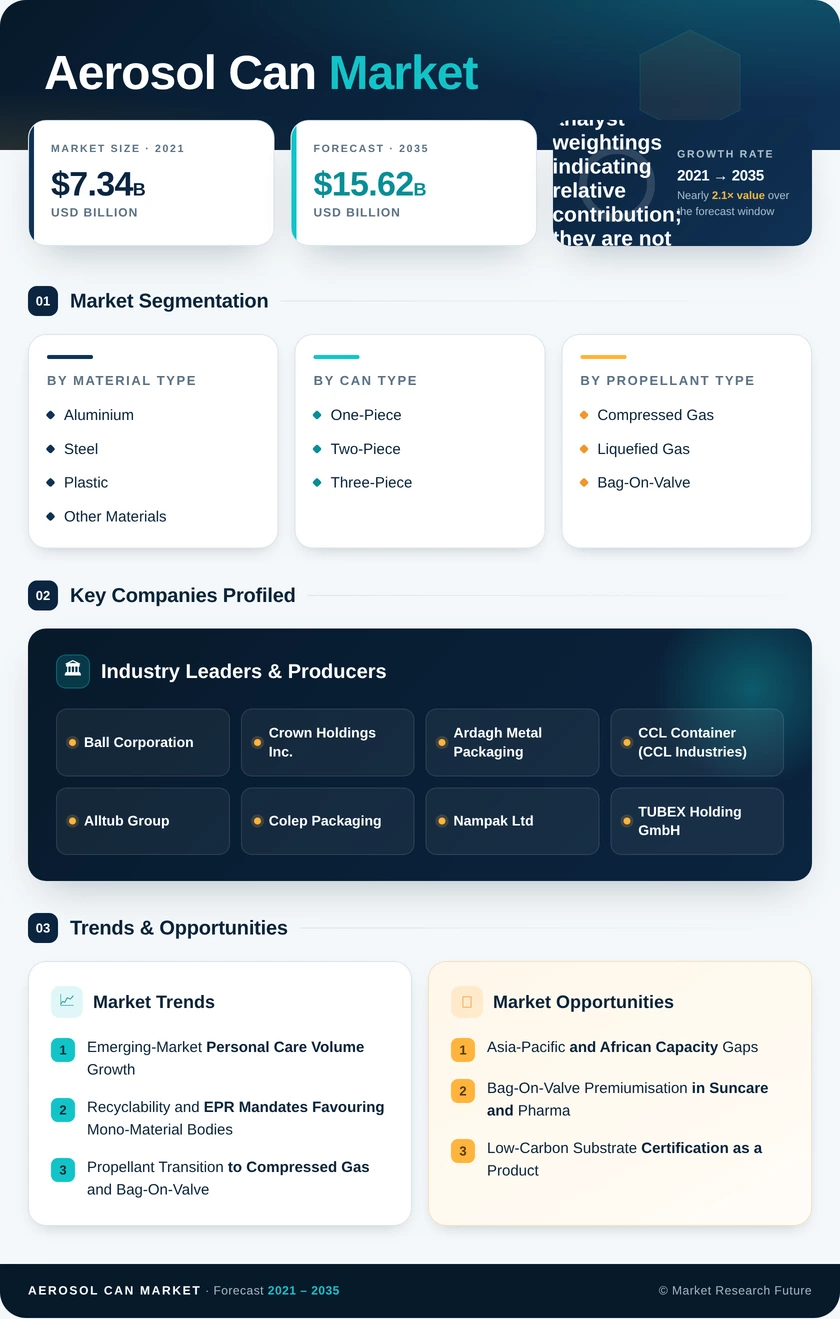
Aerosol Can Market (2026 - 2035)

ID: MRFR/PCM/1565-CR 111 Pages Varsha More Last Updated: September 22, 2026
Aerosol Can Market Research Report Information By Material Type (Aluminium, Steel, Plastic, and Other Materials), By Can Type (One-Piece, Two-Piece, and Three-Piece), By Propellant Type (Compressed Gas, Liquefied Gas, and Bag-On-Valve), By Capacity (Less Than 100ml, 101ml-300ml, 301ml-500ml, and More Than 500ml), and By End-User Industry (Personal Care and Cosmetics, Household Care, Healthcare and Pharmaceuticals, Food and Beverage, Paints and Varnishes, Automotive and Industrial, and Other End-User Industries) – Forecast Till 2035.
Aerosol Can Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.76%
2025 Market SizeUSD 8.93 Billion
2035 Market SizeUSD 15.62 Billion
Key Players
Ball Corporation
Crown Holdings Inc.
Ardagh Metal Packaging
CCL Container
Alltub Group
Colep Packaging
Opportunities
  • Asia-Pacific and African Capacity Gaps
  • Bag-On-Valve Premiumisation in Suncare and Pharma
  • Low-Carbon Substrate Certification as a Product
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Material Type | |
    2. 2.2 By Can Type | |
    3. 2.3 By Propellant Type | |
    4. 2.4 By Capacity | |
    5. 2.5 By End-User Industry | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Emerging-Market Personal Care Volume Growth | |
    2. 4.2 Recyclability and EPR Mandates Favouring Mono-Material Bodies | |
    3. 4.3 Propellant Transition to Compressed Gas and Bag-On-Valve | |
    4. 4.4 E-Commerce Driven Miniaturisation | |
    5. 4.5 Lightweighting and Low-Carbon Metal Supply | |
    6. 4.6 Two-Piece Manufacturing Capacity Investment | |
    7. 4.7 Healthcare and Pharmaceutical Spray Adoption | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Aluminium and Tinplate Price Volatility | |
    2. 5.2 VOC Limits and Hazard Reclassification | |
    3. 5.3 Substitution by Pump and Trigger Dispensers | |
    4. 5.4 Capital Intensity of New Can Lines | |
    5. 5.5 Dangerous-Goods Logistics and Insurance Cost | |
  6. 6 Opportunities | |
    1. 6.1 Asia-Pacific and African Capacity Gaps | |
    2. 6.2 Bag-On-Valve Premiumisation in Suncare and Pharma | |
    3. 6.3 Low-Carbon Substrate Certification as a Product | |
    4. 6.4 Digital Printing and Connected-Pack Data Monetisation | |
    5. 6.5 Refill and Returnable Dispensing Models | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Machine Vision and Autonomous Line Operation | |
    2. 8.2 Circularity Reporting Becomes a Contract Term | |
    3. 8.3 The Propellant Transition Reaches Scale | |
    4. 8.4 Regional Fill-Near-Market Economics Harden | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Material Type | | |
      1. 9.1.1 Aluminium | | |
      2. 9.1.2 Steel | | |
      3. 9.1.3 Plastic | | |
      4. 9.1.4 Other Materials | |
    2. 9.2 By Can Type | | |
      1. 9.2.1 One-Piece | | |
      2. 9.2.2 Two-Piece | | |
      3. 9.2.3 Three-Piece | |
    3. 9.3 By Propellant Type | | |
      1. 9.3.1 Compressed Gas | | |
      2. 9.3.2 Liquefied Gas | | |
      3. 9.3.3 Bag-On-Valve | |
    4. 9.4 By Capacity | | |
      1. 9.4.1 Less Than 100ml | | |
      2. 9.4.2 101ml-300ml | | |
      3. 9.4.3 301ml-500ml | | |
      4. 9.4.2 More Than 500ml | |
    5. 9.5 By End-User Industry | | |
      1. 9.5.1 Personal Care and Cosmetics | | |
      2. 9.5.2 Household Care | | |
      3. 9.5.3 Healthcare and Pharmaceuticals | | |
      4. 9.5.4 Food and Beverage | | |
      5. 9.5.5 Paints and Varnishes | | |
      6. 9.5.6 Automotive and Industrial | | |
      7. 9.5.7 Other End-User Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Ball Corporation | | |
      2. 10.3.2 Crown Holdings Inc. | | |
      3. 10.3.3 Ardagh Metal Packaging | | |
      4. 10.3.4 CCL Container (CCL Industries) | | |
      5. 10.3.5 Alltub Group | | |
      6. 10.3.6 Colep Packaging | | |
      7. 10.3.7 Nampak Ltd | | |
      8. 10.3.8 TUBEX Holding GmbH | | |
      9. 10.3.9 DS Containers Inc. | | |
      10. 10.3.10 Mauser Packaging Solutions | | |
      11. 10.3.11 Tecnocap Group | | |
      12. 10.3.12 Grupo Zapata | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Validation | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size & Forecast, by Revenue (USD billion), 2021–2035 | |
  16. TABLE 2 Global Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Material Type, 2021–2035 (USD billion) | |
  20. TABLE 6 Global Market Size, by Can Type, 2021–2035 (USD billion) | |
  21. TABLE 7 Global Market Size, by Propellant Type, 2021–2035 (USD billion) | |
  22. TABLE 8 Global Market Size, by Capacity, 2021–2035 (USD billion) | |
  23. TABLE 9 Global Market Size, by End-User Industry, 2021–2035 (USD billion) | |
  24. TABLE 10 Global Market Size, by Region, 2021–2035 (USD billion) | |
  25. TABLE 11 Regional Summary — Share, Value and Investment Themes, 2025 | |
  26. TABLE 12 North America Market Size, by Country, 2021–2035 (USD billion) | |
  27. TABLE 13 Europe Market Size, by Country, 2021–2035 (USD billion) | |
  28. TABLE 14 Asia-Pacific Market Size, by Country, 2021–2035 (USD billion) | |
  29. TABLE 15 South America Market Size, by Country, 2021–2035 (USD billion) | |
  30. TABLE 16 Middle East & Africa Market Size, by Country, 2021–2035 (USD billion) | |
  31. TABLE 17 North America Market Size, by Material Type, 2021–2035 (USD billion) | |
  32. TABLE 18 North America Market Size, by End-User Industry, 2021–2035 (USD billion) | |
  33. TABLE 19 Europe Market Size, by Material Type, 2021–2035 (USD billion) | |
  34. TABLE 20 Europe Market Size, by Propellant Type, 2021–2035 (USD billion) | |
  35. TABLE 21 Asia-Pacific Market Size, by Can Type, 2021–2035 (USD billion) | |
  36. TABLE 22 Asia-Pacific Market Size, by Capacity, 2021–2035 (USD billion) | |
  37. TABLE 23 South America Market Size, by End-User Industry, 2021–2035 (USD billion) | |
  38. TABLE 24 Middle East & Africa Market Size, by Material Type, 2021–2035 (USD billion) | |
  39. TABLE 25 Competitive Benchmarking Matrix, 2026 | |
  40. TABLE 26 Company Profiles — Key Players and Strategic Positioning | |
  41. TABLE 27 Recent Developments & Strategic Announcements, 2023–2025 | |
  42. TABLE 28 Report Scope & Methodology Summary | |
  43. TABLE 29 Detailed Sources and Citations Index | |
  44. TABLE 30 Segmentation Quick Reference — Dominant and Fastest Growing Segments | | LIST OF FIGURES | |
  45. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Overview | |
  46. FIGURE 2 Industry Value Chain Analysis — Substrate to Filled Unit | |
  47. FIGURE 3 Porter's Five Forces Analysis | |
  48. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 (USD billion) | |
  49. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) | |
  50. FIGURE 6 Market Share by Material Type, 2025 vs 2035 (%) | |
  51. FIGURE 7 Market Share by Can Type, 2025 (%) | |
  52. FIGURE 8 Market Share by Propellant Type, 2025 vs 2035 (%) | |
  53. FIGURE 9 Market Share by Capacity, 2025 (%) | |
  54. FIGURE 10 Market Share by End-User Industry, 2025 (%) | |
  55. FIGURE 11 Regional Market Share Distribution, 2025 (%) | |
  56. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) | |
  57. FIGURE 13 Country-Level Share within Europe, 2025 (%) | |
  58. FIGURE 14 Country-Level Share within Asia-Pacific, 2025 (%) | |
  59. FIGURE 15 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  60. FIGURE 16 Competitive Positioning Map — Scale versus Specialisation | |
  61. FIGURE 17 Propellant Transition Adoption Curve, 2021–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Material TypeAluminium; Steel; Plastic; Other MaterialsAluminium (46.7% share)Plastic (6.84% CAGR)
By Can TypeOne-Piece; Two-Piece; Three-PieceTwo-Piece (51.3% share)One-Piece (6.15% CAGR)
By Propellant TypeCompressed Gas; Liquefied Gas; Bag-On-ValveLiquefied Gas (56.3% share)Compressed Gas (6.32% CAGR)
By CapacityLess Than 100ml; 101ml-300ml; 301ml-500ml; More Than 500ml301ml-500ml (42.6% share)Less Than 100ml (6.60% CAGR)
By End-User IndustryPersonal Care and Cosmetics; Household Care; Healthcare and Pharmaceuticals; Food and Beverage; Paints and Varnishes; Automotive and Industrial; Other End-User IndustriesPersonal Care and Cosmetics (58.7% share)Healthcare and Pharmaceuticals (7.05% CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaEurope (34.2% share)Asia-Pacific (7.18% CAGR)


Market Segmentation Overview

By Material Type

Sub-SegmentKey Trend
AluminiumRecycled and inert-anode metal blends supporting low-carbon claims
SteelRetained in price-sensitive cleaner and lubricant applications
PlasticTransparent, contoured bodies enabling low-volume e-commerce launches
Other MaterialsHybrid and composite formats penalised by sortation-linked fees


Aluminium leads this dimension at 46.7% of 2025 value because impact-extrusion lines run fast, freight mass stays low, and closed-loop scrap supports the recycled-content thresholds European regulation now enforces. Plastic grows fastest at 6.84% CAGR, but from a narrow base concentrated in travel sizes and nutraceutical sprays where mould cost and shelf transparency matter more than line speed. Steel holds volume rather than share, defending cleaner and automotive applications on price. Other Materials shrink as producer-responsibility fees make multi-material bodies structurally expensive.

By Can Type

Sub-SegmentKey Trend
One-PieceHermetic extruded bodies specified for pharmaceutical and food fills.
Two-PieceDrawing-and-ironing capacity additions dominating new investment
Three-PieceWelded formats retained for large-diameter industrial sizes


Two-Piece shells hold 51.3% of 2025 value and absorb nearly all new capital because eliminating the welded side seam trims metal input and keeps lines running above 300 units per minute. One-Piece bodies post the dimension's fastest 6.15% CAGR, pulled by pharmaceutical and food customers who specify seamless hermetic integrity regardless of unit cost. Three-Piece construction persists where diameter exceeds extrusion limits, though sorting difficulty at end-of-life now carries a quantified fee penalty that accelerates its decline in consumer applications.

By Propellant Type

Sub-SegmentKey Trend
Compressed GasNitrogen and air systems removing flammability classification
Liquefied GasCost and droplet-size performance sustaining mainstream volume
Bag-On-ValveProduct-propellant separation enabling preservative-free claims


Liquefied Gas retains a 56.3% share because hydrocarbon propellants remain the cheapest route to a spray pattern consumers recognise. Compressed Gas expands at 6.32% CAGR as hazard-class removal cuts freight, warehousing and insurance costs simultaneously, making the switch a logistics decision rather than a marketing one. Bag-On-Valve stays a premium tier: higher component cost is justified only where preservative-free formulation, near-complete evacuation or any-angle dispensing carries clinical or cosmetic value.

By Capacity

Sub-SegmentKey Trend
Less Than 100mlSubscription bundles and carry-on compliance driving miniaturisation
101ml-300mlPromotional multipacks and travel-retail assortment demand
301ml-500mlCore household replenishment size with strongest shelf presence
More Than 500mlIndustrial, garage and sealant applications


The 301ml-500ml band dominates at 42.6% of 2025 value, matching how households actually consume deodorant, hairspray and air-care products. Less Than 100ml grows fastest at 6.60% CAGR because dimensional-weight freight pricing rewards compact packs, and online try-me bundles need small formats to hit target price points. The 101ml-300ml band holds promotional and travel-retail relevance, while More Than 500ml tracks construction and vehicle-maintenance cycles rather than consumer behaviour.

By End-User Industry

Sub-SegmentKey Trend
Personal Care and CosmeticsPremium, refillable and low-carbon propositions in mature markets
Household CareInsecticide and air-care demand strongest in tropical geographies
Healthcare and PharmaceuticalsPropellant approvals clearing inhalation reformulation paths
Food and BeveragePlant-based topping and cooking-spray launches
Paints and VarnishesTouch-up coatings and industrial marking applications
Automotive and IndustrialLubricants, brake cleaners and release agents
Other End-User IndustriesVeterinary, marine and specialty technical sprays


Personal Care and Cosmetics commands 58.7% of 2025 demand, but Western volume growth has flattened, pushing deodorant and hairspray brands toward premiumisation and recycled-content differentiation rather than unit expansion. Healthcare and Pharmaceuticals grows fastest at 7.05% CAGR as regulatory clearance of substitute propellants opens reformulation routes for metered-dose inhalers and nasal delivery, applications that also carry the dimension's highest realised price per unit. Household Care provides volume stability through insecticide and air-care demand, while Food and Beverage adds incremental growth from plant-based topping launches.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.