Aerosol Can Market Summary
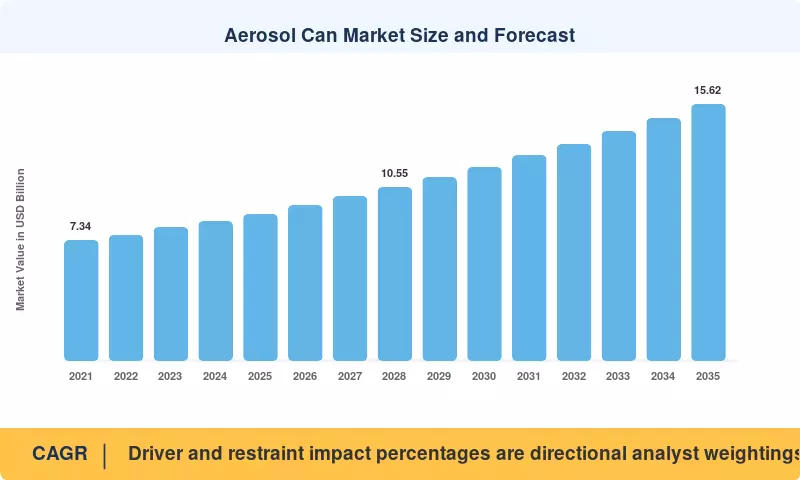
The Aerosol Can Market reached USD 8.93 billion in 2025 and opens the forecast window at USD 9.44 billion in 2026, advancing to USD 15.62 billion by 2035 at a 5.76% CAGR. Two catalysts anchor that trajectory. The European Union's Packaging and Packaging Waste Regulation, in force since early 2025, requires all packaging placed on the single market to be recyclable by 2030 and sets recycled-content thresholds that favour mono-material metal bodies over composite alternatives [4]. Parallel capital deployment in drawn-and-ironed shell capacity — roughly USD 1.4 billion committed across European, Mexican and Southeast Asian plants between 2023 and 2025 — has lifted global filling-line throughput above 300 units per minute on new installations [20].
The valve out is changing the category as technology substitutes. The 1990s workhorses, welded three-piece bodies and hydrocarbon-propelled formats fill base, are being replaced by seamless two-piece shells, nitrogen-charged compressed-gas systems and bag-on-valve inserts that keep product separate from propellant. Salvalco’s Eco-Valve (commercialised across European deodorant lines in 2024) removes flammability pictograms completely and maintains spray pattern within consumer tolerance [18]. Low-carbon aluminum supply reaffirms the pivot: ELYSIS inert-anode metal combined 50-50 with post-consumer scrap currently supports premium aerosol packaging lines, and Beiersdorf has committed to 50% recycled aluminum content across its can portfolio [19].
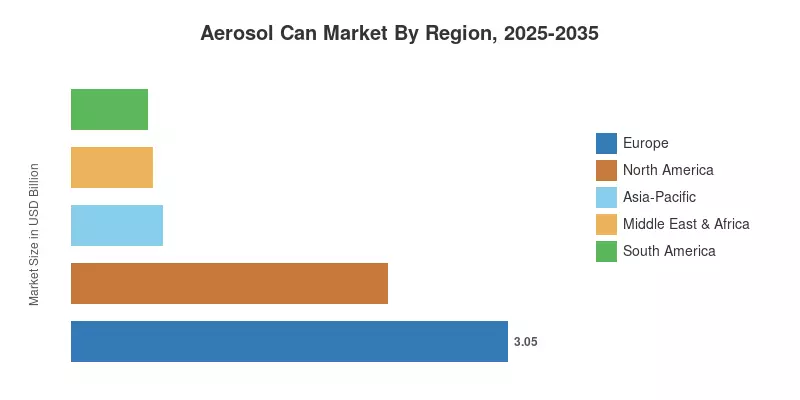
Continues regional hierarchy driven by Europe. Germany, France and Spain are dense filler networks that deliver 34.2% of 2025 global value to Europe. Asia-Pacific is compounding at 7.18% through 2035 as Chinese and Indian personal-care volumes increase. North America is the second largest market in absolute terms with USD 2.21 billion supported by dry-shampoo and household-care reformulation cycles. By 2035, the competitive dilemma will be not unit cost but compliance cost — and those providers that master both will gain disproportionate share.
Key Report Takeaways
• By Material Type
- Aluminium holds 46.7% of 2025 global value, retaining volume leadership across personal-care and food formats.
- Plastic bodies expand at a 6.84% CAGR through 2035, concentrated in travel and nutraceutical sizes.
• By Can Type
- Two-piece shells command 51.3% of 2025 value, reflecting the capital bias toward seamless drawing-and-ironing lines.
- One-piece bodies grow fastest at 6.15% CAGR, pulled by hermetic pharmaceutical and food applications.
• By Propellant Type
- Liquefied gas retains a 56.3% share of 2025 demand on cost and droplet-size advantages.
- Compressed gas advances at 6.32% CAGR as zero-VOC labelling and non-hazardous freight gain commercial weight.
• By Capacity
- The 301ml-500ml band accounts for 42.6% of 2025 value, balancing consumption convenience with shelf presence.
- Less Than 100ml packs post the category's fastest 6.60% CAGR on subscription bundling and carry-on rules.
• By End-User Industry
- Personal Care and Cosmetics represents 58.7% of 2025 demand across deodorant, hairspray and sun-care lines.
- Healthcare and Pharmaceuticals grows at 7.05% CAGR, led by metered-dose inhalers and nasal delivery.
• By Region
- Europe leads the Aerosol Can Market with 34.2% of 2025 value, anchored by regulatory-driven design upgrades
- Asia-Pacific delivers the fastest regional expansion at 7.18% CAGR through 2035
- Middle East & Africa contributes USD 0.40 billion in 2025, with Gulf contract-filling capacity scaling quickly
Aerosol Can Market Size and Forecast (2021–2035)
The market sizing merges bottom-up data on shipments of filler level with top-down validation against national aerosol production surveys published by the European Aerosol Federation and the Household & Commercial Products Association [1][2]. Historical data are audited against can-maker revenues from Ball Corporation, Crown Holdings and Ardagh Metal Packaging, deflated to constant 2025 USD and cross-checked against Eurostat packaging-waste tonnage [6][7][8][12]. Forecast values use a substrate-weighted price index to unit volume predictions. Propellant transition costs are modeled individually for the Aerosol Can Market from 2027 forward.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


