Percutaneous Coronary Intervention Market 摘要
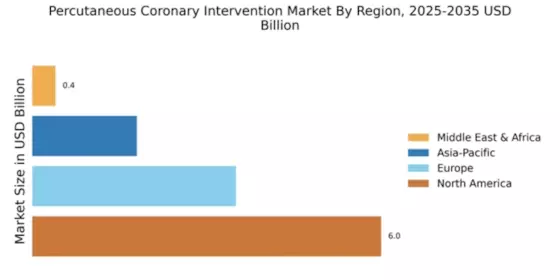
全球经皮冠状动脉介入市场的规模在2024年估计为117亿美元,预计市场将从2025年的128.7亿美元增长到2035年的334.8亿美元,在2025年至2035年的预测期内注册年均增长率为10.03%。北美市场领先,市场份额超过51.28%,产生约60亿美元的收入。
心血管疾病的发病率上升、老龄化人口增加以及支架技术和微创手术的持续进步正在加速对经皮冠状动脉介入的需求,改善治疗结果,同时支持在医疗系统中的更广泛采用。
根据世界卫生组织,心血管疾病每年导致约1790万人死亡,占全球死亡人数的32%,这进一步强调了对先进PCI程序和早期心脏干预技术的迫切需求。
主要市场趋势和亮点
经皮冠状动脉介入市场因技术进步和疾病流行率上升而有望实现显著增长。
- 北美在2024年占据了51.28%的PCI市场收入,保持区域领导地位。
- 欧洲在2024年创造了35亿美元的收入,贡献了大约29.91%的全球市场份额。
- 医院的市场份额估计为58%,这得益于全球心血管手术量的增加。
- 心血管疾病每年导致约1790万人死亡,加速了全球对PCI技术的需求。
市场规模与预测
| 2024市场规模 | 117 (十亿美元) |
| 2035市场规模 | 334.8 (十亿美元) |
| 年均增长率 (2025 - 2035) | 10.03% |
主要参与者
一些主要参与者包括雅培(美国)、波士顿科学(美国)、美敦力(美国)、强生(美国)、B. Braun(德国)、Terumo(日本)、嘉德医疗(美国)、西门子医疗(德国)、飞利浦(荷兰)。



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


