Virtual Mobile Infrastructure Market (2026 - 2035)

ID: MRFR/ICT/7250-HCR 110 Pages Ankit Gupta Last Updated: September 15, 2026
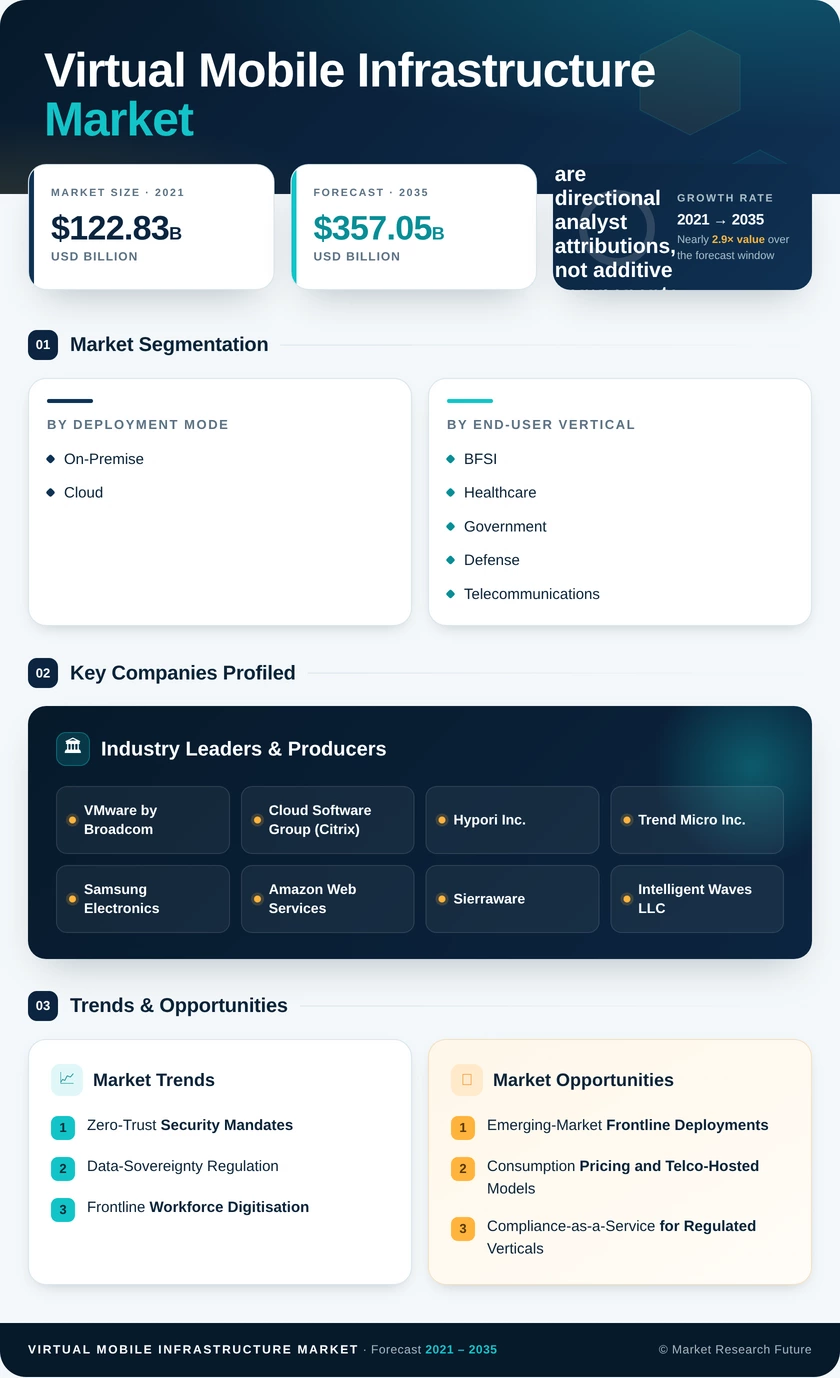
Virtual Mobile Infrastructure Market Size, Share and Research Report By Deployment Mode (On-Premise, Cloud), By End-User Vertical (BFSI, Healthcare, Government & Defense, IT & Telecom, Manufacturing, Others) and By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Industry Forecast to 2035
Virtual Mobile Infrastructure Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.9%
2025 Market SizeUSD 166.92 Billion
2035 Market SizeUSD 357.05 Billion
Key Players
VMware by Broadcom
Cloud Software Group
Hypori Inc.
Trend Micro Inc.
Samsung Electronics
Amazon Web Services
Opportunities
  • Emerging-Market Frontline Deployments
  • Consumption Pricing and Telco-Hosted Models
  • Compliance-as-a-Service for Regulated Verticals
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Deployment Mode | |
    2. 2.2 By End-user Vertical | |
    3. 2.3 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Zero-Trust Security Mandates | |
    2. 4.2 Data-Sovereignty Regulation | |
    3. 4.3 Frontline Workforce Digitisation | |
    4. 4.4 Cloud Delivery Economics | |
    5. 4.5 Handset Fleet Cost Avoidance | |
    6. 4.6 5G and eSIM Connectivity Density | |
    7. 4.7 Clinical Mobility Compliance | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Network Dependency and Latency | |
    2. 5.2 Concurrency-Based Licence Costs | |
    3. 5.3 Feature Parity Gaps with Native Apps | |
    4. 5.4 Identity and Endpoint Stack Integration | |
    5. 5.5 Cross-Border Hosting Constraints | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Frontline Deployments | |
    2. 6.2 Consumption Pricing and Telco-Hosted Models | |
    3. 6.3 Compliance-as-a-Service for Regulated Verticals | |
    4. 6.4 Sovereign Public-Sector Hosting | |
    5. 6.5 AI Workloads on Server-Hosted Sessions | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Server-Side AI and Session Orchestration | |
    2. 8.2 Platform Economics and Consumption Pricing | |
    3. 8.3 Edge Hosting and Connectivity Densification | |
    4. 8.4 Device Lifecycle Reporting and Sustainability Disclosure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Deployment Mode | | |
      1. 9.1.1 On-Premise | | |
      2. 9.1.2 Cloud | |
    2. 9.2 By End-user Vertical | | |
      1. 9.2.1 BFSI | | |
      2. 9.2.2 Healthcare | | |
      3. 9.2.3 Government and Defense | | |
      4. 9.2.4 Telecommunications and IT | | |
      5. 9.2.5 Manufacturing | | |
      6. 9.2.6 Other End-User Verticals | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Virtual Mobile Infrastructure Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Virtual Mobile Infrastructure Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Global Virtual Mobile Infrastructure Market – Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Global Virtual Mobile Infrastructure Market – Restraint Impact Analysis, 2026–2035 | |
  19. TABLE 5 Global Virtual Mobile Infrastructure Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Virtual Mobile Infrastructure Market Size, by End-user Vertical, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Virtual Mobile Infrastructure Market Size, by Region, 2021–2035 (USD Billion) | |
  22. TABLE 8 North America Virtual Mobile Infrastructure Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 Europe Virtual Mobile Infrastructure Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Asia-Pacific Virtual Mobile Infrastructure Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 South America Virtual Mobile Infrastructure Market Size, by Country, 2021–2035 (USD Billion) | |
  26. TABLE 12 Middle East & Africa Virtual Mobile Infrastructure Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 North America Virtual Mobile Infrastructure Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Virtual Mobile Infrastructure Market Size, by End-user Vertical, 2021–2035 (USD Billion) | |
  29. TABLE 15 Europe Virtual Mobile Infrastructure Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  30. TABLE 16 Europe Virtual Mobile Infrastructure Market Size, by End-user Vertical, 2021–2035 (USD Billion) | |
  31. TABLE 17 Asia-Pacific Virtual Mobile Infrastructure Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  32. TABLE 18 Asia-Pacific Virtual Mobile Infrastructure Market Size, by End-user Vertical, 2021–2035 (USD Billion) | |
  33. TABLE 19 South America Virtual Mobile Infrastructure Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  34. TABLE 20 South America Virtual Mobile Infrastructure Market Size, by End-user Vertical, 2021–2035 (USD Billion) | |
  35. TABLE 21 Middle East & Africa Virtual Mobile Infrastructure Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  36. TABLE 22 Middle East & Africa Virtual Mobile Infrastructure Market Size, by End-user Vertical, 2021–2035 (USD Billion) | |
  37. TABLE 23 Competitive Benchmarking Matrix – Global Virtual Mobile Infrastructure Market, 2026 | |
  38. TABLE 24 Company Profiles – Key Players, Global Virtual Mobile Infrastructure Market | |
  39. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 | |
  40. TABLE 26 Report Scope & Methodology Summary | |
  41. TABLE 27 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  42. FIGURE 1 Global Virtual Mobile Infrastructure Market – Market Dynamics Overview | |
  43. FIGURE 2 Industry Value Chain Analysis | |
  44. FIGURE 3 Porter's Five Forces Analysis | |
  45. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  46. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  47. FIGURE 6 Market Share by Deployment Mode, 2025 vs 2035 (%) | |
  48. FIGURE 7 Market Share by End-user Vertical, 2025 (%) | |
  49. FIGURE 8 Fastest Growing End-user Verticals by CAGR, 2026–2035 (%) | |
  50. FIGURE 9 Regional Market Share, 2025 (%) | |
  51. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) | |
  52. FIGURE 11 North America Country-Level Share, 2025 (%) | |
  53. FIGURE 12 Asia-Pacific Country-Level Growth Comparison, 2026–2035 (%) | |
  54. FIGURE 13 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  55. FIGURE 14 Vendor Positioning Matrix – Breadth versus Accreditation Depth

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Deployment ModeOn-Premise; CloudCloud (61.5% share, 2025)Cloud (9.1% CAGR, 2026–2035)
By End-user VerticalBFSI; Healthcare; Government and Defense; Telecommunications and IT; Manufacturing; Other End-User VerticalsBFSI (24.6% share, 2025)Healthcare (9.4% CAGR, 2026–2035)


Market Segmentation Overview

By Deployment Mode

Sub-SegmentKey Trend
On-PremiseRetained for classified, central-bank and national health workloads under multi-year accreditation cycles
CloudConsumption-priced hosting displacing owned server estates; carrier edge sites emerging as a second supply channel


Cloud holds 61.5% of 2025 revenue and grows fastest at 9.1% annually, because concurrency-based buying matches how shift-driven workforces consume sessions and removes the capital approval step that stalls On-Premise expansion. On-Premise does not disappear; defence and central-bank buyers specify physical custody as a procurement condition, and their accreditation cycles run five to seven years, which locks in a durable installed base. Large accounts increasingly split the estate, running regulated workloads on-premise while general workforce sessions move to hosted capacity.

By End-user Vertical

Sub-SegmentKey Trend
BFSICommunications surveillance and trade-capture obligations keep session data inside supervised infrastructure
HealthcareShared clinical handsets cleared between shifts without touching clinician personal content
Government and DefenseZero-trust deadlines drive device-issuance avoidance across cleared and civilian agencies
Telecommunications and ITOutsourced contact-centre seats converted to hosted sessions for rapid scaling
ManufacturingContract and seasonal workforce onboarding without hardware provisioning
Other End-User VerticalsRetail, logistics and education deployments driven by turnover economics


BFSI leads at 24.6% share because banking supervisors examine the communication channel itself, and hosted delivery keeps chat and trade records inside auditable infrastructure rather than on a trader's handset. Healthcare grows fastest at 9.4% as hospitals standardise on shared devices that must be wiped between shifts under clinical safety documentation requirements. Government and Defense contributes the largest absolute public-sector spend, while Manufacturing and Other End-User Verticals expand in step with seasonal hiring rather than regulation, giving them a more cyclical demand profile than the regulated verticals above them.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.