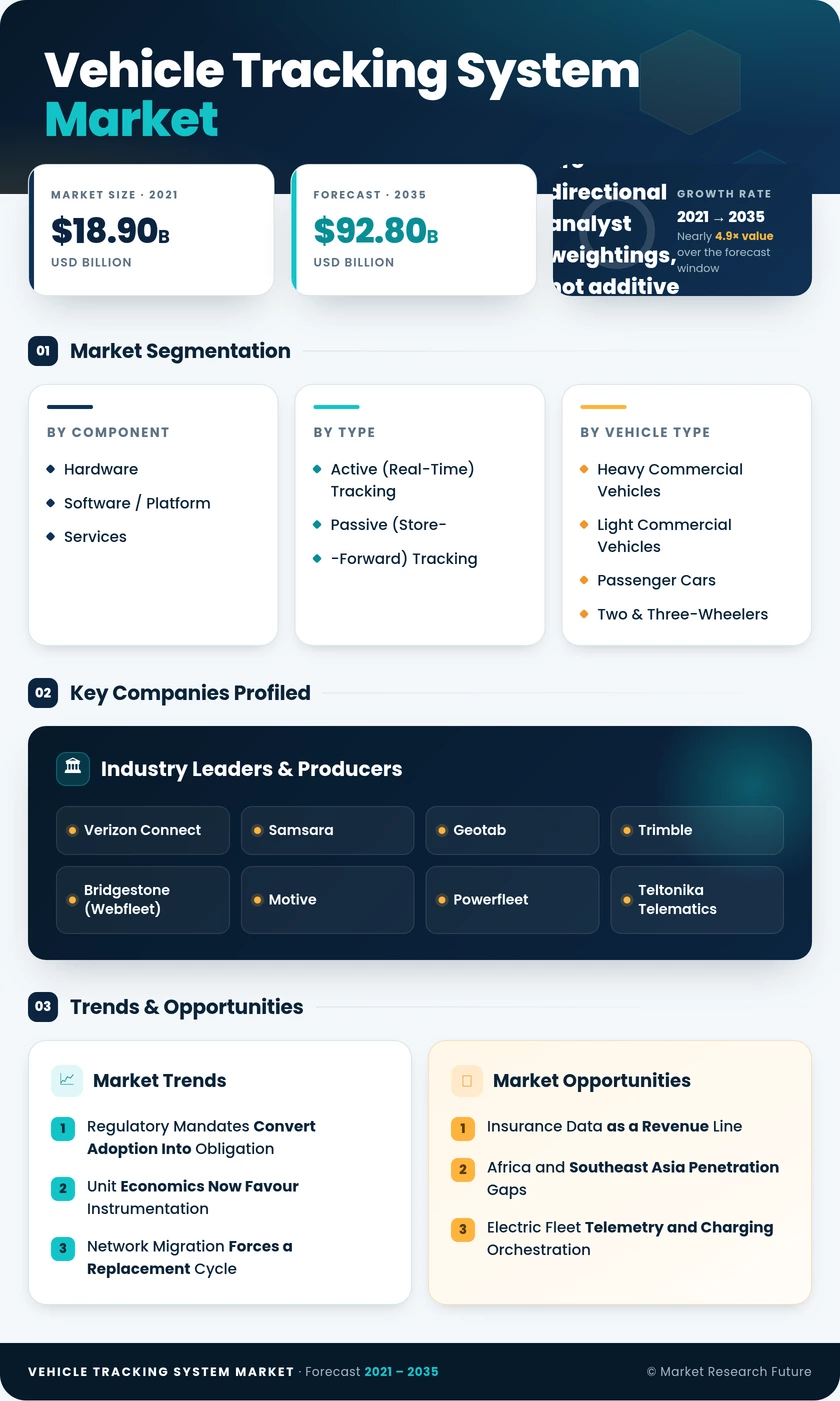
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Hardware; Software / Platform; Services | Hardware | Software / Platform |
| By Type | Active (Real-Time) Tracking; Passive (Store-and-Forward) Tracking | Active (Real-Time) Tracking | Active (Real-Time) Tracking |
| By Vehicle Type | Heavy Commercial Vehicles; Light Commercial Vehicles; Passenger Cars; Two & Three-Wheelers | Heavy Commercial Vehicles | Two & Three-Wheelers |
| By End-Use Industry | Transportation & Logistics; Insurance; Construction & Mining; Government & Public Transit; Retail & Distribution | Transportation & Logistics | Insurance |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Hardware | LTE Cat-M1 and NB-IoT modules replacing retired 2G/3G units at falling unit prices |
| Software / Platform | Open APIs and marketplace ecosystems becoming the primary retention mechanism |
| Services | Installation networks, monitoring centres and recovery operations differentiating emerging-market vendors |
Value is migrating steadily from the device to the dashboard. Vendors that once competed on modem specifications now compete on how quickly a dispatcher can act on an exception, and that shift is reshaping both gross margins and acquisition multiples across the vendor landscape.
By Type
| Sub-Segment | Key Trend |
| Active (Real-Time) Tracking | Continuous streaming becomes default as connectivity costs fall and latency expectations tighten |
| Passive (Store-and-Forward) Tracking | Retained for low-value assets, seasonal equipment and periodic compliance audits |
Real-time architectures absorb almost all new deployment volume. Passive systems persist where the asset value cannot justify a recurring data plan, though multi-year battery tags are gradually blurring the distinction between the two categories.
By Vehicle Type
| Sub-Segment | Key Trend |
| Heavy Commercial Vehicles | Compliance mandates and premium subscription tiers sustain revenue leadership |
| Light Commercial Vehicles | Delivery van fleet expansion drives the largest absolute unit additions |
| Passenger Cars | Insurance telematics and recovery services widen the consumer-adjacent base |
| Two & Three-Wheelers | Gig delivery formalisation across South and Southeast Asia creates high-volume, low-ARPU demand |
Regulation concentrates on the heaviest classes, but growth concentrates on the lightest. Two-wheeler tracking in particular reflects a different commercial model entirely — cents-per-month pricing at enormous scale, with monetisation coming from lending, insurance and platform data rather than the subscription itself.
By End-Use Industry
| Sub-Segment | Key Trend |
| Transportation & Logistics | Integration with transport management and customer ETA systems deepens |
| Insurance | Behaviour-based underwriting and claims validation scale into commercial lines |
| Construction & Mining | Utilisation tracking and proximity safety extend beyond on-road assets |
| Government & Public Transit | Service reliability reporting and public accountability drive procurement |
| Retail & Distribution | Cold chain auditability and direct-to-consumer delivery visibility expand requirements |
Buying centres are diversifying. Where fleet managers once held sole authority, procurement now routinely involves risk, sustainability and finance functions, each with distinct data requirements that vendors must satisfy within a single platform.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA