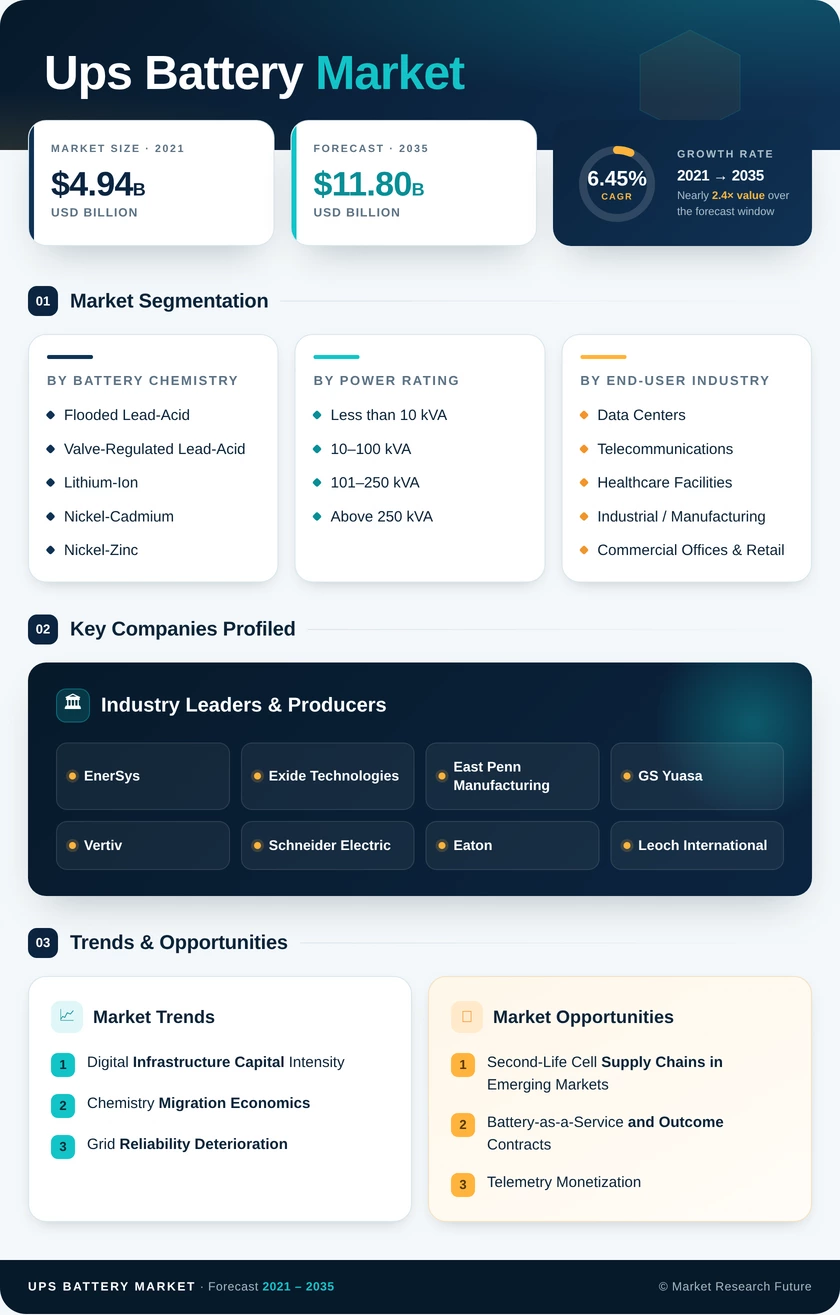
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Battery Chemistry | Flooded Lead-Acid, Valve-Regulated Lead-Acid, Lithium-Ion, Nickel-Cadmium, Nickel-Zinc, Others | Valve-Regulated Lead-Acid | Nickel-Zinc |
| By Power Rating | Less than 10 kVA, 10–100 kVA, 101–250 kVA, Above 250 kVA | 10–100 kVA | Above 250 kVA |
| By End-User Industry | Data Centers, Telecommunications, Healthcare Facilities, Industrial / Manufacturing, Commercial Offices & Retail, Residential & Small Office, Others | Data Centers | Residential & Small Office |
| By Sales Channel | Original Equipment Manufacturer, After-Market / Replacement | After-Market / Replacement | After-Market / Replacement |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Middle East & Africa |
Market Segmentation Overview
By Battery Chemistry
| Sub-Segment | Key Trend |
| Flooded Lead-Acid | Retained in utility substations and heavy industry where footprint is unconstrained |
| Valve-Regulated Lead-Acid | Defends share through like-for-like replacement, not new-build specification |
| Lithium-Ion | Default for greenfield hyperscale; factory-integrated cabinets shorten commissioning |
| Nickel-Cadmium | Niche strength in extreme temperature and offshore environments |
| Nickel-Zinc | Fastest chemistry growth, clearing permitting where lithium stalls |
| Others | Sodium-ion and supercapacitor hybrids in early field trials |
Chemistry is where value migrates fastest. Lead-acid keeps volume through the installed base while lithium and nickel-zinc capture the specification decisions that determine share a decade out.
By Power Rating
| Sub-Segment | Key Trend |
| Less than 10 kVA | Consumer and small-office demand lifted by remote work and rooftop solar |
| 10–100 kVA | Broadest building coverage; the volume backbone of commercial demand |
| 101–250 kVA | Mid-enterprise refresh cycles tied to server consolidation |
| Above 250 kVA | Fastest growth as hyperscale operators consolidate into larger blocks |
Rating bands correlate tightly with building typology. The mid band carries breadth; the top band carries momentum and increasingly sets chemistry norms for everyone else.
By End-User Industry
| Sub-Segment | Key Trend |
| Data Centers | AI density lifts stored-energy requirement per square metre |
| Telecommunications | 5G small cells and tower autonomy sustain unit volume |
| Healthcare Facilities | Uptime mandates for imaging and critical care drive scheduled refresh |
| Industrial / Manufacturing | Power quality protection for process continuity |
| Commercial Offices & Retail | Building management and access control resilience |
| Residential & Small Office | Fastest end-user growth; pairing with home solar and storage |
| Others | Transport, defence and education deployments |
End-user mix has tilted decisively toward digital infrastructure, but the fastest percentage growth now sits at the smallest end of the demand curve.
By Sales Channel
| Sub-Segment | Key Trend |
| Original Equipment Manufacturer | Integrated cabinet bundling ties the battery to the frame warranty |
| After-Market / Replacement | Higher-margin annuity, pressured by condition-based service intervals |
Channel dynamics turn on who owns the telemetry. Whoever reads the health data controls the timing of the next purchase order.
By Region
| Sub-Segment | Key Trend |
| North America | Interconnection constraints and tariff-driven sourcing realignment |
| Europe | Efficiency directive compliance shaping chemistry preference |
| Asia-Pacific | Largest region; manufacturing depth lowers delivered cost |
| South America | Colocation entry concentrated in Brazil |
| Middle East & Africa | Fastest growth on sovereign cloud and second-life economics |
Regional divergence is widening. Mature markets optimize for footprint and disclosure; growth markets optimize for autonomy and delivered cost.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA