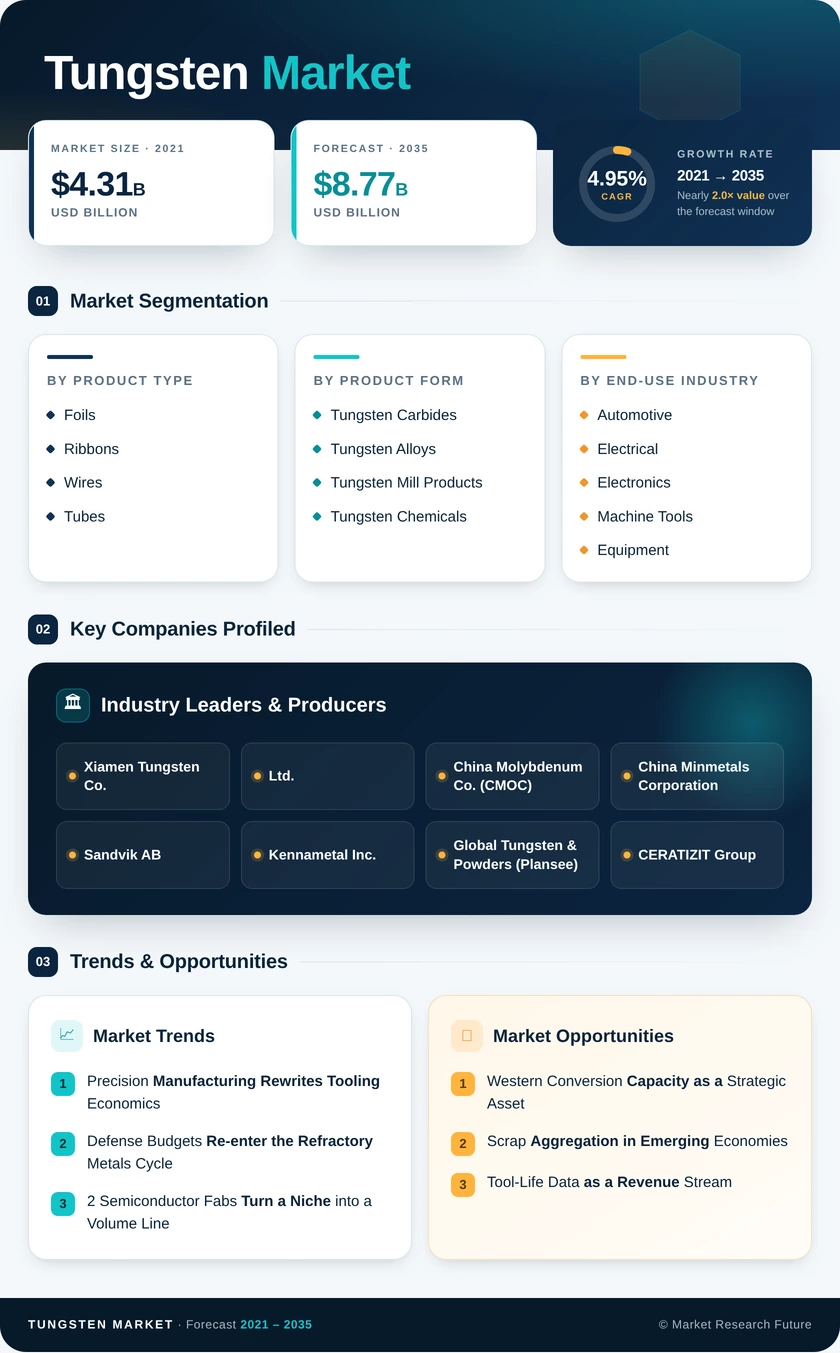
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Foils, Ribbons, Wires, Tubes | Wires | Tubes |
| By Product Form | Tungsten Carbides, Tungsten Alloys, Tungsten Mill Products, Tungsten Chemicals | Tungsten Carbides | Tungsten Chemicals |
| By End-Use Industry | Automotive, Electrical and Electronics, Machine Tools and Equipment, Aerospace and Defense, Other End-User Industries | Automotive | Other End-User Industries |
| By Geography | Asia-Pacific, North America, Europe, South America, Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Foils | Radiation shielding and electronics packaging demand widening beyond legacy uses |
| Ribbons | Steady replacement demand from lighting, vacuum and sensor assemblies |
| Wires | EDM and furnace element consumption anchored by automation-driven machine uptime |
| Tubes | Aerospace propulsion qualification driving the steepest order growth. |
Product type demand splits cleanly between high-volume consumables and low-volume, high-specification components. Wire carries the tonnage; tube carries the margin story.
By Product Form
| Sub-Segment | Key Trend |
| Tungsten Carbides | Cutting-tool penetration still rising against high-speed steel across emerging economies. |
| Tungsten Alloys | Defense penetrator and shielding demand tracking NATO expenditure commitments |
| Tungsten Mill Products | Electrode and sputtering-target demand tied to display and photovoltaic capacity |
| Tungsten Chemicals | Semiconductor deposition and catalyst applications commanding steep purity premiums |
Form segmentation is where value concentration becomes visible. Carbide dominates tonnage while chemicals capture disproportionate value per tonne, a divergence that will widen through 2035.
By End-Use Industry
| Sub-Segment | Key Trend |
| Automotive | EV structural machining lifting tooling intensity per vehicle |
| Electrical and Electronics | Advanced node fab construction locking in long-cycle chemical demand |
| Machine Tools and Equipment | Industrial capex recovery restoring consumable order volumes |
| Aerospace and Defense | Hypersonic and armour programmes creating sticky multi-year offtake |
| Other End-User Industries | Battery, medical imaging and fusion research forming the fastest-compounding pool |
End-use analysis shows a market where cyclical sectors set the volume baseline while defense and electronics set the growth rate. Buyers modelling long-term supply should weight the latter more heavily than tonnage share alone suggests.
By Geography
| Sub-Segment | Key Trend |
| Asia-Pacific | Conversion capacity concentration sustaining both dominance and fastest growth. |
| North America | Defense-funded domestic refining rebuilding a long-dormant supply base |
| Europe | Regulatory benchmarks under the Critical Raw Materials Act forcing structural change. |
| South America | Mining capex cycles driving consumable demand with high beta to commodity prices. |
| Middle East & Africa | Formalised artisanal supply and industrial diversification programmes expanding the base |
Geographic structure reflects processing capacity rather than reserves, which is why regional shares shift slowly despite active mine development elsewhere.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA