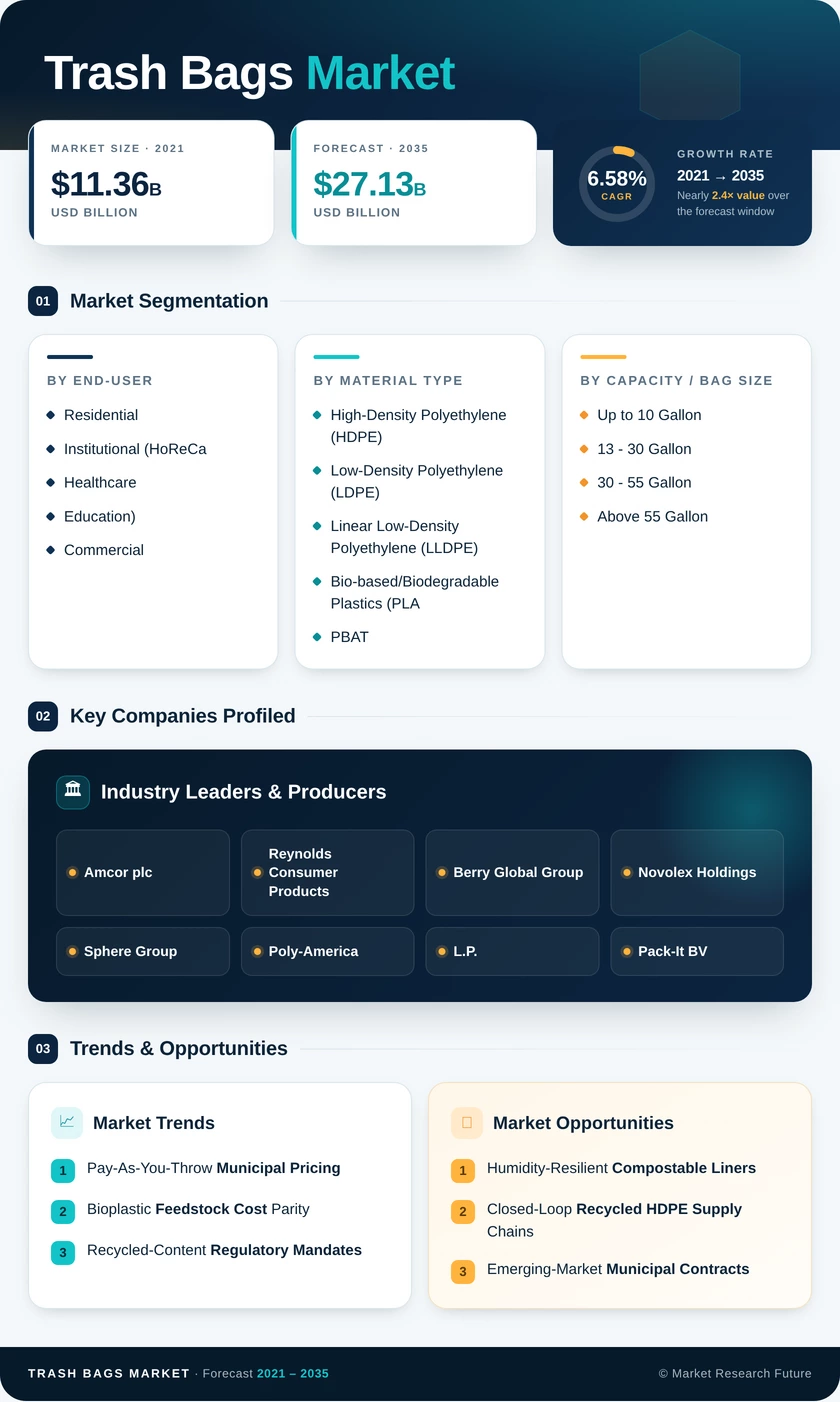
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By End-user | Residential; Institutional (HoReCa, Healthcare, Education); Commercial and Industrial | Residential — 49.5% share (2025) | Institutional (HoReCa, Healthcare, Education) — 7.20% CAGR (2026–2035) |
| By Material Type | High-Density Polyethylene (HDPE); Low-Density Polyethylene (LDPE); Linear Low-Density Polyethylene (LLDPE); Bio-based/Biodegradable Plastics (PLA, PBAT, PHA) | Linear Low-Density Polyethylene (LLDPE) — 41.0% share (2025) | Bio-based/Biodegradable Plastics (PLA, PBAT, PHA) — 7.39% CAGR (2026–2035) |
| By Capacity / Bag Size | Up to 10 Gallon; 13 - 30 Gallon; 30 - 55 Gallon; Above 55 Gallon | Up to 10 Gallon — 44.9% share (2025) | 30 - 55 Gallons — 7.37% CAGR (2026–2035) |
| By Sales Channel | Retail (Supermarkets, Convenience, Online); B2B / Institutional Procurement; Distribution / Wholesale | Retail (Supermarkets, Convenience, Online) — 35.2% share (2025) | B2B / Institutional Procurement — 7.16% CAGR (2026–2035) |
Market Segmentation Overview
By End-user
| Sub-Segment | Key Trend |
| Residential | Metered disposal billing shifts households toward smaller, certified formats. |
| Institutional (HoReCa, Healthcare, Education) | Infection-control codes and campus recycled-content pledges drive premium specification. |
| Commercial and Industrial | Warehouse and retail back-of-house consolidation raises per-site liner volume. |
Residential buyers lead this dimension at 49.5% of 2025 revenue because household count, not policy, sets the baseline, and direct subscription channels have added replenishment frequency on top of that base. Institutional demand across HoReCa, healthcare and education grows fastest at a 7.20% CAGR, since hospitals must buy leak-proof, colour-segregated liners to satisfy auditable infection-control codes and universities have committed to fully recycled-content procurement. Commercial and Industrial volume tracks logistics footprint rather than regulation, which makes it steady but slower.
By Material Type
| Sub-Segment | Key Trend |
| High-Density Polyethylene (HDPE) | High-purity AI-sorted reclaim makes it the preferred mandate-compliant substrate. |
| Low-Density Polyethylene (LDPE) | Retains low-gauge dry-waste niches but cedes share to metallocene alternatives |
| Linear Low-Density Polyethylene (LLDPE) | Downgauging economics deliver equal strength at lower resin consumption |
| Bio-based/Biodegradable Plastics (PLA, PBAT, PHA) | Feedstock cost parity unlocks municipal compostable procurement |
Linear Low-Density Polyethylene (LLDPE) holds 41.0% of 2025 revenue because metallocene grades let converters cut gauge roughly 30% without losing puncture resistance, and resin is the dominant input cost. Bio-based/Biodegradable Plastics (PLA, PBAT, PHA) grow fastest at a 7.39% CAGR now that PLA and PBAT feedstock matches LDPE pricing, removing the budget objection that previously kept municipal tenders on conventional film. High-Density Polyethylene (HDPE) gains where recycled-content rules bite, while Low-Density Polyethylene (LDPE) slowly loses ground.
By Capacity / Bag Size
| Sub-Segment | Key Trend |
| Up to 10 Gallon | Kitchen and bathroom placement plus metered-disposal downsizing sustain volume leadership. |
| 13 - 30 Gallon | Standard kerbside set-out size benefiting from retail multipack promotion |
| 30 - 55 Gallon | Commercial collection-point consolidation drives the fastest expansion. |
| Above 55 Gallon | Heavy 1.5-mil gauges serve construction, hospitality and event venues. |
Up to 10 Gallon formats lead at 44.9% of 2025 revenue on sheer unit frequency, and volume-based municipal billing reinforces that lead by rewarding households that set out less. The 30 - 55 Gallon bracket grows fastest at a 7.37% CAGR because warehouses, full-service restaurants and retailers are consolidating scattered collection points into fewer large containers, particularly where food-waste diversion rules apply. Above 55 Gallon liners carry the highest per-unit price but address a structurally narrow project-driven base.
By Sales Channel
| Sub-Segment | Key Trend |
| Retail (Supermarkets, Convenience, Online) | Private-label and marketplace brands compress branded price realisation |
| B2B / Institutional Procurement | Group purchasing agreements embed recycled-content floors into multi-year contracts. |
| Distribution / Wholesale | Bulk case packs cut per-unit cost 12–15% against retail formats. |
Retail (Supermarkets, Convenience, Online) remains the largest channel at 35.2% of 2025 revenue, though marketplace private labels undercutting branded film by more than twenty percent have made share defence expensive. B2B / Institutional Procurement grows fastest at a 7.16% CAGR because group purchasing organisations now write verified recycled-content minimums into tenders, which favours converters holding their own reclaim capacity. Distribution / Wholesale holds substantial value on case-pack economics that high-volume foodservice and facilities buyers cannot replicate at retail.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA