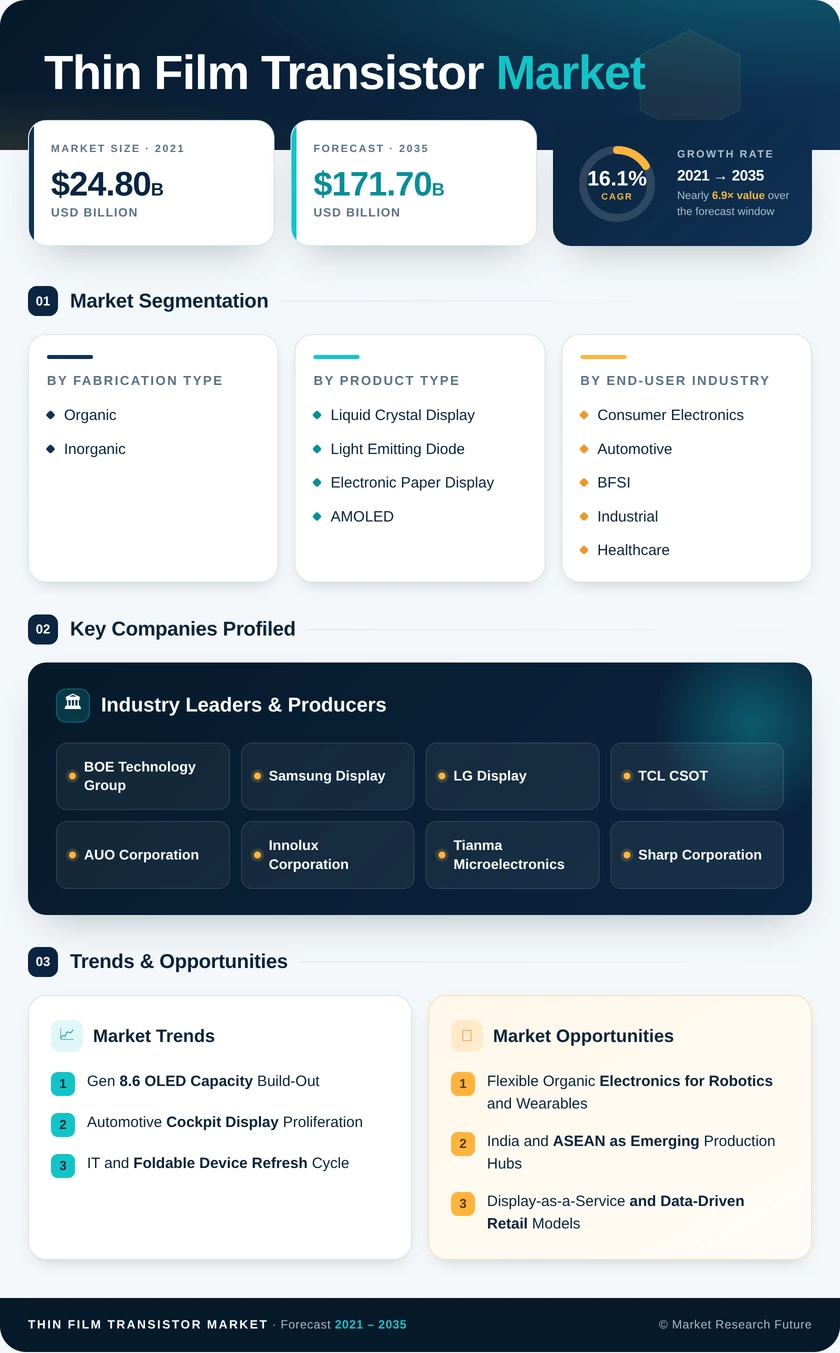
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Fabrication Type | Organic; Inorganic | Inorganic (88.7% share) | Organic (24.3% CAGR) |
| By Product Type | Liquid Crystal Display; Light Emitting Diode; Electronic Paper Display; AMOLED | Liquid Crystal Display (47.9% share) | AMOLED (21.8% CAGR) |
| By End-user Industry | Consumer Electronics; Automotive; BFSI; Industrial; Healthcare; Other End-user Industries | Consumer Electronics (54.6% share) | Automotive (20.7% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America (34.2% share) | Asia-Pacific (18.4% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Organic | Printed, low-temperature transistors for flexible sensors, e-paper and wearables |
| Inorganic | Migration from a-Si toward LTPS, IGZO and hybrid LTPO backplanes |
Inorganic TFTs lead with an 88.7% share because a-Si, LTPS and oxide lines are depreciated, high-yield and qualified for every panel type. Organic TFTs grow fastest at a 24.3% CAGR since they can be printed on plastic below 150 °C, suiting bendable sensors and e-paper. Their mobility and stability limits keep them out of mainstream video displays for now.
| Sub-Segment | Key Trend |
|---|
| Liquid Crystal Display | Capacity consolidating in China as legacy fabs close |
| Light Emitting Diode | Active-matrix mini-LED backlights in premium TVs and notebooks |
| Electronic Paper Display | Subscription-based shelf labels and low-power signage |
| AMOLED | Gen 8.6 lines bringing OLED into notebooks and tablets |
Liquid Crystal Display holds the lead at a 47.9% share on television and monitor volume, even as older lines in Japan and Korea shut. AMOLED grows fastest at a 21.8% CAGR because the new Gen 8.6 fabs from Samsung Display, BOE and Visionox target IT devices that demand LTPO backplanes. Electronic Paper Display gains from retailers adopting shelf labels that consume no power for static content.
| Sub-Segment | Key Trend |
|---|
| Consumer Electronics | OLED migration in tablets, notebooks and foldables |
| Automotive | Pillar-to-pillar and multi-screen EV cockpits |
| BFSI | Kiosk, ATM and payment-terminal upgrades |
| Industrial | Rugged HMI with long supply commitments |
| Healthcare | Digital radiography detectors and diagnostic monitors |
| Other End-user Industries | Aerospace, defense and education displays |
Consumer Electronics leads with a 54.6% share, driven by smartphone, television and notebook refresh cycles. Automotive grows fastest at a 20.7% CAGR as electric vehicles add larger, wide-temperature-rated displays that need automotive-qualified LTPS and oxide arrays. Healthcare follows closely as hospitals replace film radiography with TFT-based flat panel detectors.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA