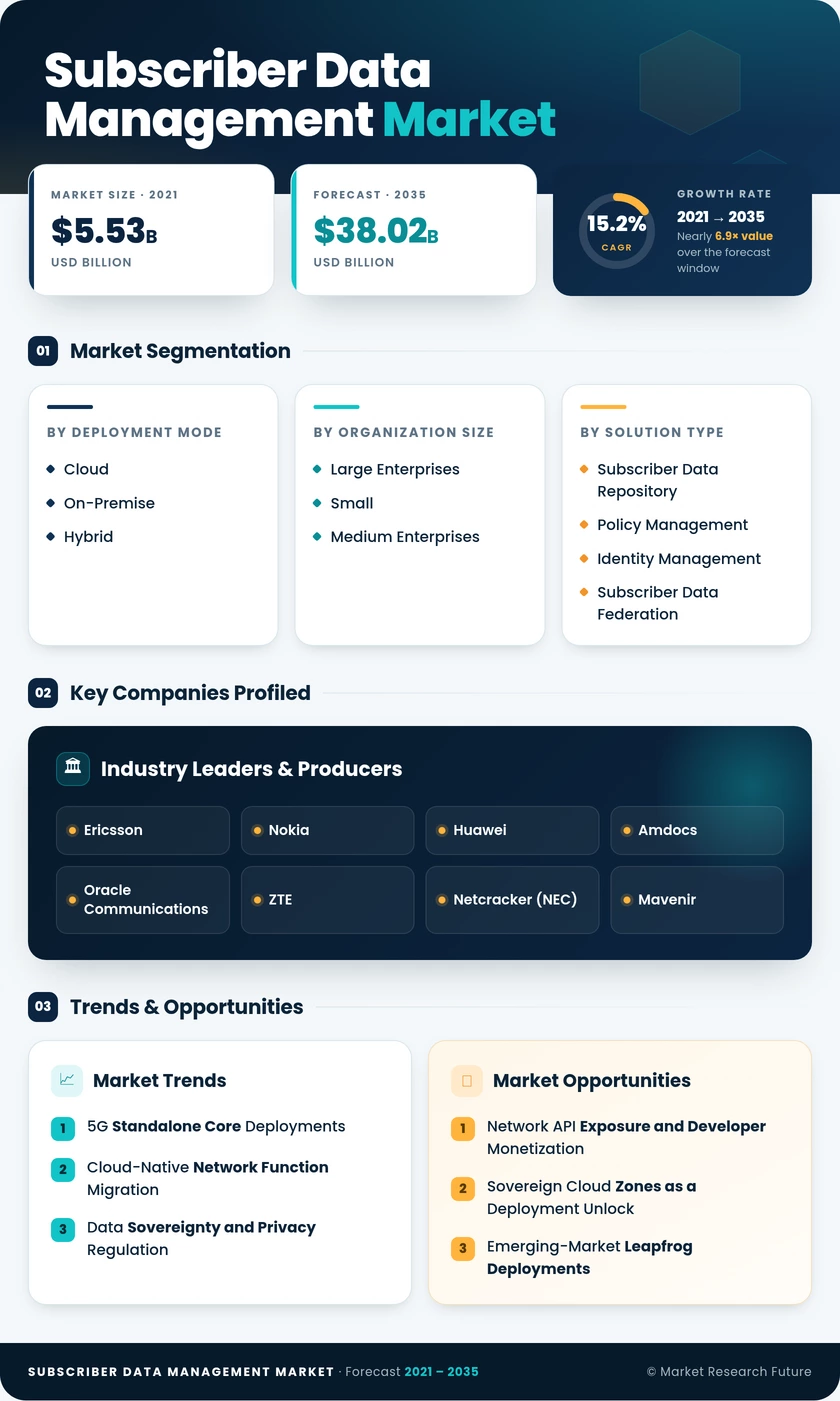
Subscriber Data Management Market (2026 - 2035)

ID: MRFR/ICT/4901-HCR 100 Pages Nirmit Biswas Last Updated: September 15, 2026
Subscriber Data Management Market Size, Share and Research Report By Deployment Mode (Cloud, On-Premise, Hybrid), By Organization Size (Large Enterprises, SMEs), By Solution Type (Subscriber Data Repository, Policy Management, Identity Management, Data Federation), By Network Type (2G/3G, 4G/LTE, 5G Non-Standalone, 5G Standalone), By End-User (MNOs, MVNOs, Enterprises/IoT Service Providers) and By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Industry Forecast to 2035
Subscriber Data Management Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)15.2%
2025 Market SizeUSD 9.14 Billion
2035 Market SizeUSD 38.02 Billion
Key Players
Ericsson
Nokia
Huawei
Amdocs
Oracle Communications
ZTE
Opportunities
  • Network API Exposure and Developer Monetization
  • Sovereign Cloud Zones as a Deployment Unlock
  • Emerging-Market Leapfrog Deployments
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Deployment Mode | |
    2. 2.2 By Organization Size | |
    3. 2.3 By Solution Type | |
    4. 2.4 By Network Type | |
    5. 2.5 By End-User | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 5G Standalone Core Deployments | |
    2. 4.2 Cloud-Native Network Function Migration | |
    3. 4.3 Data Sovereignty and Privacy Regulation | |
    4. 4.4 Massive IoT and Private Network Expansion | |
    5. 4.5 MVNO and Digital Brand Proliferation | |
    6. 4.6 AI-Driven Subscriber Analytics | |
    7. 4.7 Fixed-Mobile Convergence Programs | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Legacy HLR/HSS Migration Complexity | |
    2. 5.2 Data Residency Fragmentation Costs | |
    3. 5.3 Operator Capex Compression | |
    4. 5.4 Signalling Security Exposure | |
    5. 5.5 Cloud-Native Skills Shortage | |
  6. 6 Opportunities | |
    1. 6.1 Network API Exposure and Developer Monetization | |
    2. 6.2 Sovereign Cloud Zones as a Deployment Unlock | |
    3. 6.3 Emerging-Market Leapfrog Deployments | |
    4. 6.4 Private Network and Campus Identity Services | |
    5. 6.5 Subscriber Data as a Federated Analytics Product | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 United Arab Emirates | | |
      3. 7.5.3 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Network Operations | |
    2. 8.2 Platform Economics and API Revenue | |
    3. 8.3 Machine Identity Overtakes Human Identity | |
    4. 8.4 Energy Efficiency and Reporting Obligations | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Deployment Mode | | |
      1. 9.1.1 Cloud | | |
      2. 9.1.2 On-Premise | | |
      3. 9.1.3 Hybrid | |
    2. 9.2 By Organization Size | | |
      1. 9.2.1 Large Enterprises | | |
      2. 9.2.2 Small and Medium Enterprises | |
    3. 9.3 By Solution Type | | |
      1. 9.3.1 Subscriber Data Repository | | |
      2. 9.3.2 Policy Management | | |
      3. 9.3.3 Identity Management | | |
      4. 9.3.4 Subscriber Data Federation | |
    4. 9.4 By Network Type | | |
      1. 9.4.1 2G/3G | | |
      2. 9.4.2 4G/LTE | | |
      3. 9.4.3 5G Non-Standalone | | |
      4. 9.4.4 5G Standalone | |
    5. 9.5 By End-user | | |
      1. 9.5.1 Mobile Network Operators (MNOs) | | |
      2. 9.5.2 Mobile Virtual Network Operators | | |
      3. 9.5.3 Enterprises/IoT Service Providers | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Subscriber Data Management Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Subscriber Data Management Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Regional Market Share Summary, 2025 (%) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  26. TABLE 12 Market Size, by Organization Size, 2021–2035 (USD Billion) | |
  27. TABLE 13 Market Size, by Solution Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Market Size, by Network Type, 2021–2035 (USD Billion) | |
  29. TABLE 15 Market Size, by End-user, 2021–2035 (USD Billion) | |
  30. TABLE 16 Competitive Benchmarking Matrix, 2026 | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations Index | |
  34. TABLE 20 Segmentation Quick Reference Matrix | | LIST OF FIGURES | |
  35. FIGURE 1 Market Dynamics – Drivers, Restraints, and Opportunities | |
  36. FIGURE 2 Industry Value Chain Analysis | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  39. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 (%) | |
  40. FIGURE 6 Market Share by Deployment Mode, 2025 (%) | |
  41. FIGURE 7 Market Share by Organization Size, 2025 (%) | |
  42. FIGURE 8 Market Share by Solution Type, 2025 (%) | |
  43. FIGURE 9 Market Share by Network Type, 2025 (%) | |
  44. FIGURE 10 Market Share by End-user, 2025 (%) | |
  45. FIGURE 11 Regional Market Share Distribution, 2025 (%) | |
  46. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) | |
  47. FIGURE 13 Competitive Landscape Positioning Map, 2026 | |
  48. FIGURE 14 Top-5 Vendor Revenue Share Concentration, 2025 (%)

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Deployment ModeCloud; On-Premise; HybridCloud (51.9% share, 2025)Hybrid (16.8% CAGR)
By Organization SizeLarge Enterprises; Small and Medium EnterprisesLarge Enterprises (59.5% share, 2025)Small and Medium Enterprises (17.8% CAGR)
By Solution TypeSubscriber Data Repository; Policy Management; Identity Management; Subscriber Data FederationSubscriber Data Repository (36.9% share, 2025)Identity Management (17.1% CAGR)
By Network Type2G/3G; 4G/LTE; 5G Non-Standalone; 5G Standalone4G/LTE (41.8% share, 2025)5G Standalone (17.5% CAGR)
By End-userMobile Network Operators (MNOs); Mobile Virtual Network Operators; Enterprises/IoT Service ProvidersMobile Network Operators (53.4% share, 2025)Enterprises/IoT Service Providers (18.2% CAGR)


Market Segmentation Overview

By Deployment Mode

Sub-SegmentKey Trend
CloudConsumption licensing replaces per-node pricing as hyperscaler core partnerships mature
On-PremiseRetained for sovereign, defence, and regulated-identifier custody workloads
HybridAutomated data-placement policies shift records between edge and core on latency or compliance triggers


Cloud holds the revenue lead because operators prefer contracting terms that eliminate hardware refresh cycles and match subscriber growth to spend. Hybrid grows fastest, and the reason is jurisdictional rather than technical — European and Indian carriers store regulated identifiers domestically while running policy analytics on hyperscale infrastructure nearer user clusters. On-premise deployments do not disappear; they consolidate around customers whose licence conditions prohibit external custody entirely.

By Organization Size

Sub-SegmentKey Trend
Large EnterprisesMulti-site core modernization tied to standalone commissioning schedules
Small and Medium EnterprisesLow-code provisioning portals and pre-packaged analytics lower the skills barrier


Large enterprises command the majority of revenue because national operators undertake the most complex migrations and license the broadest feature sets. Small and medium enterprises grow fastest, since subscription pricing converts a capital decision into an operating one — decisive for regional virtual operators, utility networks, and campus 5G licensees. Vendors serving the smaller cohort compete on time-to-provision, where weeks rather than quarters determine the win.

By Solution Type

Sub-SegmentKey Trend
Subscriber Data RepositoryConsolidation of profile, location, and policy records spanning 2G through 5G eras
Policy ManagementSlice-aware quality-of-service enforcement replaces per-service policy engines
Identity ManagementZero-trust authentication and SUCI concealment drive premium security attach
Subscriber Data FederationQuery-in-place analytics satisfy purpose-limitation rules without record movement


Subscriber Data Repository leads on share because every adjacent function reads from it, giving it the widest installed base and the highest switching cost. Identity Management advances fastest as enterprises deploying private 5G use the identity layer to segregate robotics, camera, and employee traffic across slices — a security requirement whose only alternative is physically separate networks. Policy Management and Subscriber Data Federation sit between the two, growing with slicing complexity and residency constraints respectively.

By Network Type

Sub-SegmentKey Trend
2G/3GStaged sunsets managed alongside rural voice-fallback continuity
4G/LTEInstalled-base scale sustained by fixed-wireless access growth
5G Non-StandaloneTransitional deployments bridging radio upgrades ahead of core readiness
5G StandaloneSlice-to-identity mapping at microsecond latency reshapes repository design


4G/LTE retains the largest share on installed-base weight, and fixed-wireless access continues adding LTE-attached records where fibre economics fail. 5G Standalone grows fastest because it changes the underlying technical requirement rather than merely adding volume; resolving slice policy against identity inside a microsecond budget is incompatible with legacy query paths. Support for 2G/3G persists in parallel, so vendors tag records with access-type metadata to avoid duplicating policy logic across generations.

By End-user

Sub-SegmentKey Trend
Mobile Network Operators (MNOs)Core modernization tied to standalone commissioning and 2G/3G retirement
Mobile Virtual Network OperatorsMulti-tenant identity partitioning purchased from host operators
Enterprises/IoT Service ProvidersDevice-fleet credential lifecycle management delivered through systems integrators


Mobile Network Operators remain the revenue centre because they own the largest subscriber bases and the most demanding migration programs. Enterprises/IoT Service Providers grow fastest, and their buying route differs fundamentally — purchases route through industrial systems integrators rather than carrier account teams, which changes vendor cost structures and support models. Mobile Virtual Network Operators sit in between, buying partitioned capacity from hosts rather than owning platforms, which caps their spend per subscriber but makes revenue highly recurring.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.