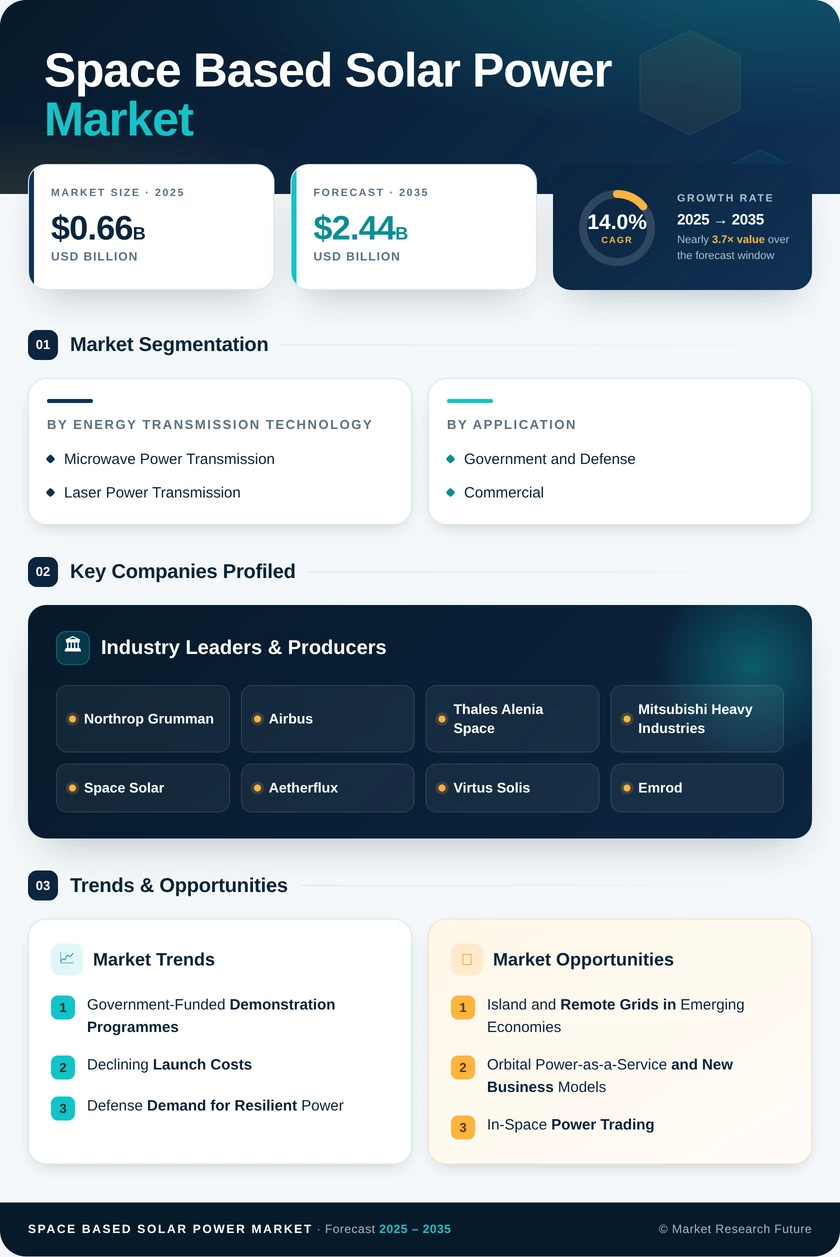
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Energy Transmission Technology | Microwave Power Transmission; Laser Power Transmission | Microwave Power Transmission (73.2% share) | Laser Power Transmission (19.4% CAGR) |
| By Application | Terrestrial; Space | Terrestrial (55.6% share) | Space (16.6% CAGR) |
| By End User | Government and Defense; Commercial | Government and Defense (62.4% share) | Commercial (17.2% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America (41.5% share) | Europe (16.3% CAGR (2026–2035)) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Microwave Power Transmission | High-efficiency metamaterial rectennas and 5G-derived amplifier supply chains |
| Laser Power Transmission | Compact receivers, optical relays and high-altitude platform hybrids |
Microwave Power Transmission leads with a 73.2% share because it penetrates cloud cover and builds on decades of validated beaming tests. Laser Power Transmission grows fastest at a 19.4% CAGR, since tightly focused optical beams cut receiver size from kilometre-scale fields to compact arrays. That size advantage suits forward bases and satellite-to-satellite links, where land and mass are scarce.
| Sub-Segment | Key Trend |
|---|
| Terrestrial | Containerised receivers for mines, bases, islands and disaster zones |
| Space | Satellite power sharing, orbital computing and lunar surface supply |
Terrestrial delivery holds a 55.6% share, since remote sites paying high diesel prices offer the fastest payback for beamed power. Space applications expand at a 16.6% CAGR because spacecraft need far lower power levels than grids, letting operators sell into orbit before gigawatt systems exist. Lunar programmes add a long-term anchor customer for space delivery.
| Sub-Segment | Key Trend |
|---|
| Government and Defense | Funded flight demonstrations and beam-safety standards |
| Commercial | Orbital offtake contracts and asset-light service models |
Government and Defense buyers hold a 62.4% share, funding demonstrators such as SSPIDR and setting the safety rules commercial operators will follow. Commercial users grow fastest at a 17.2% CAGR as utilities and data center operators test long-term offtake for firm clean supply. Venture-backed providers are lowering entry barriers by selling delivered power rather than hardware.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA