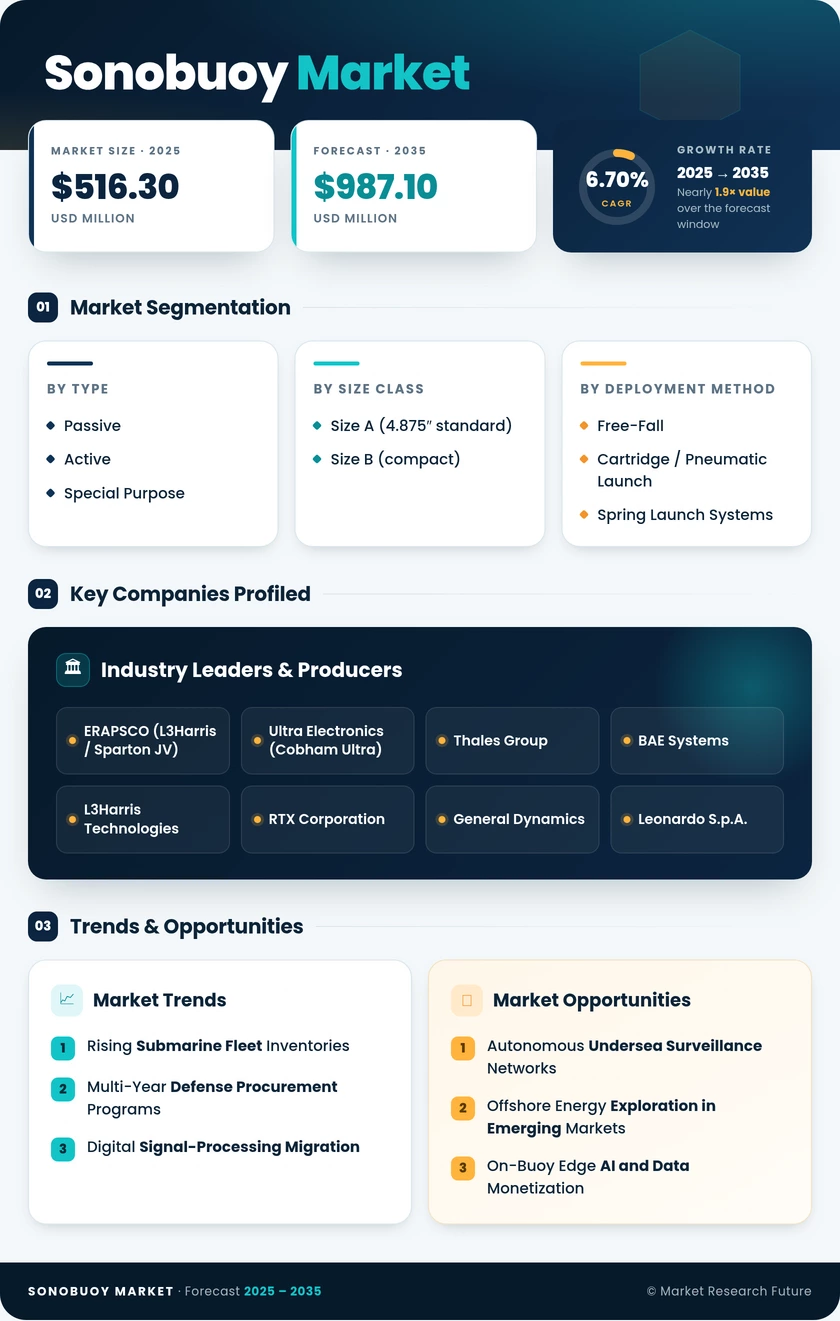
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Type | Active, Passive, Special Purpose | Passive | Active |
| Size Class | Size A, Size B | Size A | Size B |
| Deployment Method | Free-Fall, Cartridge/Pneumatic Launch, Spring Launch Systems | Free-Fall | Cartridge/Pneumatic Launch |
| Application | Commercial, Defense | Defense | Commercial |
| Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| Passive | Dominant share driven by covert wide-area surveillance requirements and low unit cost |
| Active | Rapid growth fueled by littoral localization missions and multistatic network architectures |
| Special Purpose | Steady niche demand for bathythermograph, calibration, and environmental-monitoring variants |
Passive sonobuoys remain the workhorse of fleet operations due to their ability to detect submarine acoustic signatures without emitting energy that reveals the deploying aircraft's position. Active and special-purpose variants are gaining procurement share as mission profiles diversify beyond traditional deep-water barrier operations.
By Size Class
| Sub-Segment | Key Trend |
| Size A (Standard) | Entrenched dominance based on NATO-standard launcher compatibility across allied fleets |
| Size B (Compact) | Fastest growth driven by UAS and rotary-wing deployment requirements |
The Size A form factor ensures cross-platform interoperability, but the shift toward unmanned and helicopter-based deployment is accelerating demand for compact Size B units that fit smaller launch tubes and lighter payload bays.
By Deployment Method
| Sub-Segment | Key Trend |
| Free-Fall | Leading share anchored by fixed-wing maritime patrol aircraft operations |
| Cartridge / Pneumatic Launch | Growing adoption for helicopter and UAS dispensing systems |
| Spring Launch Systems | Niche use in shipboard and submarine-launched surveillance missions |
Free-fall deployment from P-8A Poseidon and comparable platforms accounts for the majority of global consumption, while cartridge-based formats are the primary growth vector as smaller airframes enter the maritime patrol role.
By Application
| Sub-Segment | Key Trend |
| Defense | Overwhelming share sustained by anti-submarine warfare training and operations |
| Commercial | Fastest growth from offshore energy seismic surveys and marine environmental research |
Defense end users consume the vast majority of global sonobuoy production, but the commercial segment is expanding as oil-and-gas operators and marine researchers adopt expendable acoustic sensors for passive seismic monitoring and oceanographic data collection.
By Geography
| Sub-Segment | Key Trend |
| North America | Largest market driven by U.S. Navy multi-year procurement contracts |
| Europe | Resurgent demand from NATO northern-flank anti-submarine warfare priorities |
| Asia-Pacific | Fastest growth propelled by submarine fleet expansion and AUKUS programs |
| South America | Dual-use demand from naval defense and offshore energy exploration |
| Middle East & Africa | Emerging procurement linked to Gulf-state naval modernization programs |
Regional demand patterns closely mirror submarine threat environments and defense alliance structures, with North America retaining procurement leadership while Asia-Pacific posts the highest growth rate across the forecast period.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA