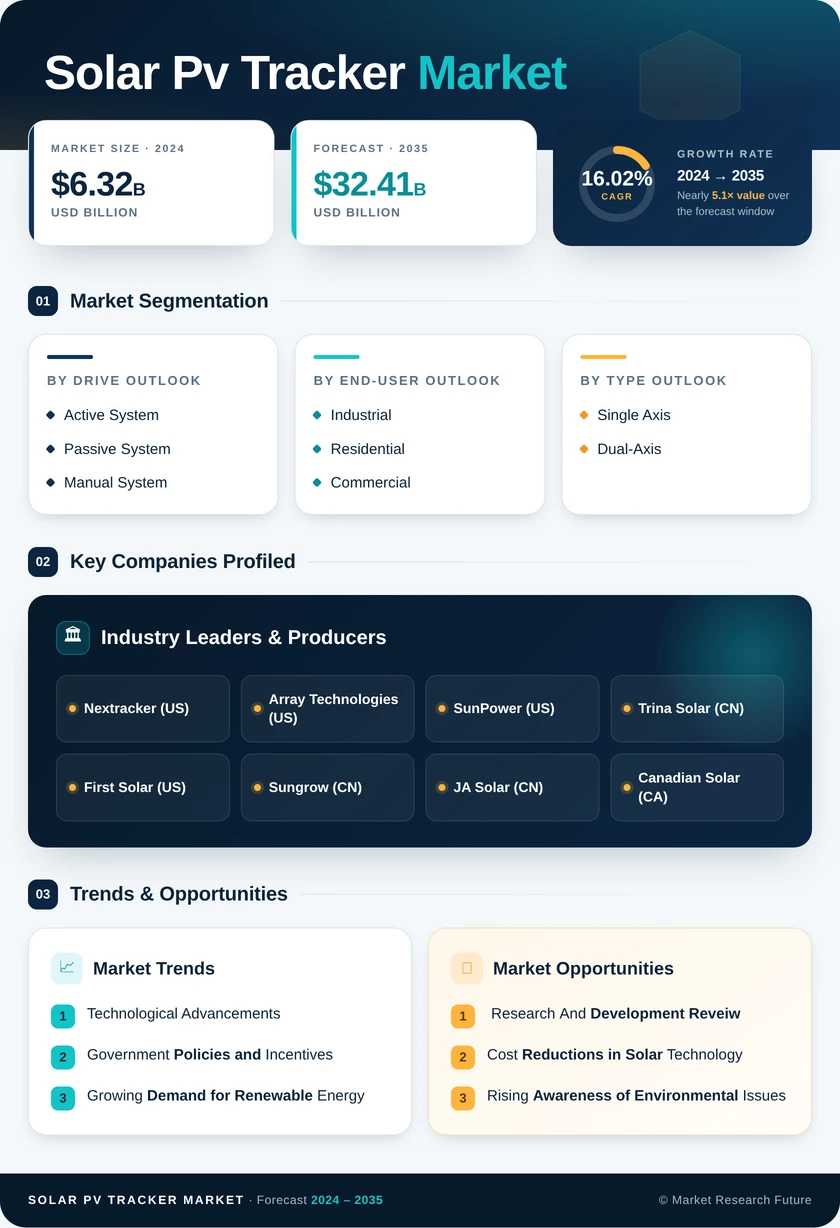
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Tracker Type | Single-Axis; Horizontal Single-Axis; Tilted / Vertical Single-Axis; Dual-Axis; Tip-Tilt Dual-Axis; Azimuth-Altitude Dual-Axis | Single-Axis | Azimuth-Altitude Dual-Axis |
| By Technology | Photovoltaic (PV); Concentrated Solar Power (CSP); Concentrated PV (CPV) | Photovoltaic (PV) | Concentrated PV (CPV) |
| By Drive Type | Electric Motor Drive; Hydraulic Drive; Manual / Passive | Electric Motor Drive | Hydraulic Drive |
| By Application | Utility-Scale; Commercial & Industrial; Residential; Agrivoltaic | Utility-Scale | Agrivoltaic |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Tracker Type
| Sub-Segment | Key Trend |
| Single-Axis | Row lengths extending past 90 modules per drive to dilute actuator cost. |
| Horizontal Single-Axis | Standardized torque tube sections enabling regional fabrication |
| Tilted / Vertical Single-Axis | Adoption rising above 45 degrees latitude and on constrained parcels. |
| Dual-Axis | Confined to concentrating and precision-pointing applications |
| Tip-Tilt Dual-Axis | Used where module count is small but irradiance capture is critical. |
| Azimuth-Altitude Dual-Axis | Fastest architecture growth, tied to concentrator optics programmes |
Tracker architecture selection is now driven less by peak energy capture than by installed cost per delivered megawatt-hour. Single-axis systems win that calculation almost everywhere flat land is available, while dual-axis retains value only where optical concentration demands precise pointing.
By Technology
| Sub-Segment | Key Trend |
| Photovoltaic (PV) | Bifacial penetration reshaping row geometry and ground cover ratio |
| Concentrated Solar Power (CSP) | Persisting in Gulf and Chinese hybrids with molten salt storage |
| Concentrated PV (CPV) | Small base expanding on multi-junction cell cost improvement |
Photovoltaic demand governs the entire hardware roadmap, and supplier R&D budgets follow accordingly. Thermal and concentrating technologies survive in dispatchability-driven procurement, where storage value rather than energy cost decides the award.
By Drive Type
| Sub-Segment | Key Trend |
| Electric Motor Drive | Integration with SCADA and adaptive control firmware |
| Hydraulic Drive | Rapid storm-stow capability winning cyclone-exposed markets |
| Manual / Passive | Limited to small distributed and off-grid installations |
Drive selection increasingly reflects climate risk rather than cost. Insurers and lenders now examine stow speed and failure modes closely, which has lifted hydraulic architectures out of their former niche in typhoon and cyclone corridors.
By Application
| Sub-Segment | Key Trend |
| Utility-Scale | Yield per interconnection megawatt becoming the governing metric. |
| Commercial & Industrial | Corporate PPA and self-consumption demand supporting healthier margins |
| Residential | Premium rural ground-mount niche with limited absolute volume |
| Agrivoltaic | Policy-mandated elevation and row spacing creating price premiums |
Application mix determines margin far more than volume. Utility-scale sets the price floor through competitive tendering, while agrivoltaic and commercial installations reward engineering customization that standardized utility products cannot deliver.
By Region
| Sub-Segment | Key Trend |
| North America | Domestic content certification restructuring supplier selection |
| Europe | Dual land-use policy and permitting reform releasing constrained pipeline |
| Asia-Pacific | Local content rules and cost leadership driving volume growth |
| South America | Distributed generation reform and mining electrification demand |
| Middle East & Africa | Sovereign gigawatt tenders with rising local assembly requirements |
Regional demand no longer moves in unison. Policy design, not irradiance, now explains most of the variance in growth rates, and suppliers that align manufacturing footprints with content rules will hold the strongest positions through 2035.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA