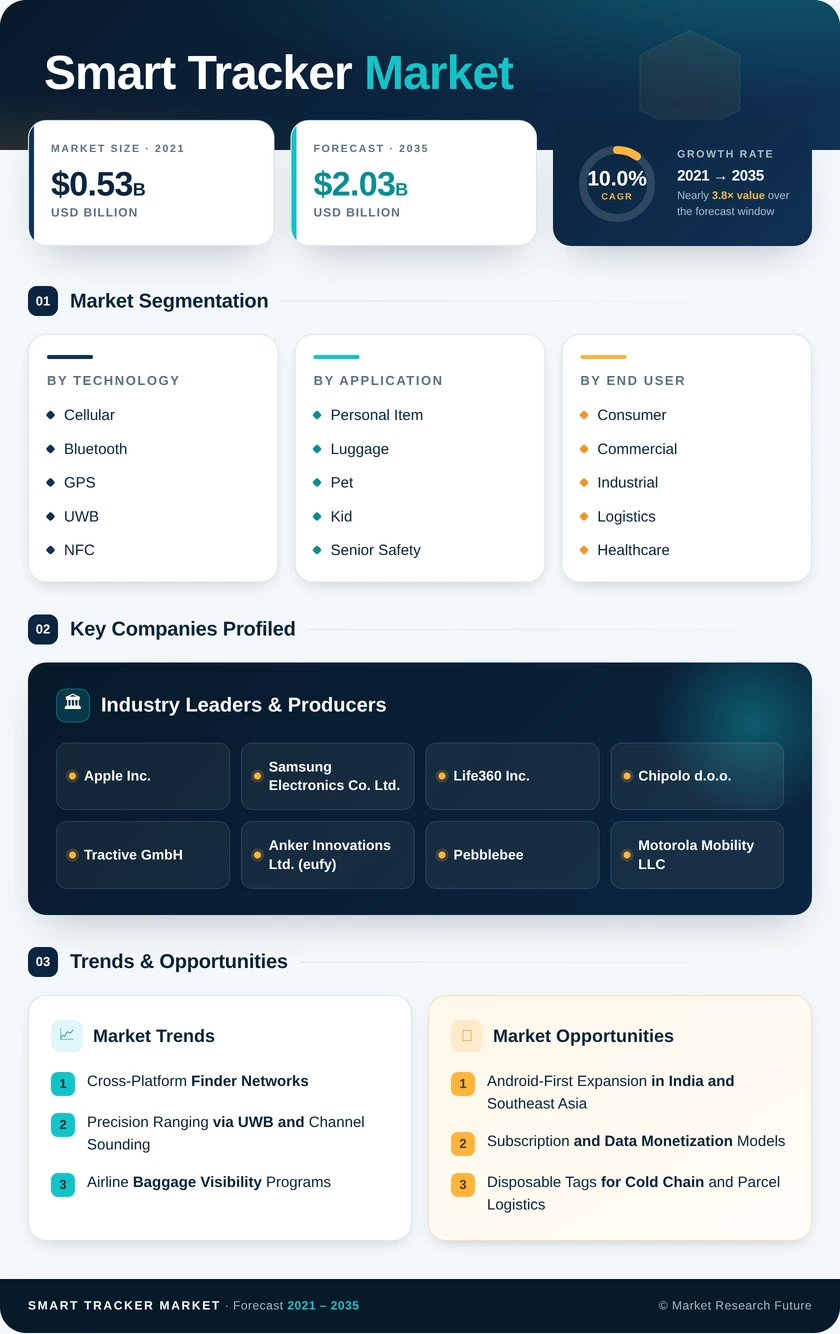
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Technology | Cellular, Bluetooth, GPS, UWB, NFC | Bluetooth (56.8% share) | UWB (10.3% CAGR) |
| By Application | Personal Item, Luggage, Pet, Kid and Senior Safety, Enterprise Inventory, Vehicle | Personal Item (53.6% share) | Kid and Senior Safety (10.9% CAGR) |
| By End User | Consumer, Commercial, Industrial and Logistics, Healthcare, Government | Consumer (54.3% share) | Healthcare (12.1% CAGR) |
| By Form Factor | Key Fob, Card, Wearable Clip, Plug-In, Disposable Tag | Key Fob (45.6% share) | Wearable Clip (11.2% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America (38.5% share) | Asia-Pacific (12.4% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Cellular | LTE-M and NB-IoT replace sunset 2G/3G modules |
| Bluetooth | Finder-network relays and Channel Sounding upgrades |
| GPS | Outdoor accuracy for pets and vehicles |
| UWB | Centimeter-level ranging for enterprise and premium tags |
| NFC | Tap-to-read owner details in lost mode |
Bluetooth leads because any nearby smartphone can relay its location at no cost to the owner, which keeps entry-level tags cheap. UWB grows fastest as hospitals and warehouses pay for sub-30 cm accuracy that Bluetooth proximity cannot match. Cellular and GPS hold their ground in outdoor use, where phone relays are sparse.
| Sub-Segment | Key Trend |
|---|
| Personal Item | Price compression pushes brands toward subscriptions |
| Luggage | Airline location-sharing integrations |
| Pet | Insurer-backed GPS collars |
| Kid and Senior Safety | Cellular wearables with voice and fall alerts |
| Enterprise Inventory | Ruggedized tags linked to asset software |
| Vehicle | Theft recovery in high-crime markets |
Personal Item tracking leads on volume, yet its share is gradually eroding as basic tags commoditize. Kid and Senior Safety grows fastest because caregivers pay for cellular connectivity, two-way calling and geofence alerts that basic tags lack. Luggage gains a structural boost from airline programs that now accept passenger tag data.
| Sub-Segment | Key Trend |
|---|
| Consumer | Shift from one-time hardware to memberships |
| Commercial | Tags embedded in high-shrink merchandise |
| Industrial and Logistics | Pallet dwell-time and theft monitoring |
| Healthcare | Anchor networks for mobile medical equipment |
| Government | Tamper-evident trackers for sensitive assets |
Consumers remain the largest buyer group, but falling hardware margins are steering brands toward paid memberships. Healthcare grows fastest because hospitals can quantify savings from fewer equipment rentals and shorter search times once anchor networks are in place. Industrial and Logistics buyers add scale as disposable and long-life tags cut per-shipment costs.
| Sub-Segment | Key Trend |
|---|
| Key Fob | Commoditized design competing on battery life |
| Card | Slim wallet trackers with rechargeable cells |
| Wearable Clip | Collar and wristband mounts with activity sensors |
| Plug-In | OBD-II vehicle units using onboard power |
| Disposable Tag | Single-use parcel and cold-chain labels |
Key Fob designs lead because one product fits keys, bags and luggage, though differentiation now rests mainly on battery life and speaker volume. Wearable Clip formats grow fastest as pet owners and caregivers favor devices that sit securely on collars or wrists and support health-monitoring subscriptions. Disposable Tag formats are the logistics growth story as unit costs fall.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA