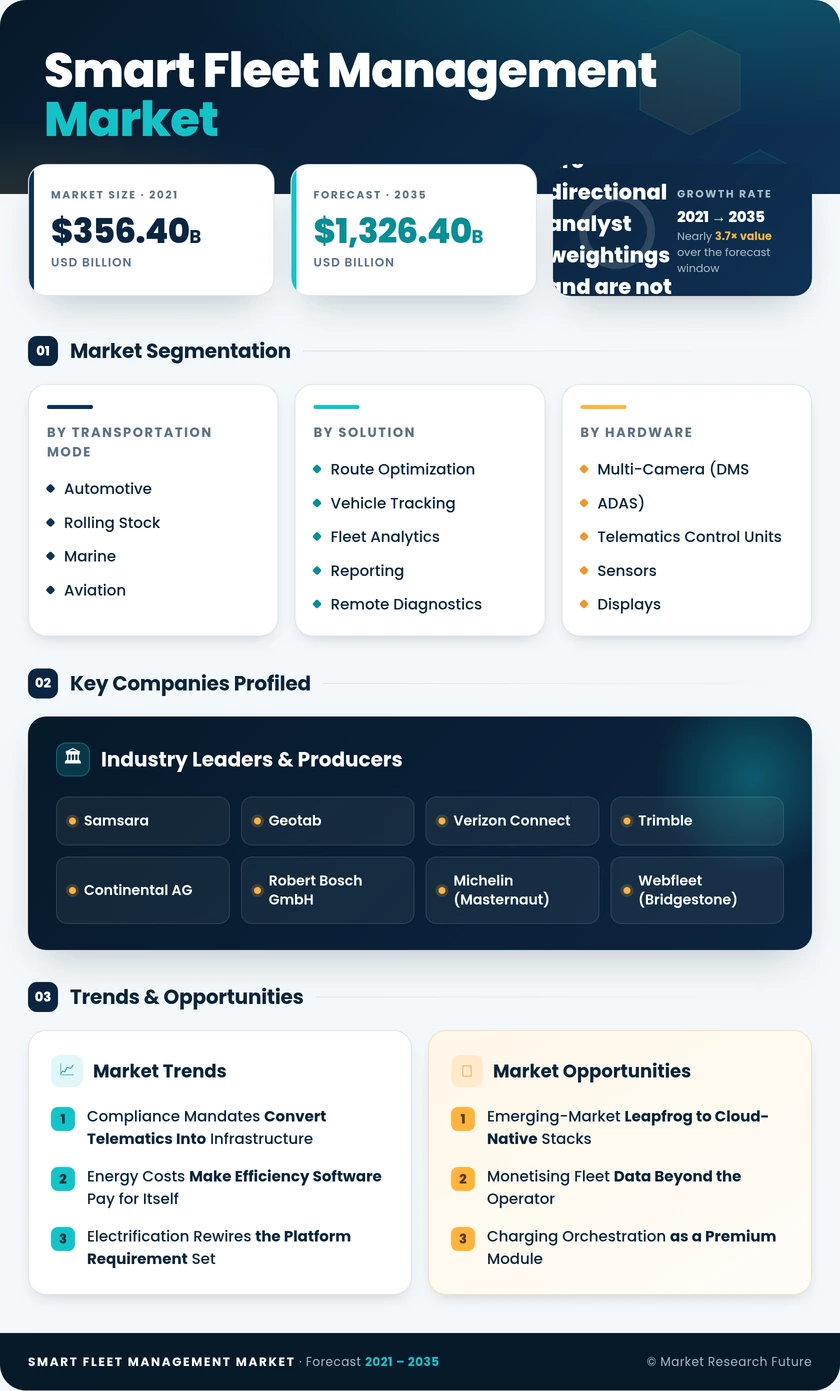
Smart Fleet Management Market (2026 - 2035)

ID: MRFR/AT/3788-CR 111 Pages Triveni Bhoyar Last Updated: October 16, 2026
Smart Fleet Management Market Research Report By Transportation Mode (Automotive, Rolling Stock, Marine, Aviation), By Solution (Route Optimization, Vehicle Tracking, Fleet Analytics and Reporting, Remote Diagnostics, Driver Behaviour Monitoring, Tracking and Monitoring, Advanced Driver-Assistance Systems (ADAS), Telematics Data Analytics (AI/ML), Video-Telematics and Driver Safety), By Hardware (Multi-Camera (DMS, ADAS), Telematics Control Units, Sensors, Displays and HMI, On-board Diagnostics (OBD) Dongles, GNSS/Dual-band GPS Devices), By Connectivity (Short-Range (Bluetooth/Wi-Fi), Long-Range (Cellular), Satellite), By Fleet Size (1–49 Vehicles (Small), 50–499 Vehicles (Medium), 500+ Vehicles (Large)), By End-User Vertical (Logistics and Last-Mile Delivery, Public Transport, Construction and Mining, Oil and Gas, Retail and FMCG, Government and Municipal) - Forecast to 2035
Smart Fleet Management Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)10.05%
2025 Market SizeUSD 541.20 Billion
2035 Market SizeUSD 1,326.40 billion
Key Players
Samsara
Geotab
Verizon Connect
Trimble
Continental AG
Robert Bosch GmbH
Opportunities
  • Emerging-Market Leapfrog to Cloud-Native Stacks
  • Monetising Fleet Data Beyond the Operator
  • Charging Orchestration as a Premium Module
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Region | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Compliance Mandates Convert Telematics Into Infrastructure | |
    2. 4.2 Energy Costs Make Efficiency Software Pay for Itself | |
    3. 4.3 Electrification Rewires the Platform Requirement Set | |
    4. 4.4 Insurers Are Underwriting on Telematics Output | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Privacy Law Constrains What Platforms May Collect | |
    2. 5.2 Legacy Systems Resist the Handshake | |
    3. 5.3 Small Fleets Cannot Fund the Upfront Hardware | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Leapfrog to Cloud-Native Stacks | |
    2. 6.2 Monetising Fleet Data Beyond the Operator | |
    3. 6.3 Charging Orchestration as a Premium Module | |
    4. 6.4 Insurance-Embedded Distribution | |
    5. 6.5 Cold-Chain and Regulated-Cargo Telemetry | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomy Moves From Highway to Yard | |
    2. 8.2 Platform Economics Shift Toward Consolidation | |
    3. 8.3 The Electrification Supercycle Reshapes Requirements | |
    4. 8.4 Emissions Reporting Becomes a Contractual Requirement | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Transportation Mode | | |
      1. 9.1.1 Automotive | | |
      2. 9.1.2 Rolling Stock | | |
      3. 9.1.3 Marine | | |
      4. 9.1.4 Aviation | |
    2. 9.2 By Solution | | |
      1. 9.2.1 Route Optimization | | |
      2. 9.2.2 Vehicle Tracking | | |
      3. 9.2.3 Fleet Analytics and Reporting | | |
      4. 9.2.4 Remote Diagnostics | | |
      5. 9.2.5 Driver Behaviour Monitoring | | |
      6. 9.2.6 Tracking and Monitoring | | |
      7. 9.2.7 Advanced Driver-Assistance Systems (ADAS) | | |
      8. 9.2.8 Telematics Data Analytics (AI/ML) | | |
      9. 9.2.9 Video-Telematics and Driver Safety | |
    3. 9.3 By Hardware | | |
      1. 9.3.1 Multi-Camera (DMS, ADAS) | | |
      2. 9.3.2 Telematics Control Units | | |
      3. 9.3.3 Sensors | | |
      4. 9.3.4 Displays and HMI | | |
      5. 9.3.5 On-board Diagnostics (OBD) Dongles | | |
      6. 9.3.6 GNSS/Dual-band GPS Devices | |
    4. 9.4 By Connectivity | | |
      1. 9.4.1 Short-Range (Bluetooth/Wi-Fi) | | |
      2. 9.4.2 Long-Range (Cellular) | | |
      3. 9.4.3 Satellite | |
    5. 9.5 By Fleet Size | | |
      1. 9.5.1 1–49 Vehicles (Small) | | |
      2. 9.5.2 50–499 Vehicles (Medium) | | |
      3. 9.5.3 500+ Vehicles (Large) | |
    6. 9.6 By End-User Vertical | | |
      1. 9.6.1 Logistics and Last-Mile Delivery | | |
      2. 9.6.2 Public Transport | | |
      3. 9.6.3 Construction and Mining | | |
      4. 9.6.4 Oil and Gas | | |
      5. 9.6.5 Retail and FMCG | | |
      6. 9.6.6 Government and Municipal | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Samsara | | |
      2. 10.3.2 Geotab | | |
      3. 10.3.3 Verizon Connect | | |
      4. 10.3.4 Trimble | | |
      5. 10.3.5 Continental AG | | |
      6. 10.3.6 Robert Bosch GmbH | | |
      7. 10.3.7 Michelin (Masternaut) | | |
      8. 10.3.8 Webfleet (Bridgestone) | | |
      9. 10.3.9 Omnitracs / Solera | | |
      10. 10.3.10 Teletrac Navman | | |
      11. 10.3.11 Cartrack (Karooooo) | | |
      12. 10.3.12 ORBCOMM | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Assumptions | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | | LIST OF FIGURES

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Transportation ModeAutomotive; Rolling Stock; Marine; AviationAutomotiveMarine
By SolutionRoute Optimization; Vehicle Tracking; Fleet Analytics and Reporting; Remote Diagnostics; Driver Behaviour MonitoringRoute OptimizationFleet Analytics and Reporting
By HardwareMulti-Camera (DMS, ADAS); Telematics Control Units; Sensors; Displays and HMITelematics Control UnitsMulti-Camera (DMS, ADAS)
By ConnectivityShort-Range (Bluetooth/Wi-Fi); Long-Range (Cellular); SatelliteLong-Range (Cellular)Satellite
By Fleet Size1–49 Vehicles (Small); 50–499 Vehicles (Medium); 500+ Vehicles (Large)50–499 Vehicles (Medium)1–49 Vehicles (Small)
By End-User VerticalLogistics and Last-Mile Delivery; Public Transport; Construction and Mining; Oil and Gas; Retail and FMCG; Government and MunicipalLogistics and Last-Mile DeliveryPublic Transport
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Transportation Mode

Sub-SegmentKey Trend
AutomotiveVideo-enabled safety systems become standard specification on new commercial orders
Rolling StockWagon-level tracking spreads as rail freight competes on visibility parity with road
MarinePort call optimisation and berth scheduling drive instrumentation of terminal assets
AviationGround support equipment tracking reduces turnaround delays at congested hubs


By Solution

Sub-SegmentKey Trend
Route OptimizationDynamic re-sequencing replaces static daily route planning
Vehicle TrackingCustomer-facing ETA sharing becomes a shipper contract requirement
Fleet Analytics and ReportingEmissions and compliance dashboards move from optional to mandated
Remote DiagnosticsFault-code prediction shifts maintenance from calendar to condition-based
Driver Behaviour MonitoringCoaching workflows replace punitive scoring to protect retention


Solution buying has matured from tracking toward decision support. Operators no longer ask where the vehicle is; they ask what should happen next, and that question is what sustains subscription pricing power.

By Hardware

Sub-SegmentKey Trend
Multi-Camera (DMS, ADAS)Edge inference reduces bandwidth cost of continuous video telematics
Telematics Control UnitsFactory-fitted units erode aftermarket dongle volumes in developed markets
SensorsTemperature, weight and tyre pressure sensing expands beyond cold chain
Displays and HMIIn-cab interfaces consolidate multiple vendor apps into a single workflow


Camera hardware is the growth engine, driven by liability exposure and coaching value. Factory-fitted control units, meanwhile, quietly compress aftermarket hardware margins across Europe and North America.

By Connectivity

Sub-SegmentKey Trend
Short-Range (Bluetooth/Wi-Fi)Depot Wi-Fi offload cuts cellular costs for video-heavy fleets
Long-Range (Cellular)4G LTE-M and NB-IoT replace legacy 2G/3G as networks sunset
SatelliteDirect-to-device services extend coverage into previously dark corridors


Cellular remains the backbone, though network sunsets forced an involuntary hardware refresh across several markets. Satellite economics improved enough by 2025 that hybrid units are viable for mid-tier fleets, not just remote resource operators.

By Fleet Size

Sub-SegmentKey Trend
1–49 Vehicles (Small)Insurance-bundled and self-install offerings unlock the long tail
50–499 Vehicles (Medium)Multi-module platform consolidation replaces point tools
500+ Vehicles (Large)Custom API integration and private data lakes define requirements


Medium fleets are the commercial sweet spot: large enough to justify a platform, small enough to buy without an enterprise procurement cycle. Small fleets grow fastest because distribution finally reached them through insurers and self-installation.

By End-User Vertical

Sub-SegmentKey Trend
Logistics and Last-Mile DeliveryStop-density optimisation compounds with parcel volume growth
Public TransportElectrification programs bundle depot and charging management
Construction and MiningUtilisation tracking and proximity safety systems converge
Oil and GasLone-worker safety and remote-asset monitoring drive satellite attach
Retail and FMCGCold-chain audit trails become supplier qualification criteria
Government and MunicipalPublic asset accountability and fuel fraud prevention lead procurement


Vertical requirements diverge more than vendors like to admit. A mining haulage deployment shares almost no functional overlap with a parcel delivery rollout beyond the connectivity layer, which is why vertical-specialised competitors continue to hold share against horizontal platforms.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.