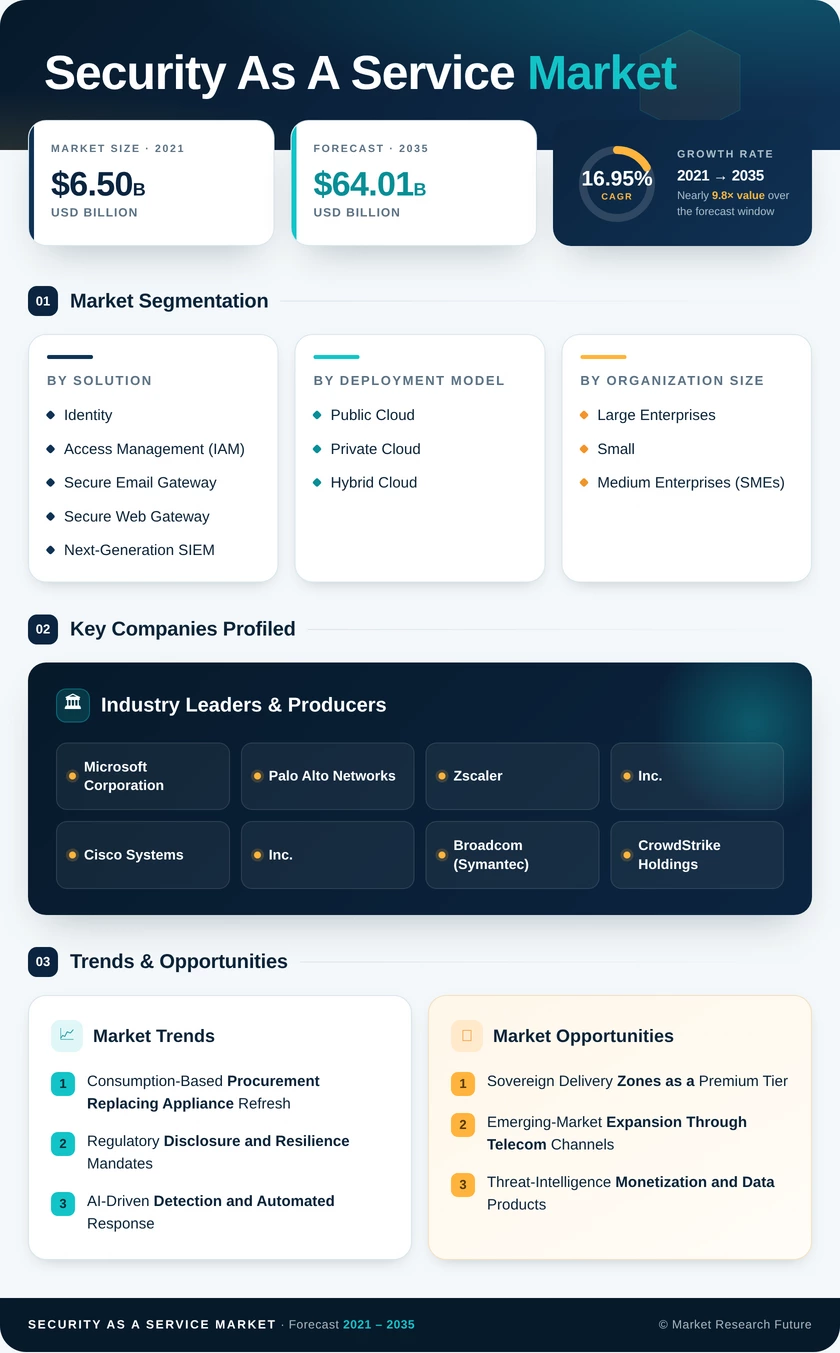
Security as a Service Market (2026 - 2035)

ID: MRFR/ICT/5246-HCR 100 Pages Ankit Gupta Last Updated: September 15, 2026
Security as a Service Market Size, Share and Research Report: By Component (Solution and Service), By Application Area (Network Security, Email-security, Database Cloud Security, Web Security, and Others), By Organization Size (SMEs and Large Enterprises), By Vertical (BFSI, Oil & Gas, IT & Telecom, Retail, Government, and Defence) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) โ€“Market Forecast Till 2035.
Security as a Service Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.95%
2025 Market SizeUSD 13.37 Billion
2035 Market SizeUSD 64.01 Billion
Key Players
Microsoft Corporation
Palo Alto Networks
Zscaler, Inc.
Cisco Systems, Inc.
Broadcom
CrowdStrike Holdings
Opportunities
  • Sovereign Delivery Zones as a Premium Tier
  • Emerging-Market Expansion Through Telecom Channels
  • Threat-Intelligence Monetization and Data Products
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Solution | |
    2. 2.2 By Deployment Model | |
    3. 2.3 By Organization Size | |
    4. 2.4 By End-User Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021โ€“2035) | |
    1. 3.1 Historical Market Size (2021โ€“2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026โ€“2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Consumption-Based Procurement Replacing Appliance Refresh | |
    2. 4.2 Regulatory Disclosure and Resilience Mandates | |
    3. 4.3 AI-Driven Detection and Automated Response | |
    4. 4.4 Distributed Workforce and Edge Site Proliferation | |
    5. 4.5 Public-Cloud Workload Migration | |
    6. 4.6 Insurance-Linked SME Adoption | |
    7. 4.7 Security Operations Talent Shortage | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Data-Residency and Sovereignty Constraints | |
    2. 5.2 Integration Debt with Legacy On-Premise Stacks | |
    3. 5.3 Decryption Latency and Inspection Overhead | |
    4. 5.4 Budget Compression in Price-Sensitive Segments | |
    5. 5.5 Vendor Concentration and Lock-In Exposure | |
  6. 6 Opportunities | |
    1. 6.1 Sovereign Delivery Zones as a Premium Tier | |
    2. 6.2 Emerging-Market Expansion Through Telecom Channels | |
    3. 6.3 Threat-Intelligence Monetization and Data Products | |
    4. 6.4 Post-Quantum Cryptographic Migration Services | |
    5. 6.5 Operational Technology and Industrial Coverage | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 United Kingdom | | |
      2. 7.2.2 Germany | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Australia | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 United Arab Emirates | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026โ€“2035) | |
    1. 8.1 Autonomous Detection and Response Operations | |
    2. 8.2 Platform Economics and Contract Consolidation | |
    3. 8.3 Sovereign and Regionalized Delivery Architecture | |
    4. 8.4 Cryptographic Transition and Long-Horizon Risk | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Solution | | |
      1. 9.1.1 Identity and Access Management (IAM) | | |
      2. 9.1.2 Secure Email Gateway | | |
      3. 9.1.3 Secure Web Gateway | | |
      4. 9.1.4 Next-Generation SIEM | | |
      5. 9.1.5 Cloud Access Security Broker | | |
      6. 9.1.6 Data Loss Prevention | | |
      7. 9.1.7 Vulnerability Management | | |
      8. 9.1.8 Other Solutions | |
    2. 9.2 By Deployment Model | | |
      1. 9.2.1 Public Cloud | | |
      2. 9.2.2 Private Cloud | | |
      3. 9.2.3 Hybrid Cloud | |
    3. 9.3 By Organization Size | | |
      1. 9.3.1 Large Enterprises | | |
      2. 9.3.2 Small and Medium Enterprises (SMEs) | |
    4. 9.4 By End-User Industry | | |
      1. 9.4.1 BFSI | | |
      2. 9.4.2 IT and Telecom | | |
      3. 9.4.3 Healthcare and Life Sciences | | |
      4. 9.4.4 Retail and E-commerce | | |
      5. 9.4.5 Government and Defence | | |
      6. 9.4.6 Manufacturing | | |
      7. 9.4.7 Other End-User Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2025) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Security As A Service Market Size & Forecast, by Revenue (USD Billion), 2021โ€“2035 | |
  16. TABLE 2 Security As A Service Market โ€” Year-over-Year Growth Analysis, 2021โ€“2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026โ€“2035 | |
  18. TABLE 4 Restraints Impact Analysis Matrix, 2026โ€“2035 | |
  19. TABLE 5 Market Size, by Region (USD Billion), 2021โ€“2035 | |
  20. TABLE 6 North America Market Size, by Country (USD Billion), 2021โ€“2035 | |
  21. TABLE 7 Europe Market Size, by Country (USD Billion), 2021โ€“2035 | |
  22. TABLE 8 Asia-Pacific Market Size, by Country (USD Billion), 2021โ€“2035 | |
  23. TABLE 9 South America Market Size, by Country (USD Billion), 2021โ€“2035 | |
  24. TABLE 10 Middle East & Africa Market Size, by Country (USD Billion), 2021โ€“2035 | |
  25. TABLE 11 Market Size, by Solution (USD Billion), 2021โ€“2035 | |
  26. TABLE 12 Market Size, by Deployment Model (USD Billion), 2021โ€“2035 | |
  27. TABLE 13 Market Size, by Organization Size (USD Billion), 2021โ€“2035 | |
  28. TABLE 14 Market Size, by End-User Industry (USD Billion), 2021โ€“2035 | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2025 | |
  30. TABLE 16 Company Profiles โ€” Key Players | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023โ€“2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations Index | |
  34. TABLE 20 Segmentation Quick Reference โ€” Dominant and Fastest-Growing Segments | | LIST OF FIGURES | |
  35. FIGURE 1 Market Dynamics โ€” Drivers, Restraints and Opportunities Overview | |
  36. FIGURE 2 Industry Value Chain Analysis | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Market Size Trend and Forecast (USD Billion), 2021โ€“2035 | |
  39. FIGURE 5 Year-over-Year Growth Curve, 2022โ€“2035 | |
  40. FIGURE 6 Revenue Share by Solution, 2025 | |
  41. FIGURE 7 Revenue Share by Deployment Model, 2025 | |
  42. FIGURE 8 Revenue Share by Organization Size, 2025 | |
  43. FIGURE 9 Revenue Share by End-User Industry, 2025 | |
  44. FIGURE 10 Regional Revenue Share Distribution, 2025 | |
  45. FIGURE 11 Regional Growth Rate Comparison, 2026โ€“2035 | |
  46. FIGURE 12 North America Country-Level Share Breakdown, 2025 | |
  47. FIGURE 13 Asia-Pacific Country-Level Share Breakdown, 2025 | |
  48. FIGURE 14 Competitive Landscape โ€” Estimated Revenue Share Bands, 2025 | |
  49. FIGURE 15 Vendor Positioning Matrix โ€” Capability Breadth vs Delivery Footprint

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By SolutionIdentity and Access Management (IAM); Secure Email Gateway; Secure Web Gateway; Next-Generation SIEM; Cloud Access Security Broker; Data Loss Prevention; Vulnerability Management; Other SolutionsIdentity and Access Management (IAM) โ€” 22.86% revenue share (2025)Cloud Access Security Broker โ€” 17.55% CAGR (2026โ€“2035)
By Deployment ModelPublic Cloud; Private Cloud; Hybrid CloudPublic Cloud โ€” 55.57% revenue share (2025)Hybrid Cloud โ€” 18.35% CAGR (2026โ€“2035)
By Organization SizeLarge Enterprises; Small and Medium Enterprises (SMEs)Large Enterprises โ€” 63.12% revenue share (2025)Small and Medium Enterprises (SMEs) โ€” 18.67% CAGR (2026โ€“2035)
By End-User IndustryBFSI; IT and Telecom; Healthcare and Life Sciences; Retail and E-commerce; Government and Defence; Manufacturing; Other End-User IndustriesIT and Telecom โ€” 21.70% revenue share (2025)BFSI โ€” 17.44% CAGR (2026โ€“2035)

ย 

Market Segmentation Overview

By Solution

Sub-SegmentKey Trend
Identity and Access Management (IAM)Governance extending from workforce sign-on to machine and service identities
Secure Email GatewayMigration of standalone gateways into converged edge inspection stacks
Secure Web GatewayLocal inspection at branch and remote sites replacing centralized backhaul
Next-Generation SIEMObject-storage ingestion architectures resetting per-terabyte retention economics
Cloud Access Security BrokerDiscovery and control of application-to-application data movement
Data Loss PreventionClassification extended to generative-AI prompts and model outputs
Vulnerability ManagementScanning embedded in build pipelines with runtime exploitability correlation
Other SolutionsEncryption services and continuous compliance evidence generation

ย 

Identity and Access Management (IAM) holds the lead because container orchestrators and automated pipelines now issue more credentials than HR systems do, expanding licensed identity counts faster than headcount grows. Cloud Access Security Broker advances quickest as buyers discover that SaaS-to-SaaS integrations move regulated data without ever traversing an inspected network path. Secure Web Gateway and Secure Email Gateway remain substantial revenue lines, though both increasingly ship as modules inside converged platforms rather than as standalone purchases.

By Deployment Model

Sub-SegmentKey Trend
Public CloudGlobal points of presence delivering elastic inspection without customer infrastructure
Private CloudDedicated instances preserving metadata isolation for defence and critical infrastructure
Hybrid CloudSplit control and data planes reconciling residency rules with latency targets

ย 

Public Cloud remains the majority deployment because most buyers prioritize immediate geographic reach and zero infrastructure ownership. Hybrid Cloud grows fastest as regulated organizations place identity brokers and policy engines in shared infrastructure while keeping inline decryption on customer-managed nodes for sensitive traffic โ€” an arrangement that satisfies supervisors without abandoning performance targets. Private Cloud sustains steady demand among operators contractually barred from exposing traffic metadata to multi-tenant environments, particularly in defence and national infrastructure.

By Organization Size

Sub-SegmentKey Trend
Large EnterprisesContract consolidation and automation offsetting tier-1 analyst scarcity
Small and Medium Enterprises (SMEs)Zero-touch onboarding and insurer-recognized control bundles

ย 

Large Enterprises account for the majority of spending through multi-year programmes, established operations centres, and cross-border estates that require inspection points in several jurisdictions simultaneously. Their buying behaviour now favours fewer vendors with broader scope. Small and Medium Enterprises expand fastest because usage-based pricing and exportable compliance reports removed the expertise threshold that previously excluded them, while insurance carriers bundling monitoring into premiums turn the subscription into a cost-neutral or cost-positive decision for many firms.

By End-User Industry

Sub-SegmentKey Trend
BFSIContinuous compliance evidence replacing periodic audit attestation
IT and TelecomMulti-tenant estate complexity driving broad control coverage
Healthcare and Life SciencesConnected medical devices widening the monitored attack surface
Retail and E-commercePayment-card requirements combined with seasonal traffic elasticity
Government and DefenceSovereign delivery and in-country key management requirements
ManufacturingConvergence of plant networks with corporate IT under supply-chain assurance rules
Other End-User IndustriesEducation, energy and logistics modernization programmes

ย 

IT and Telecom generates the largest share because these operators adopted cloud-native architecture earliest and run the most heterogeneous estates, requiring nearly the full control catalogue. BFSI grows fastest as operational-resilience regimes shift supervisors from annual attestation toward near-real-time evidence, forcing banks and insurers to buy continuous monitoring rather than periodic assessment. Healthcare and Life Sciences demand tracks connected-device deployment more than patient-record volume, while Manufacturing accelerates as plant-floor networks converge with corporate infrastructure.


ย 

ย 

ย 

ย 

ย 

ย 

ย 

ย 

ย 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.