Security Analytics Market (2026 - 2035)

Security Analytics Market Size, Share and Trends Analysis Report By Application (Web Security, Network Security, Endpoint Security, Application Security), By Service (Professional, Managed), and By Region (Asia-Pacific, Europe, North America, and Rest Of The World) โ€“Market Forecast Till 2035.
ID: MRFR/ICT/2867-HCR
100 Pages
Ankit Gupta
Last Updated: August 24, 2026
Security Analytics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)18.34%
2025 Market SizeUSD 21.02 Billion
2035 Market SizeUSD 113.15 Billion
Key Players
IBM
Splunk
Palo Alto Networks
Fortinet
Broadcom
Rapid7
Opportunities
  • AI-Native SOC Automation Platforms
  • SME-Focused Managed Analytics Services
  • Emerging Market Digital Infrastructure Buildout

Security Analytics Market Summary

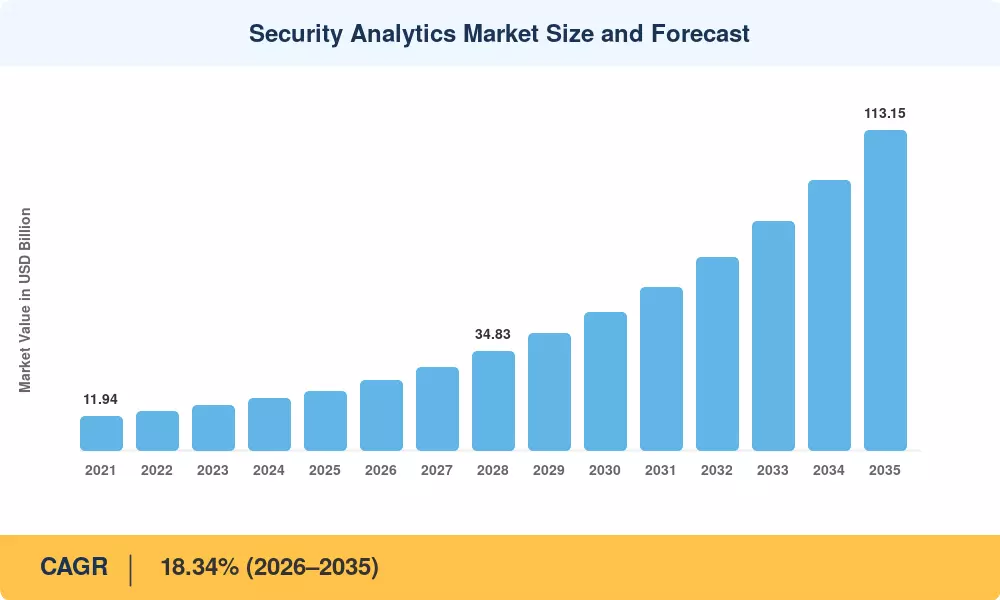
The Security Analytics Market reached an estimated USD 21.02 billion in 2025 and is projected to enter the forecast window at USD 24.87 billion in 2026, climbing to USD 113.15 billion by 2035 at a CAGR of 18.34%. This trajectory reflects a surge in cybersecurity spending driven by escalating ransomware costs โ€” the FBI's Internet Crime Complaint Center recorded over USD 12.5 billion in reported losses during 2023 alone [1] โ€” and tightening regulatory mandates such as the EU's NIS2 Directive and the SEC's cybersecurity disclosure rules enacted in December 2023 [2]. Enterprises are no longer treating security analytics as optional; boards now classify it alongside financial audit and compliance infrastructure.

A fundamental technology shift is reshaping the Security Analytics Market. Legacy perimeter-based security tools and siloed log management platforms are giving way to AI-driven, cloud-native analytics platforms that correlate telemetry across endpoints, networks, identities, and applications in real time. estimated that global cybersecurity spending exceeded USD 215 billion in 2024 [3], with analytics and intelligence platforms capturing an increasing share of that budget as organizations move from reactive to predictive security postures.

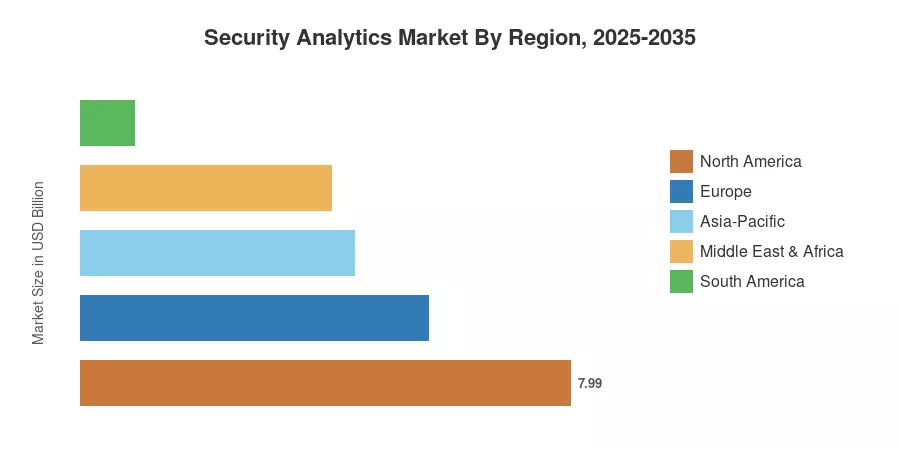
North America commands roughly 38% of the Security Analytics Market, underpinned by mature enterprise IT ecosystems and aggressive federal cybersecurity mandates like CISA's Binding Operational Directives [4]. Asia-Pacific stands as the fastest-growing region at an estimated CAGR exceeding 21%, fueled by rapid digitalization across India, China, and Southeast Asia. Europe holds the second-largest share at approximately 27%, propelled by GDPR enforcement actions and the Digital Operational Resilience Act (DORA) for financial services [5]. The decade ahead will be defined by convergence โ€” security analytics merging with IT operations, identity governance, and automated response into unified platforms.

ย 

Key Report Takeaways

โ€ข By Application

  • Network Security Analytics accounts for the largest share of the Security Analytics Market at approximately 42% of 2025 revenue, driven by the proliferation of east-west traffic monitoring inside hybrid cloud environments.
  • Application Security Analytics is expanding at the fastest pace within the segment, with a projected CAGR of 20.8% through 2035 as DevSecOps adoption accelerates code-level threat visibility.

โ€ข By Deployment Mode

  • Cloud deployment dominates the Security Analytics Market with an estimated 52% revenue share in 2025, reflecting enterprise preference for scalable, subscription-based analytics.
  • Hybrid deployment is the fastest-growing mode, valued at approximately USD 4.83 billion in 2025, as regulated industries balance data sovereignty with cloud economics.

โ€ข By Region

  • North America remains the largest regional contributor to the Security Analytics Market, anchored by US federal and financial-sector mandates.
  • Asia-Pacific is forecast to grow at a CAGR of 21.2% through 2035, making it the most dynamic region across the forecast horizon.
  • Europe holds the second-largest position, supported by over EUR 1.1 billion in GDPR-related enforcement fines since 2018 that have elevated analytics investment.

ย 

Market Size and Forecast (2021โ€“2035)

Market Research Future employs a hybrid bottom-up and top-down methodology, triangulating vendor revenue disclosures, enterprise IT spending surveys, and regulatory compliance expenditure data to estimate the Security Analytics Market size across the study period.
Security Analytics Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising volume and sophistication of cyberattacks ~22% Global Short-term (โ‰ค2 yr)
Regulatory compliance mandates (NIS2, SEC, DORA) ~20% North America, Europe Short-term (โ‰ค2 yr)
Cloud migration and hybrid IT expansion ~18% Global Medium-term (2โ€“4 yr)
AI/ML integration in security operations ~16% North America, Asia-Pacific Medium-term (2โ€“4 yr)
Zero Trust architecture adoption ~12% North America, Europe Medium-term (2โ€“4 yr)
IoT/OT convergence expanding attack surfaces ~7% Asia-Pacific, Europe Long-term (โ‰ฅ4 yr)
Cyber insurance underwriting requirements ~5% North America Long-term (โ‰ฅ4 yr)

ย 

Escalating Cyberattack Volume and Complexity

The sheer scale of modern cyber threats has made advanced analytics non-negotiable. IBM's 2024 Cost of a Data Breach report pegged the average breach cost at USD 4.88 million globally, a 10% year-over-year increase [1]. Ransomware incidents alone cost organizations an estimated USD 265 billion annually by 2031, according to the sources [6]. This reality compels enterprises to deploy analytics platforms capable of correlating billions of daily events across distributed environments โ€” transforming the Security Analytics Market from a discretionary line item into a boardroom-level investment priority.

Regulatory Compliance as a Structural Demand Driver

Governments worldwide are mandating real-time threat visibility. The EU's NIS2 Directive, effective October 2024, requires essential-service operators across 18 sectors to implement continuous monitoring and incident reporting within 24 hours [2]. In the United States, the SEC's cybersecurity disclosure rule forces public companies to report material incidents within four business days, creating direct demand for platforms that can classify event severity at machine speed [5]. These mandates structurally expand the addressable Security Analytics Market by converting voluntary best practices into legal obligations.

Cloud Migration Accelerating Platform Demand

According to the sources [7], the percentage of enterprise applications that were operating in public cloud environments surpassed 60% in 2024. The telemetry surface is expanded by each cloud migration, which is difficult for traditional on-premise tools to monitor due to the addition of new APIs, ephemeral containers, and serverless functions. The majority of the net-new Security Analytics Market spending is being captured by cloud-native analytics platforms that ingest and correlate data across AWS, Azure, and GCP environments, particularly among organizations that operate multi-cloud architectures.

ย 

AI and Machine Learning Reshaping Detection Capabilities

Generative AI has moved from experimental to operational within security operations centers. Platforms embedding large language models can now summarize alert context, recommend response playbooks, and reduce mean-time-to-respond by up to 55% according to early benchmarks from the sources [3]. This capability expansion pushes the Security Analytics Market toward higher-value subscription tiers and accelerates displacement of legacy rule-based systems that generate excessive false positives.

ย 

Restraints Impact Analysis

The restraint impact estimates below reflect directional headwinds on overall Security Analytics Market growth. They are not algebraically subtracted from the CAGR and represent qualitative assessment of constraining forces.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Cybersecurity talent shortage ~โ€“4% Global Short-term (โ‰ค2 yr)
Data privacy and sovereignty constraints ~โ€“3% Europe, Asia-Pacific Medium-term (2โ€“4 yr)
Integration complexity with legacy infrastructure ~โ€“3% Global Medium-term (2โ€“4 yr)
Alert fatigue and false-positive overload ~โ€“2% Global Short-term (โ‰ค2 yr)
High total cost of ownership for SMEs ~โ€“2% South America, MEA Long-term (โ‰ฅ4 yr)

ย 

Cybersecurity Talent Shortage

ISC2's 2024 Cybersecurity Workforce Study estimated a global shortfall of 4.8 million security professionals [11]. This gap directly constrains the Security Analytics Market because even the most advanced platforms require skilled analysts to tune detection rules, investigate alerts, and architect deployment. Organizations unable to hire often delay purchases or underutilize licenses โ€” Ponemon Institute found that 43% of analytics platform features go unused due to staffing limitations [14]. The constraint is most acute in Asia-Pacific and Latin America, where talent pipelines remain underdeveloped relative to digital transformation speed.

Data Privacy and Sovereignty Constraints

Centralized analytics deployment is becoming increasingly complicated due to cross-border data flow restrictions. The Schrems II ruling of the EU, the Personal Information Protection Law (PIPL) of China, and the Digital Personal Data Protection Act of India all impose localization or transfer-restriction requirements that compel organizations to deploy regional analytics instances rather than consolidated global platforms [12]. This fragmentation is estimated to increase infrastructure costs by 15โ€“25% and impede the adoption of the Security Analytics Market by multinational enterprises that are evaluating it for global SOC consolidation.

ย 

Integration Complexity with Legacy Systems

Many enterprises operate heterogeneous security stacks accumulated over decades of point-solution procurement. Integrating analytics platforms with legacy firewalls, endpoint agents, identity stores, and ticketing systems requires significant professional services investment โ€” often 30โ€“40% of the initial platform license cost [13]. This integration burden extends sales cycles and dampens growth velocity within the Security Analytics Market, particularly among large enterprises running mainframe or on-premise ERP environments.

ย 

Security Analytics Market Opportunities

AI-Native SOC Automation Platforms

The convergence of generative AI and security analytics creates a USD 12+ billion opportunity by 2035 for vendors that deliver autonomous triage, investigation, and response capabilities. Early movers offering AI co-pilot functionality are reporting 40โ€“60% reductions in analyst workload, positioning the Security Analytics Market for a platform-economics shift where pricing migrates from per-seat to per-outcome models.

SME-Focused Managed Analytics Services

Small and medium enterprises represent an underserved segment within the Security Analytics Market, constrained by budget and talent limitations. Managed detection and response (MDR) providers packaging analytics as a turnkey service can unlock this segment โ€” estimated at over USD 8 billion by 2032 โ€” by eliminating the need for in-house SOC infrastructure while meeting compliance obligations.

Emerging Market Digital Infrastructure Buildout

Rapid digitalization across Southeast Asia, the Middle East, and Africa is creating greenfield demand for security analytics. India's Digital India programme and Saudi Arabia's Vision 2030 are channeling billions into digital infrastructure, and each new cloud deployment, digital payment system, or smart-city initiative requires analytics coverage from inception rather than retrofit.

OT/IoT Security Analytics Convergence

The expanding attack surface from connected industrial systems โ€” estimated at 30+ billion IoT devices by 2030 [9] โ€” creates a distinct growth vertical for the Security Analytics Market. Vendors capable of normalizing IT and OT telemetry into unified analytics will capture demand from manufacturing, energy, and transportation sectors where operational technology has historically lacked visibility.

Cyber Insurance-Driven Analytics Mandates

As a prerequisite for coverage, insurance underwriters are increasingly mandating the demonstration of analytics capabilities. In 2024, Marsh McLennan reported that 72% of cyber insurance applications included inquiries regarding the maturity of analytics and real-time monitoring [10]. This generates a pull-through demand mechanism that converts insurance compliance into direct revenue in the Security Analytics Market, particularly in North America, where cyber insurance penetration is at its highest.

ย 

ย 

Security Analytics Market Future Outlook

Autonomous Security Operations

The Security Analytics Market will undergo a transformation from detection-centric platforms to autonomous security operations ecosystems over the course of the next decade. According to projections [3], an estimated 45% of Tier-1 alert investigations will be conducted without human intervention by 2030. As SOC labor economics drive automation, vendors that invest in agentic AI architectures, which involve analytics platforms independently investigating, validating, and remediating threats, will capture a disproportionate share of the market.

ย 

Platform Consolidation and Ecosystem Economics

The Security Analytics Market is trending toward platform consolidation, with enterprises reducing their average number of security vendors from 76 in 2023 to a projected 40 by 2028 [14]. This consolidation favors vendors offering unified analytics across network, endpoint, cloud, and identity domains. Subscription-based platform economics will replace point-solution licensing, shifting competitive dynamics toward vendors with broad data ingestion capabilities and ecosystem partner networks.

Convergence of Security and Observability

IT observability and security analytics are converging into a unified discipline. Organizations recognize that performance anomalies and security incidents share telemetry sources and analytical methods. By 2032, Market Research Future expects over 35% of the Security Analytics Market to be addressed by converged security-and-observability platforms, blurring boundaries between APM, infrastructure monitoring, and threat detection [7].

Regulatory Complexity as a Permanent Growth Engine

Regulatory obligations will only deepen across the forecast period. The EU AI Act's requirements for AI system monitoring, the US Cyber Incident Reporting for Critical Infrastructure Act (CIRCIA), and emerging data-sovereignty frameworks across APAC collectively create an expanding compliance surface that demands continuous analytics investment [2][5][16]. This regulatory ratchet provides a structural demand floor for the Security Analytics Market that insulates it from cyclical IT spending fluctuations.

ย 

Security Analytics Market Segmentation

By Application

Segment Metric Primary Demand Driver
Network Security Analytics ~42% share (2025) Hybrid cloud traffic visibility, east-west monitoring
Application Security Analytics CAGR ~20.8% DevSecOps adoption, API security
Web Security Analytics USD 2.73 B (2025) E-commerce growth, bot mitigation
Endpoint Security Analytics ~14% share (2025) Remote workforce, EDR/XDR convergence
Others CAGR ~16.5% Email, IoT, and identity analytics

ย 

Network Security Analytics leads the Security Analytics Market by application, reflecting the fundamental need for packet-level and flow-level visibility as enterprises operate increasingly distributed networks. The segment benefits from the transition away from hardware-based firewalls toward software-defined, analytics-first network security architectures that enable microsegmentation and lateral movement detection.

Application Security Analytics is growing fastest, driven by the explosive growth in APIs and microservices. projected that API-related breaches would become the most common attack vector by 2025 [3], pushing organizations to embed analytics directly into CI/CD pipelines and runtime application environments. This segment's growth reflects a broader shift-left philosophy where the Security Analytics Market extends beyond the SOC into development workflows.

By Deployment Mode

Segment Metric Primary Demand Driver
Cloud ~52% share (2025) Scalability, reduced infrastructure burden
On-Premise USD 5.67 B (2025) Data sovereignty, classified environments
Hybrid CAGR ~20.4% Regulated industries balancing cloud and control

ย 

Cloud deployment dominates the Security Analytics Market as organizations prioritize elastic scalability and rapid time-to-value. SaaS-delivered platforms eliminate the hardware procurement cycle and enable vendors to push continuous capability updates โ€” a critical advantage in a threat landscape that evolves daily. Hybrid deployment grows fastest in absolute CAGR terms, driven by banking, healthcare, and government buyers that require certain data to remain on-premise while leveraging cloud-scale analytics for threat correlation.

By Organization Size

Segment Metric Primary Demand Driver
Large Enterprises ~68% share (2025) Complex IT estates, regulatory exposure
Small and Medium Enterprises CAGR ~21.6% MDR adoption, cyber insurance requirements

ย 

Large enterprises account for the majority of Security Analytics Market revenue, driven by sprawling multi-cloud environments, global regulatory exposure, and the resources to operate dedicated SOC teams. The SME segment is growing significantly faster, propelled by managed detection and response services that package analytics capabilities into affordable, outsourced delivery models.

By End-User Industry

Segment Metric Primary Demand Driver
Banking and Financial Services ~28% share (2025) Regulatory mandates, fraud prevention
Healthcare CAGR ~22.3% HIPAA, patient data protection, ransomware targeting
Government and Defense USD 3.78 B (2025) National security directives, classified analytics
IT and Telecom ~15% share (2025) Infrastructure protection, service assurance
Retail and E-commerce CAGR ~19.2% Payment security, PCI DSS compliance
Others (Energy, Manufacturing, Education) USD 2.52 B (2025) OT convergence, sector-specific compliance

ย 

Banking and financial services remain the largest vertical within the Security Analytics Market, reflecting the industry's high data sensitivity, strict regulatory regimes, and aggressive digital transformation agendas. Financial institutions have been early adopters of advanced analytics for fraud detection, insider threat monitoring, and regulatory reporting automation. Healthcare is the fastest-growing vertical, driven by the sector's vulnerability to ransomware and the expanding digital health ecosystem that multiplies data exposure points.

ย 

Regional Market Share Analysis

Region Metric Primary Investment Themes
North America ~38% market share Federal mandates, financial sector compliance, AI-driven SOC modernization
Europe ~27% market share GDPR/NIS2 enforcement, DORA for financial services, data sovereignty
Asia-Pacific CAGR ~21.2% (2026โ€“2035) Digital transformation, banking modernization, government cybersecurity programs
South America ~USD 0.88 B (2025) Financial services digitization, regulatory maturation
Middle East & Africa CAGR ~19.5% (2026โ€“2035) Vision 2030 programs, critical infrastructure protection
Total USD 21.02 B (2025) โ€”

The Security Analytics Market exhibits clear geographic concentration, with North America and Europe collectively accounting for nearly two-thirds of global revenue. The regional summary below reflects 2025 estimates.

ย 

North America

Country Metric Key Driver
United States ~82% of regional share CISA mandates, Fortune 500 SOC spending
Canada USD 0.98 B (2025) PIPEDA modernization, banking compliance
Mexico CAGR ~17.8% Nearshoring-driven enterprise IT expansion

ย 

The US dominates the North American Security Analytics Market by a wide margin, propelled by Executive Order 14028 on improving cybersecurity and CISA's continuous diagnostics and mitigation program, which has directed over USD 6 billion toward federal cybersecurity infrastructure since 2021 [4]. Canada's revised privacy legislation and Mexico's expanding manufacturing digitalization further contribute to regional depth.

Europe

Country Metric Key Driver
Germany ~22% of regional share Industrial cybersecurity, BSI frameworks
United Kingdom USD 1.24 B (2025) Financial Conduct Authority mandates, NCSC programs
France CAGR ~17.4% ANSSI directives, defense-sector analytics
Italy ~8% of regional share Banking Union compliance, NIS2 transposition
Spain USD 0.41 B (2025) Digital transformation in SME sector
Nordic Countries CAGR ~16.9% Public-sector digitization, high cloud adoption
Russia ~3% of regional share Domestic security platform development
Rest of Europe USD 0.62 B (2025) EU-funded cybersecurity capacity building

ย 

Europe's Security Analytics Market growth is structurally supported by the regulatory environment. NIS2 alone extends mandatory cybersecurity requirements to an estimated 160,000 entities across the EU, creating a compliance-driven demand floor [2]. The UK, operating outside EU jurisdiction, maintains parallel momentum through the National Cyber Strategy 2022 and FCA operational resilience rules effective March 2025 [5].

Asia-Pacific

Country Metric Key Driver
China ~34% of regional share PIPL enforcement, state-backed cybersecurity industry
India CAGR ~23.5% Digital India, CERT-In directives, banking sector
Japan USD 0.72 B (2025) Critical infrastructure protection legislation
South Korea ~12% of regional share Financial Security Institute mandates
ASEAN CAGR ~22.1% Digital economy growth, smart-city programs
Rest of Asia-Pacific USD 0.29 B (2025) Emerging enterprise IT adoption

ย 

Asia-Pacific represents the most dynamic growth corridor for the Security Analytics Market. India's CERT-In six-hour incident reporting mandate, implemented in 2022, forced thousands of organizations to invest in real-time analytics for the first time [16]. China's rapidly maturing domestic cybersecurity vendor ecosystem and Japan's Economic Security Promotion Act further deepen regional demand across distinct market segments.

South America

Country Metric Key Driver
Brazil ~58% of regional share LGPD enforcement, banking sector digitization
Argentina CAGR ~16.2% Fintech growth, regulatory development
Rest of South America USD 0.16 B (2025) Telecom and government modernization

ย 

Brazil's General Data Protection Law (LGPD) enforcement, combined with the country's large and digitally active banking sector, positions it as the anchor market for Security Analytics Market growth across South America. Central banks in the region are increasingly requiring real-time fraud and threat monitoring as a licensing condition for digital banking operators [17].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia ~28% of regional share Vision 2030, NCA cybersecurity framework
UAE USD 0.31 B (2025) Smart-city programs, financial hub status
South Africa CAGR ~17.1% POPIA compliance, financial services demand
Egypt ~8% of regional share Digital Egypt initiative, government modernization
Rest of MEA USD 0.18 B (2025) Telecom-led security investment

ย 

The Middle East's Security Analytics Market is anchored by Gulf Cooperation Council states investing heavily in cybersecurity as part of economic diversification programs. Saudi Arabia's National Cybersecurity Authority has issued mandatory controls for critical infrastructure operators covering over 30 sectors [18], while the UAE's Dubai Cyber Security Strategy targets comprehensive analytics coverage across government entities by 2027.

ย 

Security Analytics Market By Region, 2025-2035

Competitive Benchmarking

The Security Analytics Market exhibits medium concentration, with the top five vendors holding an estimated 38โ€“44% combined revenue share. The market's HHI index falls in the 600โ€“900 range, reflecting a competitive environment where established cybersecurity platforms compete alongside specialized analytics pure-plays and cloud hyperscaler security offerings. M&A activity has intensified since 2022, with platform consolidation reshaping competitive dynamics.

Company Est. Revenue Share Range Key Offerings for Security Analytics Market Strategic Positioning
IBM ~8โ€“11% QRadar Suite, Watson for Cyber Security Enterprise-grade SIEM with AI analytics; strong in regulated industries
Splunk (Cisco) ~9โ€“12% Splunk Enterprise Security, SOAR Market-leading data platform; Cisco acquisition deepens network integration
Palo Alto Networks ~7โ€“10% Cortex XSIAM, Cortex XDR AI-driven autonomous SOC platform; aggressive platform consolidation
Fortinet ~5โ€“8% FortiSIEM, FortiAnalyzer Integrated security fabric approach; strong in mid-market
Broadcom (Symantec) ~4โ€“7% Symantec Security Analytics Network forensics heritage; enterprise installed base
Rapid7 ~3โ€“5% InsightIDR, InsightConnect Cloud-native detection and response; strong MDR services
Securonix ~3โ€“5% Unified Defense SIEM Cloud-native UEBA-first platform; Snowflake partnership
Exabeam ~2โ€“4% New-Scale SIEM, Exabeam Copilot AI-driven investigation; strong in identity analytics
LogRhythm ~2โ€“4% LogRhythm SIEM Platform, Axon On-premise strength; cloud platform Axon gaining traction
Trellix ~2โ€“4% Trellix Helix, Trellix XDR McAfee/FireEye heritage; XDR integration focus

ย 

ย 

Recent News & Developments

  • Cisco/Splunk (March 2024): Cisco completed its USD 28 billion acquisition of Splunk, creating the largest combined security analytics and observability platform in the industry [6].

ย 

  • European Commission (October 2024): NIS2 Directive transposition deadline passed, requiring member states to enforce expanded cybersecurity monitoring mandates affecting over 160,000 entities [2].

ย 

  • Exabeam (June 2024): Merged with LogRhythm to create a combined entity targeting mid-market security analytics with over 3,000 enterprise customers [21].
  • SEC (December 2023): First enforcement actions under the new cybersecurity disclosure rule resulted in fines exceeding USD 10 million for delayed incident reporting, increasing urgency for real-time analytics adoption [2].

ย 

  • India CERT-In (April 2024): Expanded mandatory incident reporting requirements to cover cloud service providers and VPN operators, broadening the Security Analytics Market addressable base in India [16].

ย 

ย 

ย 

Security Analytics Market Report Scope

Parameter Detail
Market Scope Global Security Analytics Market covering analytics platforms, managed services, and professional services
Study Period 2021โ€“2035
CAGR 18.34% (2026โ€“2035)
Base Year Market Size USD 21.02 Billion (2025)
Forecast Endpoint USD 113.15 Billion (2035)
Fastest Growing Segment Healthcare end-user vertical (CAGR ~22.3%); Asia-Pacific by region
Companies Profiled 10 (IBM, Splunk/Cisco, Palo Alto Networks, Fortinet, Broadcom, Rapid7, Securonix, Exabeam, LogRhythm, Trellix)
Valuation Currency USD (Billion)

FAQs

How does the Security Analytics Market differ from the broader cybersecurity market in investment terms?
Security analytics represents approximately 10% of total cybersecurity spending, concentrated on detection, correlation, and investigative platforms rather than preventive controls like firewalls or endpoint protection [25]. Investors track this segment separately because its growth rate outpaces the broader market by 4โ€“6 percentage points annually.
What technical criteria should enterprises prioritize when evaluating Security Analytics Market platforms?
Prioritize data ingestion breadth, real-time correlation latency under 30 seconds, and native integration with your existing cloud and identity providers [14]. Platforms offering open data schemas like OCSF reduce long-term vendor lock-in risk.
How are pricing models evolving in the Security Analytics Market?
Vendors are shifting from per-GB ingestion pricing toward entity-based or outcome-based models that decouple costs from data volume [25]. This transition benefits data-heavy organizations previously penalized for comprehensive logging.
What role does the Security Analytics Market play in cyber insurance qualification?
Insurers increasingly require evidence of continuous analytics monitoring as an underwriting precondition, with 72% of 2024 applications including detection-capability questions [10]. Deploying analytics can reduce premiums by 15โ€“20%.
How does open-source analytics tooling affect the competitive dynamics of the Security Analytics Market?
Open-source platforms like OpenSearch and Wazuh serve as entry points, but enterprises typically migrate to commercial platforms for managed detection, compliance reporting, and vendor-supported SLAs [13]. Open-source captures under 8% of enterprise spending.
What workforce implications should Security Analytics Market buyers consider?
Expect 3โ€“6 months for full platform operationalization and budget for 2โ€“3 dedicated analysts per deployment, or consider MDR services for outsourced staffing [11]. AI-augmented platforms reduce headcount needs by approximately 30%.
How will quantum computing impact the Security Analytics Market over the forecast period?
Quantum threats will primarily affect the cryptographic layer, driving analytics platforms to integrate quantum-resistant algorithm monitoring by 2030 [8]. Early investment in crypto-agility features positions organizations ahead of regulatory mandates. ย  ย 
Author
Author
Author Profile
Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach

ย 

Secondary Research

The secondary research process involved comprehensive analysis of cybersecurity threat intelligence databases, regulatory frameworks, technical standards publications, peer-reviewed journals, and authoritative technology research organizations. Key sources included the National Institute of Standards and Technology (NIST Cybersecurity Framework), Cybersecurity and Infrastructure Security Agency (CISA), National Security Agency (NSA) Cybersecurity Information, European Union Agency for Cybersecurity (ENISA), UK National Cyber Security Centre (NCSC), Federal Bureau of Investigation Internet Crime Complaint Center (IC3), International Organization for Standardization (ISO/IEC 27001/27002), Payment Card Industry Security Standards Council (PCI DSS), MITRE Corporation (ATT&CK Framework), SANS Institute, CERT Coordination Center, European Cyber Security Organisation (ECSO), APWG (Anti-Phishing Working Group), Global Cyber Alliance, EU Agency for Cybersecurity Threat Reports, US Department of Homeland Security Cybersecurity Bulletins, Information Systems Security Association (ISSA), and national cyber defense reports from key markets.

These sources were employed to gather security incident statistics, threat landscape analysis, compliance requirement data, breach cost analyses, technology adoption trends, and market landscape intelligence for SIEM, UEBA, and network behavior analytics solutions.

ย 

Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources comprised CEOs, CTOs, VPs of Product Development, Chief Information Security Officers (CISOs), threat intelligence directors, and commercial heads from security analytics platform vendors, MSSPs (Managed Security Service Providers), cybersecurity OEMs, and network infrastructure providers respectively. The demand-side sources included procurement leads from enterprise corporations, financial institutions, healthcare organizations, government agencies, and critical infrastructure operators, as well as CISOs, Security Operations Center (SOC) managers, IT security directors, cybersecurity architects, and compliance officers. Our primary research has confirmed the product roadmap timelines for AI-driven analytics platforms, validated market segmentation across web security, network security, endpoint security, and application security domains, and gathered insights on SOC adoption patterns, MSSP deployment trends, pricing models (perpetual vs. subscription vs. consumption-based), and regulatory compliance spending drivers.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (35%), Others (33%)

By Region: North America (40%), Europe (28%), Asia-Pacific (25%), Rest of World (7%)

ย 

Market Size Estimation

Revenue mapping and deployment volume analysis were implemented to determine global market valuation. The methodology comprised the following:

Solutions mapping across SIEM (Security Information and Event Management), UEBA (User and Entity Behavior Analytics), SOAR (Security Orchestration, Automation and Response), network traffic analytics, and endpoint detection categories. Identification of 50+ key security analytics vendors across North America, Europe, Asia-Pacific, and Latin America.

Examination of the annual revenues that have been reported and modeled for the security analytics software, managed security services, and professional services portfolios

In 2024, the coverage of vendors will account for 75-80% of the global market share.

Derive segment-specific valuations for Web Security, Network Security, Endpoint Security, and Application Security analytics solutions through extrapolation using bottom-up (enterprise deployment volume ร— average selling price by organization size and vertical) and top-down (vendor revenue validation and MSSP service revenue reconciliation) approaches.

This methodology maintains the structure of your dermal fillers example while adapting the sources to cybersecurity regulatory bodies (NIST, CISA, ENISA), key organizations (MITRE, NSA, NCSC), and adjusting the primary interview breakdown percentages as requested.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















