Screw Compressors Market (2026 - 2035)

ID: MRFR/EnP/1280-HCR 111 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Screw Compressors Market Research Report By Technology (Oil-Injected, Oil-Free), By Drive Type (Fixed Speed, Variable Speed Drive), By Power Rating (Below 50 kW, 50–250 kW, Above 250 kW), By End-User Industry (Manufacturing & Metal Fabrication, Oil & Gas, Food & Beverage, Pharmaceuticals & Healthcare, Automotive, Construction & Mining, Chemicals, Power & Others) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
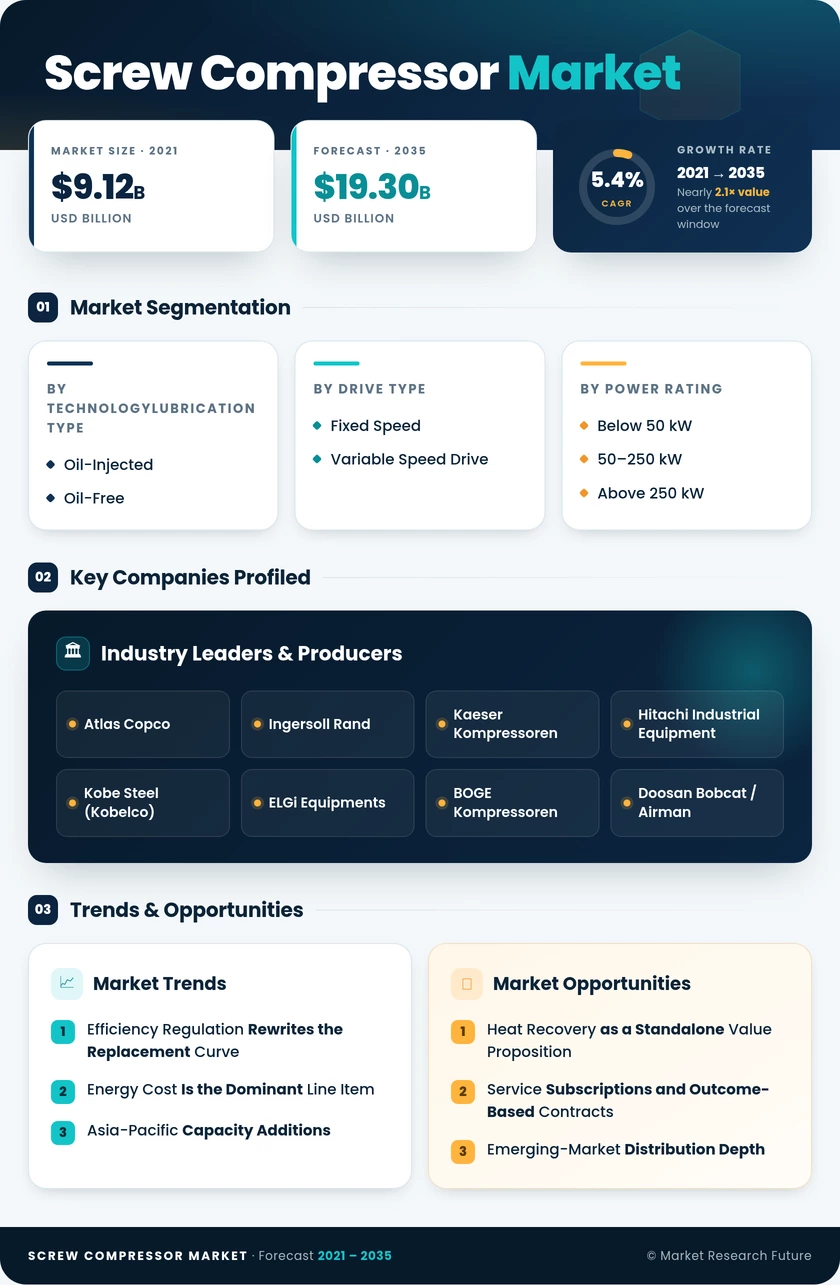
Screw Compressors Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.4%
2025 Market SizeUSD 11.40 Billion
2035 Market SizeUSD 19.30 Billion
Key Players
Atlas Copco
Ingersoll Rand
Kaeser Kompressoren
Hitachi Industrial Equipment
Kobe Steel
ELGi Equipments
Opportunities
  • Heat Recovery as a Standalone Value Proposition
  • Service Subscriptions and Outcome-Based Contracts
  • Emerging-Market Distribution Depth
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Region
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Efficiency Regulation Rewrites the Replacement Curve |
    2. 4.2 Energy Cost Is the Dominant Line Item |
    3. 4.3 Asia-Pacific Capacity Additions |
    4. 4.4 Sterile and Contact Air Requirements
  5. 5 Restraints Impact Analysis |
    1. 5.1 Upfront Cost in Small-Plant Purchases |
    2. 5.2 European Industrial Demand Softness |
    3. 5.3 Leak Management and Addressable Air Volume
  6. 6 Opportunities |
    1. 6.1 Heat Recovery as a Standalone Value Proposition |
    2. 6.2 Service Subscriptions and Outcome-Based Contracts |
    3. 6.3 Emerging-Market Distribution Depth |
    4. 6.4 Data Monetisation Through Connected Controllers |
    5. 6.5 Industrial Gas and Hydrogen Duty
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 United States | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 Italy | |
      3. 7.2.3 United Kingdom | |
      4. 7.2.4 France | |
      5. 7.2.5 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Chile | |
      4. 7.4.4 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 United Arab Emirates | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Machine Intelligence in the Compressor Room |
    2. 8.2 Industrial Electrification Baseline |
    3. 8.3 Service Economics and Aftermarket Consolidation |
    4. 8.4 Sustainability Reporting as Specification
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Technology | |
      1. 9.1.1 Oil-Injected | |
      2. 9.1.2 Oil-Free |
    2. 9.2 By Drive Type | |
      1. 9.2.1 Fixed Speed | |
      2. 9.2.2 Variable Speed Drive |
    3. 9.3 By Power Rating | |
      1. 9.3.1 Below 50 kW | |
      2. 9.3.2 50–250 kW | |
      3. 9.3.3 Above 250 kW |
    4. 9.4 By End-User Industry | |
      1. 9.4.1 Manufacturing & Metal Fabrication | |
      2. 9.4.2 Oil & Gas | |
      3. 9.4.3 Food & Beverage | |
      4. 9.4.4 Pharmaceuticals & Healthcare | |
      5. 9.4.5 Automotive | |
      6. 9.4.6 Construction & Mining | |
      7. 9.4.7 Chemicals, Power & Others
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Screw Compressor Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Screw Compressor Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Market Size, by Lubrication Type, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Market Size, by Drive Type, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Market Size, by Power Rating, 2021–2035 (USD Billion) |
  29. TABLE 14 Global Market Size, by End-Use Industry, 2021–2035 (USD Billion) |
  30. TABLE 15 Competitive Benchmarking Matrix, 2026 |
  31. TABLE 16 Company Profiles – Key Players |
  32. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 |
  33. TABLE 18 Report Scope & Methodology Summary |
  34. TABLE 19 Detailed Sources & Citations Index
  35. 16 LIST OF FIGURES |
  36. FIGURE 1 Market Dynamics – Drivers, Restraints, Opportunities and Challenges |
  37. FIGURE 2 Industry Value Chain Analysis |
  38. FIGURE 3 Porter's Five Forces Analysis |
  39. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 |
  40. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 |
  41. FIGURE 6 Market Share by Lubrication Type, 2025 vs 2035 |
  42. FIGURE 7 Market Share by Drive Type, 2025 vs 2035 |
  43. FIGURE 8 Market Share by Power Rating, 2025 |
  44. FIGURE 9 Market Share by End-Use Industry, 2025 |
  45. FIGURE 10 Regional Revenue Share Distribution, 2025 |
  46. FIGURE 11 Regional CAGR Comparison, 2026–2035 |
  47. FIGURE 12 Competitive Landscape – Estimated Revenue Share Positioning, 2026 |
  48. FIGURE 13 Strategic Positioning Matrix – Technology Depth vs Service Reach

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TechnologyOil-Injected; Oil-FreeOil-InjectedOil-Free
By Drive TypeFixed Speed; Variable Speed DriveFixed SpeedVariable Speed Drive
By Power RatingBelow 50 kW; 50–250 kW; Above 250 kW50–250 kWAbove 250 kW
By End-User IndustryManufacturing & Metal Fabrication; Oil & Gas; Food & Beverage; Pharmaceuticals & Healthcare; Automotive; Construction & Mining; Chemicals, Power & OthersManufacturing & Metal FabricationPharmaceuticals & Healthcare
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificMiddle East & Africa


Market Segmentation Overview

By Technology

Sub-SegmentKey Trend
Oil-InjectedEfficiency gains from improved rotor profiles and premium drive trains
Oil-FreeClass 0 certification becoming a tender prerequisite in hygienic processing


Lubrication choice is increasingly a compliance decision rather than a cost decision. As specific-power gaps narrow, contamination risk and audit documentation drive selection in food, beverage, semiconductor, and pharmaceutical plants.

By Drive Type

Sub-SegmentKey Trend
Fixed SpeedRetained for stable base-load duty within sequenced compressor rooms
Variable Speed DriveRapid adoption where demand fluctuates, and industrial tariffs are high


Drive selection now depends on load profile analysis rather than nameplate capacity. Sites with wide shift-to-shift variation record the largest savings, and hybrid rooms pairing a base-load fixed unit with a trimming variable unit have become standard practice.

By Power Rating

Sub-SegmentKey Trend
Below 50 kWPrice-sensitive band contested by regional manufacturers
50–250 kWCore replacement band most affected by motor efficiency regulation
Above 250 kWEngineered process duty with long lead times and custom packaging


Regulatory pressure concentrates in the mid band, where the 2023 European efficiency deadline stranded a large installed base. Large-frame demand tracks petrochemical, mining, and utility capital cycles more than efficiency policy.

By End-User Industry

Sub-SegmentKey Trend
Manufacturing & Metal FabricationBroad pneumatic tooling and automation air demand
Oil & GasInstrument air reliability and process gas handling
Food & BeverageHygienic conveying and packaging air purity requirements
Pharmaceuticals & HealthcareCleanroom validation and sterile air documentation
AutomotivePaint shop and assembly line pneumatics, EV plant build-out
Construction & MiningPortable and high-duty units for drilling and material handling
Chemicals, Power & OthersAeration, blanketing, and general plant utilities


Demand breadth insulates the sector from single-industry downturns. Regulated industries set the technical benchmark, and their specifications gradually diffuse into adjacent sectors, raising average configuration value across the installed base through 2035.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.