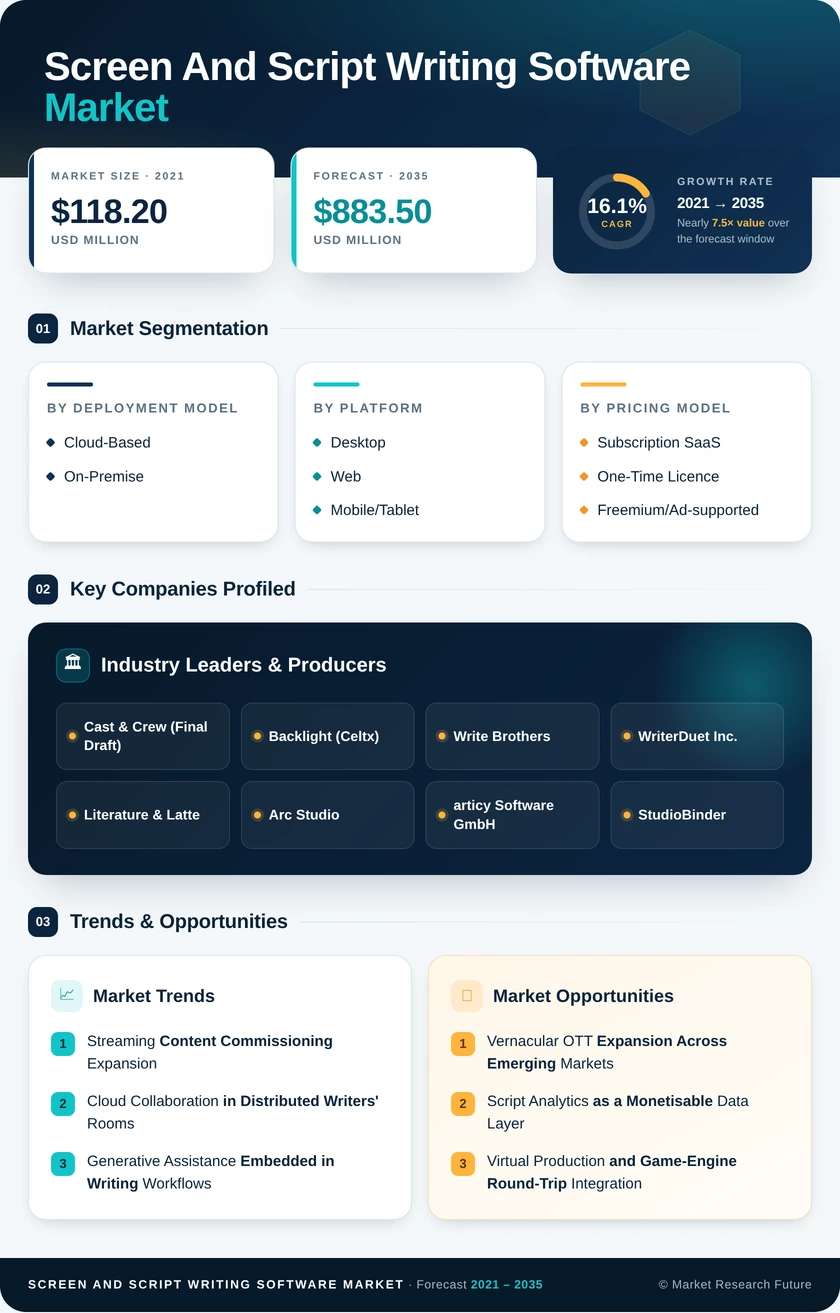
Screen and Script Writing Software Market (2026 - 2035)

ID: MRFR/ICT/19862-HCR 128 Pages Kiran Jinkalwad Last Updated: September 10, 2026
Screen and Script Writing Software Market Size, Share and Research Report By Deployment Model (Cloud-Based and On-Premise), By Platform (Desktop, Web, and Mobile/Tablet), By Pricing Model (Subscription SaaS, One-Time Licence, and Freemium/Ad-supported), By End-User (Film and TV Studios, Independent Screenwriters, Educational Institutions, Gaming Studios, Other End Users, and Advertising and Marketing Agencies), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035.
Screen and Script Writing Software Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.1%
2025 Market SizeUSD 198.6 Million
2035 Market SizeUSD 883.5 Million
Key Players
Cast & Crew
Backlight
Write Brothers
WriterDuet Inc.
Literature & Latte
Arc Studio
Opportunities
  • Vernacular OTT Expansion Across Emerging Markets
  • Script Analytics as a Monetisable Data Layer
  • Virtual Production and Game-Engine Round-Trip Integration
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Deployment Model | |
    2. 2.2 By Platform | |
    3. 2.3 By Pricing Model | |
    4. 2.4 By End-User | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Million) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Streaming Content Commissioning Expansion | |
    2. 4.2 Cloud Collaboration in Distributed Writers' Rooms | |
    3. 4.3 Generative Assistance Embedded in Writing Workflows | |
    4. 4.4 Union and Guild Digital Compliance Requirements | |
    5. 4.5 Film and Media Education Enrolment Growth | |
    6. 4.6 Interactive and Game Narrative Production | |
    7. 4.7 Vernacular Content Localisation in Emerging Markets | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Free and Open-Source Substitutes Suppressing ARPU | |
    2. 5.2 Copyright Uncertainty Around Machine-Assisted Authorship | |
    3. 5.3 Post-Strike Production Volume Contraction | |
    4. 5.4 Pre-Release Script Leak and Data-Security Exposure | |
    5. 5.5 Format Lock-In Reducing Switching Incentive | |
  6. 6 Opportunities | |
    1. 6.1 Vernacular OTT Expansion Across Emerging Markets | |
    2. 6.2 Script Analytics as a Monetisable Data Layer | |
    3. 6.3 Virtual Production and Game-Engine Round-Trip Integration | |
    4. 6.4 Institutional Licensing Funnels From Education to Profession | |
    5. 6.5 Suite Consolidation Through Vertical Bundling | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Assisted Authorship With Verifiable Provenance | |
    2. 8.2 Platform Economics and the Shift to Pre-Production Suites | |
    3. 8.3 The Vernacular Content Supercycle | |
    4. 8.4 Rights Administration and Workforce Transparency Reporting | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Deployment Model | | |
      1. 9.1.1 Cloud-Based | | |
      2. 9.1.2 On-Premise | |
    2. 9.2 By Platform | | |
      1. 9.2.1 Desktop | | |
      2. 9.2.2 Web | | |
      3. 9.2.3 Mobile/Tablet | |
    3. 9.3 By Pricing Model | | |
      1. 9.3.1 Subscription SaaS | | |
      2. 9.3.2 One-Time Licence | | |
      3. 9.3.3 Freemium/Ad-supported | |
    4. 9.4 By End-User | | |
      1. 9.4.1 Film and TV Studios | | |
      2. 9.4.2 Independent Screenwriters | | |
      3. 9.4.3 Educational Institutions | | |
      4. 9.4.4 Gaming Studios | | |
      5. 9.4.5 Other End Users | | |
      6. 9.4.6 Advertising and Marketing Agencies | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Screen And Script Writing Software Market Size & Forecast, by Revenue (USD Million), 2021–2035 | |
  16. TABLE 2 Global Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Million) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Million) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Million) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Million) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Million) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Million) | |
  25. TABLE 11 Global Market Size, by Deployment Model, 2021–2035 (USD Million) | |
  26. TABLE 12 Global Market Size, by Platform, 2021–2035 (USD Million) | |
  27. TABLE 13 Global Market Size, by Pricing Model, 2021–2035 (USD Million) | |
  28. TABLE 14 Global Market Size, by End-User, 2021–2035 (USD Million) | |
  29. TABLE 15 North America Market Size, by Deployment Model, 2021–2035 (USD Million) | |
  30. TABLE 16 Europe Market Size, by Platform, 2021–2035 (USD Million) | |
  31. TABLE 17 Asia-Pacific Market Size, by Pricing Model, 2021–2035 (USD Million) | |
  32. TABLE 18 South America Market Size, by End-User, 2021–2035 (USD Million) | |
  33. TABLE 19 Middle East & Africa Market Size, by Deployment Model, 2021–2035 (USD Million) | |
  34. TABLE 20 Competitive Benchmarking Matrix, 2026 | |
  35. TABLE 21 Company Profiles — Key Players | |
  36. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 | |
  37. TABLE 23 Report Scope & Methodology Summary | |
  38. TABLE 24 Detailed Sources and Citations | | LIST OF FIGURES | |
  39. FIGURE 1 Market Dynamics — Drivers, Restraints, and Opportunities | |
  40. FIGURE 2 Industry Value Chain Analysis | |
  41. FIGURE 3 Porter's Five Forces Analysis | |
  42. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Million) | |
  43. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 | |
  44. FIGURE 6 Market Share by Deployment Model, 2025 vs 2035 | |
  45. FIGURE 7 Market Share by Platform, 2025 vs 2035 | |
  46. FIGURE 8 Market Share by Pricing Model, 2025 vs 2035 | |
  47. FIGURE 9 Market Share by End-User, 2025 vs 2035 | |
  48. FIGURE 10 Regional Market Share Distribution, 2025 | |
  49. FIGURE 11 Regional CAGR Comparison, 2026–2035 | |
  50. FIGURE 12 North America Country-Level Share Breakdown, 2025 | |
  51. FIGURE 13 Asia-Pacific Country-Level Share Breakdown, 2025 | |
  52. FIGURE 14 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  53. FIGURE 15 Competitive Positioning Matrix — Capability vs Market Presence

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Deployment ModelCloud-Based; On-PremiseCloud-Based (61.7% share)Cloud-Based (61.7% share)
By PlatformDesktop; Web; Mobile/TabletDesktop (47.6% share)Web (17.7% CAGR)
By Pricing ModelSubscription SaaS; One-Time Licence; Freemium/Ad-supportedSubscription SaaS (57.0% share)Freemium/Ad-supported (18.4% CAGR)
By End-UserFilm and TV Studios; Independent Screenwriters; Educational Institutions; Gaming Studios; Other End UsersFilm and TV Studios (36.9% share)Independent Screenwriters (20.2% CAGR)


Market Segmentation Overview

By Deployment Model

Sub-SegmentKey Trend
Cloud-BasedVendor-hosted workspaces with immutable revision history become the studio default
On-PremiseRetained only where contractual terms forbid third-party hosting of pre-release scripts


Cloud-Based deployment carries 61.7% of 2025 revenue and also sets the pace on growth, because hosted environments resolve concurrent-editing conflicts and give showrunners instant visibility into revision colours across a distributed room. On-Premise persists at legacy post-production facilities whose air-gapped policies predate modern encryption standards, and it expands at only 9.2% annually. Improvements in audit logging and single sign-on are steadily removing the security objection that once justified local installations. New studio investment now overwhelmingly favours vendor-hosted infrastructure.

By Platform

Sub-SegmentKey Trend
DesktopOffline dependability sustains union-writer preference despite feature parity elsewhere
WebProgressive web app architecture eliminates installation and version-mismatch friction
Mobile/TabletOn-set annotation and LED-stage revision review drive niche but strategic adoption


Desktop leads with 47.6% share, sustained by writers whose formatting habits and archivedfdx libraries pre-date browser tooling. Web grows fastest at a 17.7% CAGR because Chromebook standardisation across film-school labs removes desktop binaries from an entire cohort's option set, and because silent auto-updating spares producers the version-mismatch problems that plague circulated files. Mobile/Tablet contributes modest revenue but influences purchasing, since virtual-production teams increasingly mark up pages on tablets at the stage rather than distributing printed sides.

By Pricing Model

Sub-SegmentKey Trend
Subscription SaaSRecurring billing funds continuous assistance-model and security investment
One-Time LicencePerpetual packages survive only when paired with optional cloud add-ons
Freemium/Ad-supportedTiered gating on page counts and watermarked exports seeds creator ecosystems


Subscription SaaS holds 57.0% share and remains the structural basis of vendor economics, since certification costs and assistance-model maintenance require predictable recurring revenue rather than one-off purchases. Freemium/Ad-supported expands fastest at 18.4%, functioning as a low-cost acquisition channel that converts a small share of a very large aspiring-writer base. One-Time Licence revenue is concentrated among established professionals resisting recurring billing, and its position erodes each year as interchange and collaboration features migrate exclusively to hosted tiers.

By End-User

Sub-SegmentKey Trend
Film and TV StudiosGuild compliance and content-security requirements dictate vendor shortlists
Independent ScreenwritersDirect distribution economics drive self-funded subscription purchases
Educational InstitutionsDepartmental site licences establish format habits before graduation
Gaming StudiosBranching-narrative authoring bought on engineering rather than creative budgets
Other End UsersAgency and corporate teams need simultaneous multi-length cutdown outputs


Film and TV Studios generate the largest revenue block at 36.9%, buying multi-seat enterprise contracts where disclosure logging and pre-release security are contractual prerequisites rather than preferences. Independent Screenwriters grow fastest at a 20.2% CAGR as micro-studios absorb writing, financing, and distribution functions that majors once controlled. Gaming Studios apply entirely different selection criteria — variable state tracking, flowchart authoring, and engine round-tripping — which is why specialist tools rather than screenplay editors dominate that cohort.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.