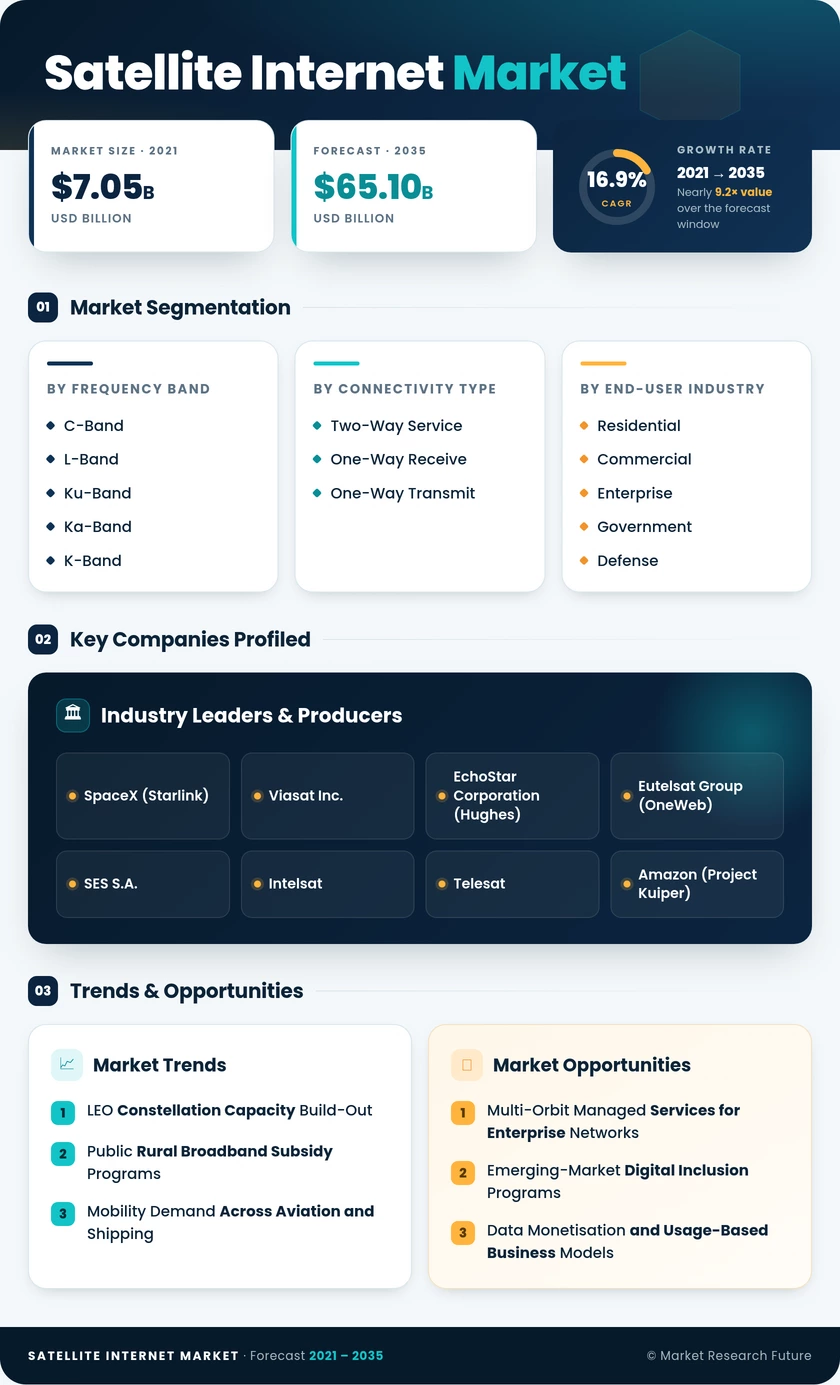
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Frequency Band | C-Band, L-Band, Ku-Band, Ka-Band, K-Band, X-Band, Other Frequency Bands | Ka-Band (29.7% share, 2025) | K-Band (18.4% CAGR, 2026–2035) |
| By Connectivity Type | Two-Way Service, One-Way Receive, One-Way Transmit | Two-Way Service (48.5% share, 2025) | Two-Way Service (16.5% CAGR, 2026–2035) |
| By End-User Industry | Residential, Commercial and Enterprise, Government and Defense, Maritime, Aviation | Commercial and Enterprise (50.9% share, 2025) | Residential (17.2% CAGR, 2026–2035) |
| By Orbital Regime | LEO, MEO, GEO | LEO (40.0% share, 2025) | LEO (17.1% CAGR, 2026–2035) |
| By Application | Backhaul and Rural Cell-Site Connectivity, Mobility, Enterprise Cloud Access, Emergency Response | Backhaul and Rural Cell-Site Connectivity (36.0% share, 2025) | Mobility (17.6% CAGR, 2026–2035) |
Market Segmentation Overview
By Frequency Band
| Sub-Segment | Key Trend |
| C-Band | Retained for rain-fade resilience in tropical maritime corridors |
| L-Band | Anchored to safety-of-life and narrowband telemetry obligations |
| Ku-Band | Large installed enterprise and maritime base slowing migration |
| Ka-Band | Per-Mbps pricing advantage drives cloud backhaul and in-flight adoption |
| K-Band | Digital beam-forming payloads unlock new high-throughput capacity |
| X-Band | Reserved government and defense allocations with stable volumes |
| Other Frequency Bands | Optical and experimental links entering limited commercial trials |
Ka-Band leads on cost per delivered megabit, which is why cloud backhaul and in-flight service concentrate there after the 2024 spectrum release eased beam congestion. K-Band grows fastest because next-generation payloads pair it with digital beam-forming, raising spectral efficiency without proportional spacecraft mass. Ku-Band retains the largest legacy enterprise and maritime base, so operators deploy dual-band payloads that let those customers migrate without re-terminating every site at once. C-Band, L-Band and X-Band hold defensible positions where regulatory or safety requirements outweigh throughput economics.
By Connectivity Type
| Sub-Segment | Key Trend |
| Two-Way Service | Interactive cloud workflows and LEO gateway integration into SD-WAN |
| One-Way Receive | Multicast weather, media, and telemetry distribution retains niche economics |
| One-Way Transmit | Sensor networks and asset tracking with low duty-cycle uplinks |
Two-Way Service both dominates and grows fastest, because tele-engineering, real-time collaboration and IoT telemetry cannot tolerate asymmetric bandwidth. One-Way Receive survives where multicast still beats duplex on cost per recipient, notably maritime weather and media distribution, but declining duplex pricing steadily erodes that advantage. One-Way Transmit remains a small, specialised layer serving low duty-cycle sensor uplinks. Hybrid unicast-multicast architectures function as the commercial bridge, letting operators keep monetising legacy GEO transponders while LEO capacity ramps.
By End-User Industry
| Sub-Segment | Key Trend |
| Residential | Voucher-subsidised terminals expand rural household addressability |
| Commercial and Enterprise | Managed SD-WAN links procured as terrestrial-outage insurance |
| Government and Defense | Multi-orbit tactical capacity contracts stabilise operator cash flow |
| Maritime | Carbon-intensity reporting and crew welfare drive fleet retrofits |
| Aviation | Passenger connectivity shifts from cost centre to ancillary revenue |
Commercial and Enterprise buyers hold the largest share because banks, energy majors and cloud providers now treat satellite links as a resilience layer rather than a last resort, and they buy managed outcomes rather than raw capacity. Residential grows fastest, since terminal subsidy removes the single largest adoption barrier for rural households. Government and Defense demand is steady rather than cyclical, underwritten by multi-year commercial capacity programs. Maritime and Aviation are smaller but strategically valuable, delivering higher revenue per terminal on multi-year fleet contracts.
By Orbital Regime
| Sub-Segment | Key Trend |
| LEO | Sub-30 ms latency enables interactive and real-time applications |
| MEO | Mid-latency capacity serving enterprise backup and government routes |
| GEO | Wide-footprint broadcast and video distribution economics remain unmatched |
LEO leads on share and on growth, because latency below 30 milliseconds opens application classes — gaming, remote desktop, real-time trading — that GEO physics simply excludes. GEO nonetheless retains a large revenue base, since distributing identical content across a continental footprint from one spacecraft is still the cheapest architecture available. MEO occupies a deliberate middle position for enterprise backup and government routing. Constellation operators now face debris-avoidance and replacement-planning costs that GEO incumbents largely avoid, which partially offsets LEO's latency advantage.
By Application
| Sub-Segment | Key Trend |
| Backhaul and Rural Cell-Site Connectivity | Coverage mandates outpace terrestrial fiber economics in low-density terrain |
| Mobility | Aviation, shipping and land transport converge on high-bandwidth telemetry |
| Enterprise Cloud Access | Bundled satellite-plus-terrestrial subscriptions simplify procurement |
| Emergency Response | Independence from ground infrastructure drives inelastic demand |
Backhaul and Rural Cell-Site Connectivity leads because mobile operators facing coverage obligations find satellite cheaper than trenching fiber once terrain and permitting are priced in, and multi-orbit managed services now meet carrier-grade uptime requirements. Mobility grows fastest as fleets across aviation, merchant shipping, and land transport adopt continuous telemetry and passenger services. Enterprise Cloud Access expands through single-subscription bundling that eases compliance and vendor management. Emergency Response buyers purchase independence from terrestrial assets, making that demand structurally price-insensitive.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA