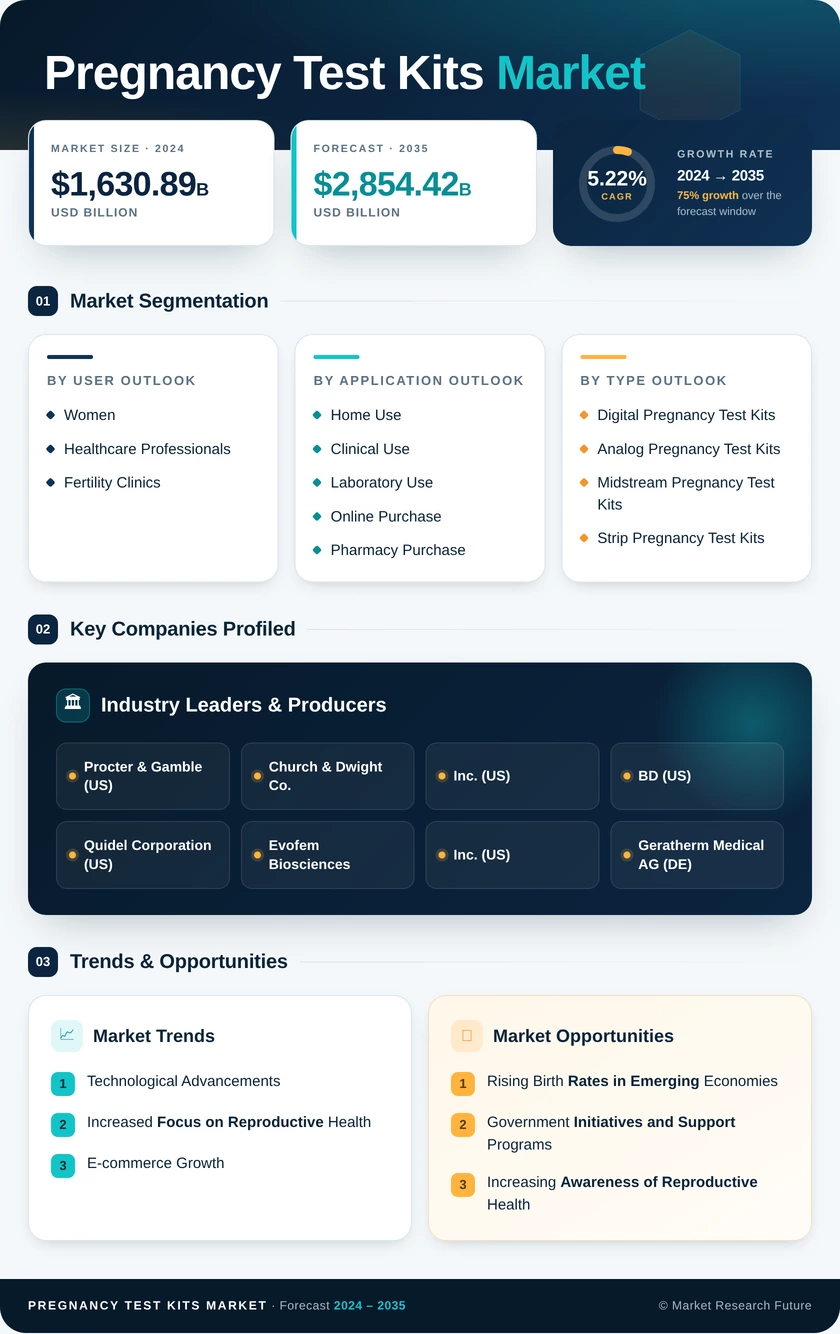
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Product Type | Line Pregnancy Tests (Test Cassette Format, Test Strip Format, Test Midstream Format); Digital Devices; Smart-Connected Devices | Line Pregnancy Tests (57.4% share) | Smart-Connected Devices (7.1% CAGR) |
| By Type of Test | Urine hCG Test; Blood hCG Test | Urine hCG Test (87.8% share) | Blood hCG Test (6.1% CAGR) |
| By Distribution Channel | Hospital Pharmacies; Independent Pharmacies & Drug Stores; Online Pharmacies; Modern Retail & Hypermarkets | Independent Pharmacies & Drug Stores (39.4% share) | Online Pharmacies (6.6% CAGR) |
| By End User | Home-care (Individuals); Gynecology & Obstetrics Clinics; Hospitals & Diagnostic Centers | Home-care (Individuals) (75.1% share) | Home-care (Individuals) (75.1% share) |
| By Region | North America; Europe; Asia-Pacific; Middle East and Africa; South America | North America (38.6% share) | Asia-Pacific (6.8% CAGR (2026–2035)) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Line Pregnancy Tests | Midstream formats replacing cassettes at retail; strips dominate online multi-packs |
| Digital Devices | Written results and weeks indicators remove line-reading ambiguity. |
| Smart-Connected Devices | Bluetooth readers and companion apps enable data-linked follow-up. |
Line Pregnancy Tests lead on revenue because their cost advantage and broad pharmacy distribution suit both mass retail and public tenders. Smart-Connected Devices grow fastest, as app integration and personal content justify prices several times higher. Digital Devices serve buyers who want clear results without sharing data.
| Sub-Segment | Key Trend |
|---|
| Urine hCG Test | CLIA-waived and Class B self-test pathways keep costs low |
| Blood hCG Test | CE-marked finger-stick kits move earlier detection beyond the laboratory. |
Urine hCG Test remains dominant because its regulatory pathway is straightforward and consumers already trust it. Blood hCG Test grows faster, since detection several days earlier matters to fertility clinics and couples tracking assisted-reproduction cycles. Lancet safety and regulatory review will shape how quickly blood kits reach home users.
| Sub-Segment | Key Trend |
|---|
| Hospital Pharmacies | Supervised testing for high-risk and fertility-treatment patients |
| Independent Pharmacies & Drug Stores | Pharmacist advice and immediate availability |
| Online Pharmacies | Discreet delivery and subscription refills |
| Modern Retail & Hypermarkets | Store-brand pricing and promotional bundles |
Independent Pharmacies & Drug Stores lead because many buyers want a test immediately and value pharmacist guidance. Online Pharmacies grow fastest, as private delivery and auto-replenishment fit the sensitive nature of the purchase. Modern Retail & Hypermarkets compete on store-brand pricing, while Hospital Pharmacies stay focused on clinical cases.
| Sub-Segment | Key Trend |
|---|
| Home-care (Individuals) | Self-directed testing linked to telehealth consultations |
| Gynecology & Obstetrics Clinics | Quantitative confirmation of positive home results |
| Hospitals & Diagnostic Centers | Testing for assisted reproduction and complicated pregnancies |
Home-care (Individuals) is both the largest and fastest-growing group, as affordable multi-packs and digital readouts let women confirm pregnancy privately before seeing a clinician. Gynecology & Obstetrics Clinics provide quantitative confirmation, while Hospitals & Diagnostic Centers concentrate on fertility treatment and high-risk cases. Clinical volumes grow more slowly as routine screening moves into the home.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA