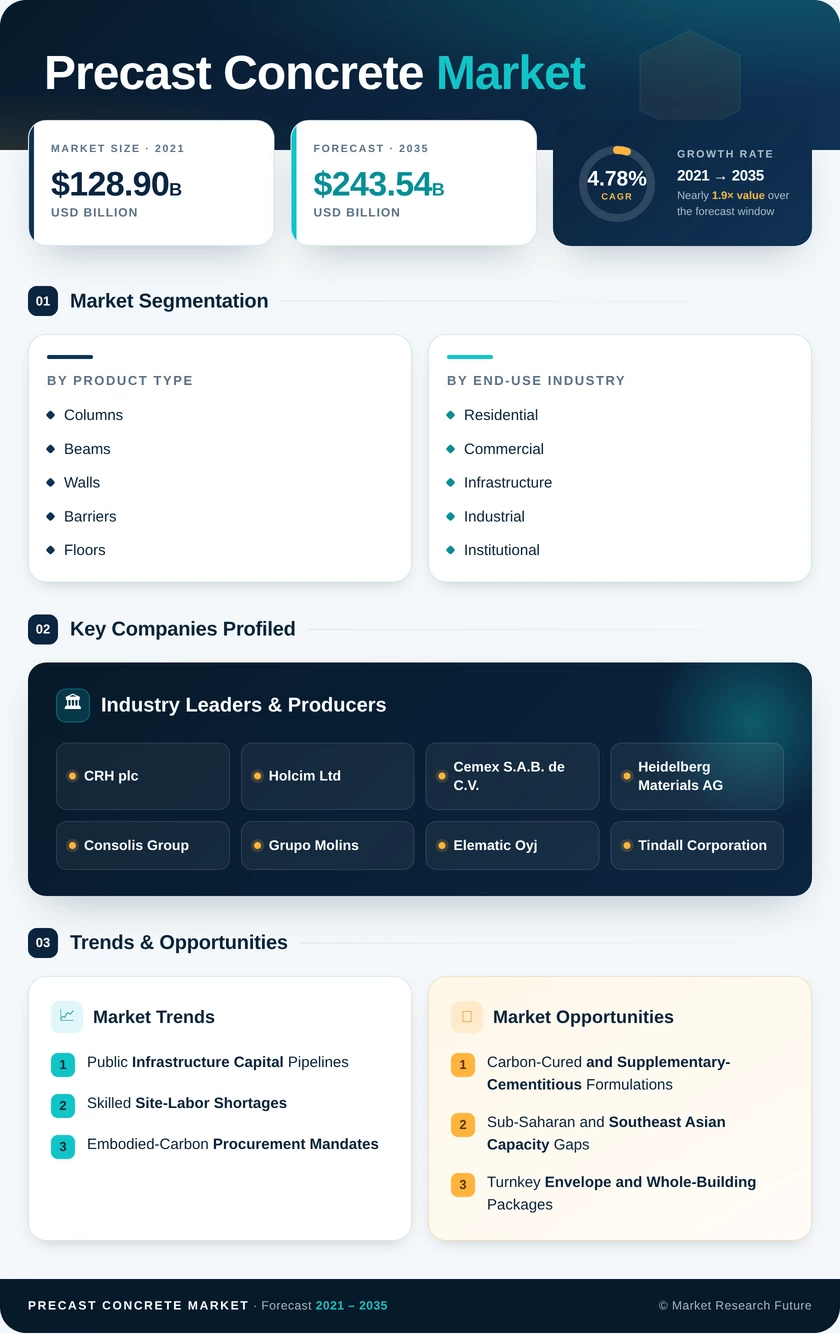
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Columns and Beams; Walls and Barriers; Floors and Roofs; Pipes; Paving Slabs; Others | Columns and Beams (39.2% share, 2025) | Walls and Barriers (5.42% CAGR, 2026–2035) |
| By End-use Industry | Residential; Commercial; Infrastructure; Industrial and Institutional | Infrastructure (34.0% share, 2025) | Residential (5.02% CAGR, 2026–2035) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Columns and Beams | Prestressing capability and load-bearing tolerance keep casting in controlled plants |
| Walls and Barriers | Integrated insulation and conduit chases convert panels into turnkey envelope units |
| Floors and Roofs | Long-span hollow-core slabs reduce on-site shoring duration |
| Pipes | Demand follows municipal water and wastewater funding cycles |
| Paving Slabs | Streetscape renewal and permeable surfacing specifications |
| Others | Architectural cladding, stairs, and utility vaults with bespoke tooling |
Columns and beams lead this dimension because bridge and high-rise frames demand dimensional precision and prestressing that site casting cannot deliver economically, which keeps the segment attached to the most heavily funded project categories. Walls and barriers grow fastest as producers embed insulation, services routing, and standardized connection hardware into panels, shifting the buyer conversation from price per cubic metre to installed envelope cost. Floors and roofs remain volume-stable on open-plan preferences, while pipes and paving slabs move on municipal budget cycles that run independently of the private building cycle.
By End-use Industry
| Sub-Segment | Key Trend |
| Residential | Full-frame packages compress schedules and advance financing drawdowns |
| Commercial | Parking decks and mixed-use podiums prioritize speed-to-revenue |
| Infrastructure | Bridge, tunnel, and desalination awards sustain baseline volume |
| Industrial and Institutional | Vibration and cleanliness criteria favor factory dimensional control |
Infrastructure holds the largest share because girders, tunnel linings, and marine elements have no practical alternative production method at the required scale, and public funding cycles insulate the segment from interest-rate sensitivity. Residential advances fastest as housing ministries attach subsidy eligibility to delivery timelines, giving developers a direct financial reason to adopt factory-supplied frames. Commercial buyers concentrate on parking and podium structures where repetition is high, while industrial and institutional demand rewards tolerance consistency in laboratories, hospitals, and logistics facilities rather than the lowest unit price.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA