Plus Size Clothing Market (2026 - 2035)

Plus Size Clothing Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Formal Wear, Casual Wear, Sportswear, Nightwear and More), By End User (Women, Men, Unisex), By Price Range (Mass, Premium/Luxury), By Distribution Channel (Online Retail Stores, Offline Retail Stores), By Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa) – Forecast Till 2035
ID: MRFR/CG/19123-HCR 128 Pages Varsha More Last Updated: September 27, 2026
Plus Size Clothing Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.97%
2025 Market SizeUSD 334.18 Billion
2035 Market SizeUSD 566.82 Billion
Key Players
Industria de Diseño Textil
H&M Group
Shein
Fast Retailing
Gap Inc.
NIKE, Inc.
Opportunities
  • Native Pattern Blocks as Competitive Moat
  • Emerging-Market Whitespace
  • Fit-Data Monetization and Licensing

Plus Size Clothing Market Summary

The Plus Size Clothing Market reached USD 334.18 Billion in 2025 and opens the forecast window at USD 336.36 Billion in 2026, climbing to USD 566.82 Billion by 2035 at a 5.97% CAGR. Two catalysts anchor that trajectory. First, the World Health Organization now counts more than 1.9 billion adults as overweight, a base that has expanded every decade since 1975 [1]. Second, retail capital has followed: apparel groups committed an estimated USD 2.4 billion between 2023 and 2025 to pattern engineering, fit-technology licensing, and dedicated extended-size supply lines .

Merchandising itself is being rebuilt. Grading standard patterns upward — the legacy approach — is giving way to block patterns drafted natively for larger bodies, supported by 3D body-scanning and virtual try-on. Roughly 41% of the top 100 global apparel retailers had deployed some form of AR or scan-based sizing by late 2025 [9]. That shift matters commercially, because fit-related returns historically ran 8–12 percentage points higher in extended-size apparel than in straight sizes [11], and each avoided return protects margin in a category where fabric consumption is already elevated. The Plus Size Clothing Market is therefore as much a technology story as a demographic one.

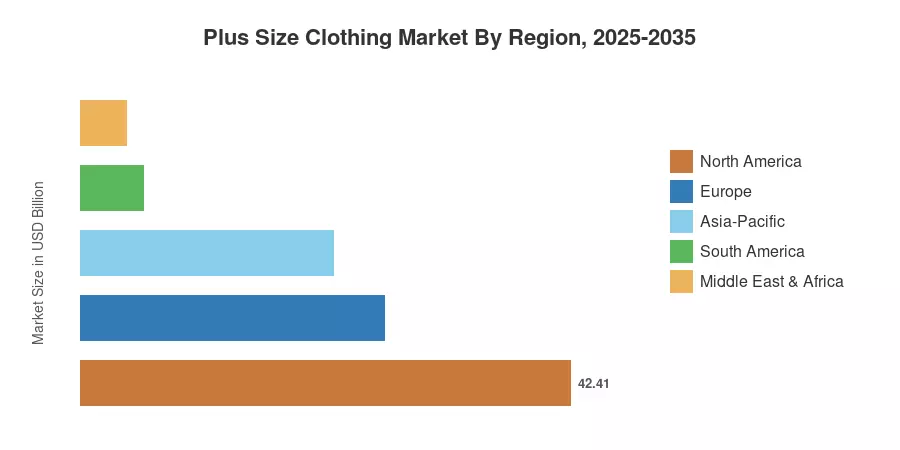
North America holds 42.41% of global value, supported by the deepest specialty-retail base and the highest average selling prices. Asia-Pacific grows fastest at 5.81% CAGR as Chinese and Indian platforms scale inclusive assortments. Europe ranks second at 26.35%, driven by circularity regulation and strong private-label penetration. Expect the gap between these blocs to narrow through 2030 as the Plus Size Clothing Market matures outside its traditional Western core.


Key Report Takeaways

• By Product Type

  • Casual wear led the Plus Size Clothing Market with 33.09% share in 2025, reflecting its role as the entry category for most first-time extended-size buyers
  • Sportswear is the fastest-growing product type at an 8.11% CAGR through 2035

• By End User

  • Men accounted for 65.16% of the Plus Size Clothing Market in 2025, a legacy of long-standing big-and-tall retail infrastructure
  • Women's apparel is compounding at 8.03% CAGR on designer collaborations and creator-led discovery

• By Distribution Channel

  • Offline retail stores generated USD 227.51 Billion in 2025
  • Online retail is advancing at 10.34% CAGR, the fastest growth rate anywhere in the Plus Size Clothing Market

• By Region

  • North America commanded 42.41% share in 2025
  • Asia-Pacific is the fastest-growing region at 5.81% CAGR
  • Europe generated USD 88.06 Billion in 2025


Market Size and Forecast (2021–2035)

Historical values were reconstructed from company segment disclosures, national retail-sales statistics, customs trade data, and point-of-sale panels covering 27 countries. Forecast years apply a bottom-up build across five regions and four segmentation dimensions, cross-checked against top-down category penetration rates. The Plus Size Clothing Market series below is expressed in USD Billion at manufacturer selling price.
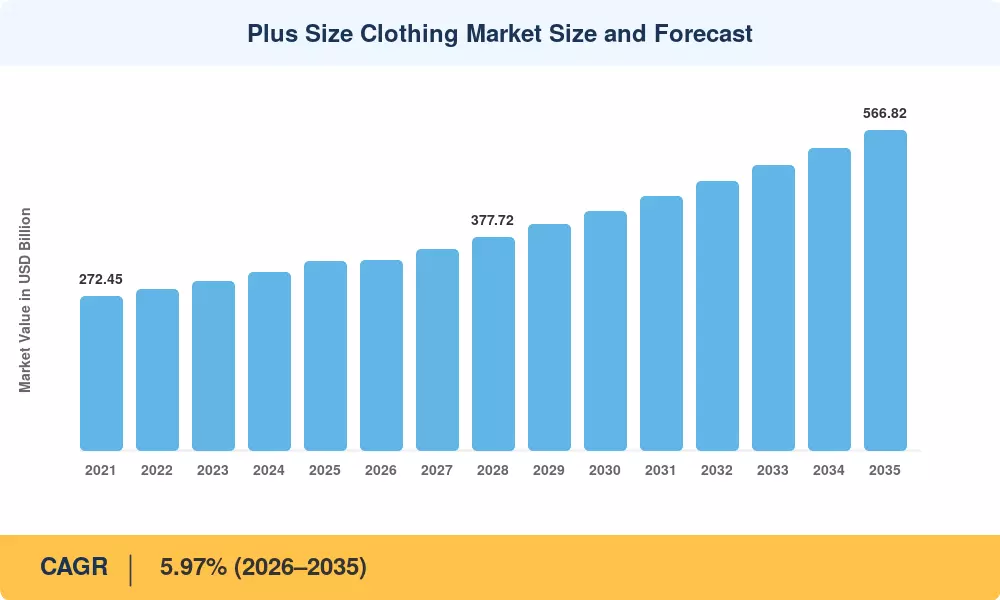
Plus Size Clothing Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising global obesity and BMI prevalence +1.40 pp Global Long-term (≥4 yr)
Body-positivity culture and inclusive marketing +1.05 pp North America, Europe Medium-term (2–4 yr)
E-commerce plus AR/3D fit technology +0.90 pp Global Short-term (≤2 yr)
Athleisure crossover into extended sizing +0.80 pp North America, Asia-Pacific Medium-term (2–4 yr)
Native block-pattern and grading investment +0.60 pp Europe, North America Medium-term (2–4 yr)
Assortment expansion by mass merchants +0.50 pp Global Short-term (≤2 yr)
Disposable income growth in emerging economies +0.40 pp Asia-Pacific, MEA, South America Long-term (≥4 yr)


Demographic Expansion Is the Structural Floor

Obesity prevalence among adults has more than doubled since 1990, and the WHO projects that over half the global adult population will be overweight or obese by 2035 [1]. That is not a marketing trend; it is a demand floor. In the United States alone, CDC NHANES cycles place adult obesity prevalence near 40.3%, meaning extended sizes are mainstream rather than niche [2]. Retailers that treat the Plus Size Clothing Market as a capsule line rather than a core assortment consistently under-index on sell-through.

Fit Technology Cuts the Cost of Serving Larger Sizes

Body-scanning and AI-driven size recommendation have moved from pilot to procurement. Deployment of virtual fitting tools among leading apparel retailers reached roughly 41% by end-2025, and early adopters report return-rate reductions of 12–18% on scanned SKUs [9]. Because reverse logistics can consume 15–25% of an online order's gross margin, that reduction converts directly into category profitability [11].

Athleisure Pulls New Buyers Into the Category

Performance brands have expanded size runs to 4X and beyond, and the sportswear sub-segment is compounding at 8.11% CAGR. panel data shows extended-size activewear units growing roughly 2.3 times faster than straight-size equivalents across 2024–2025 . Compression knits and four-way stretch also forgive grading imprecision, which lowers the technical barrier for brands entering the segment.

Mass Merchants Normalize the Assortment

Discounters and hypermarkets have folded extended sizes into mainline fixtures rather than segregated corners. Assortment audits across 14 major chains found extended-size SKU counts rising 27% between 2023 and 2025 [12]. Placement matters as much as availability — shoppers convert at materially higher rates when sizes sit on the same rack.


Restraints Impact Analysis

Restraint weightings are directional and reflect drag on realized growth rather than subtractions from the published CAGR. Several restraints are cost-side rather than demand-side, which means they compress margin before they compress volume.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Higher fabric consumption and unit COGS −0.70 pp Global Long-term (≥4 yr)
Elevated return and reverse-logistics costs −0.60 pp North America, Europe Short-term (≤2 yr)
Inventory risk from wide size curves −0.50 pp Global Medium-term (2–4 yr)
Constrained in-store floor-space allocation −0.40 pp Europe, Asia-Pacific Medium-term (2–4 yr)
Fragmented sizing standards across regions −0.30 pp Global Long-term (≥4 yr)


Fabric Economics Squeeze the Category

Larger clothing require 18-30% more fabric per unit, and cotton price volatility exacerbates this sensitivity – benchmark lint prices fluctuated over 34% peak-to-trough across 2023-2025 [6]. “Brands rarely price that differential fully into retail, concerned about being accused of a size surcharge. The outcome is a structurally lower gross margin, which constrains promotional flexibility.


Size-Curve Complexity Creates Markdown Exposure

Add four sizes to a style and the SKU count can grow without a commensurate lift in forecast accuracy. Retail audits show that size-curve mismatch accounts for 22% of extended sizes markdowns, not rejection of the style [12]. This burden will remain until demand-planning systems assimilate fit data at the same resolution as color and style.


Physical Retail Space Remains the Bottleneck

European and Asian shop formats have, on average, smaller selling floors than their North American counterparts. Category managers often allocate expanded sizes below their percentage of demand. Space-productivity evaluations of 900 retailers identified allocation gaps of 6-9 percentage points compared to regional demand [13].


Plus Size Clothing Market Opportunities

Native Pattern Blocks as Competitive Moat

Brands that use purpose-built blocks rather than scaling straight-size patterns have much higher repeat-purchase rates. Building that capability requires fit models throughout the complete size run and a specialized technical design staff – an expenditure most mid-market players have deferred. The first person to industrialize gets a huge amount of loyalty in the plus size clothing market.


Emerging-Market Whitespace

India, Indonesia, Brazil, and Saudi Arabia combine rising BMI prevalence with almost no dedicated specialty infrastructure. Domestic e-commerce platforms are the likeliest vehicle, since size-inclusive retail scales faster online than through leased floor space in these geographies. India's apparel sector alone is expanding at high single digits with extended sizes barely represented in organized retail [4].

Fit-Data Monetization and Licensing

Every scan, return reason code, and alteration request is a data asset. Vendors are already licensing anonymized anthropometric datasets to manufacturers pricing at USD 40,000–150,000 per annual seat [9]. Retailers sitting on millions of fit records can convert a cost center into a licensing line.

Rental, Resale, and Subscription Models

Resale platforms report that extended sizes clear inventory faster than average, yet supply remains thin. Subscription boxes tuned to fit-uncertain shoppers reduce the trial risk that suppresses first purchase, and they generate the repeat-fit data described above. Both models extend the addressable Plus Size Clothing Market without new store capital.

Adaptive and Maternity Adjacencies

Adaptive design — magnetic closures, seated-fit trousers, sensory-friendly seams — overlaps heavily with extended sizing in both pattern work and customer base. Regulatory tailwinds from accessibility procurement rules in the EU and US create institutional demand channels that most apparel brands have never touched .


Plus Size Clothing Market Future Outlook

AI Moves From Recommendation to Design

Generative pattern tools trained on anthropometric datasets will compress technical design cycles from weeks to days. estimates generative AI could unlock USD 150–275 billion in operating-profit potential across apparel and fashion value chains . For the Plus Size Clothing Market, the payoff concentrates in grading and fit validation, where iteration cost has historically deterred entry.

Platform Economics Redraw Distribution

Marketplaces are absorbing discovery, and specialty retailers increasingly operate as brands on someone else's rails. Expect commission structures and fulfillment terms — not store leases — to determine category profitability by 2030. Brands with proprietary fit data will negotiate from strength; those without become interchangeable.

Circularity Rules Reshape Cost Structures

Extended Producer Responsibility, digital product passports, and durability requirements phase in across the EU through the early 2030s [14]. Compliance costs land hardest on high-volume, low-quality product. Well-constructed extended sizes, with their higher material content, gain relative advantage under lifecycle-based accounting.

Health Policy Introduces Genuine Uncertainty

Widespread GLP-1 adoption is the one variable that could bend the demand curve. Current prescription volumes reach a small share of the eligible population, and adherence beyond 12 months remains low [23]. A meaningful population-level BMI shift before 2035 is unlikely, but the Plus Size Clothing Market should be modeled with scenario sensitivity around this factor rather than assuming demographic momentum alone.


Regional Market Share Analysis

Region Share of Global Value (2025) Primary Investment Themes
North America 42.41% Specialty retail scale, big-and-tall consolidation, AR fit deployment
Europe 26.35% Circularity regulation, private-label grading, omnichannel returns
Asia-Pacific 21.88% Platform commerce, domestic brand entry, urban BMI shift
South America 5.42% Marketplace expansion, local manufacturing, informal-to-organized shift
Middle East & Africa 3.94% Modest-wear crossover, mall retail, cross-border e-commerce
Total 100.00% —

Regional performance in the Plus Size Clothing Market tracks three variables: BMI prevalence, organized-retail penetration, and e-commerce logistics maturity. Where all three align, category growth outpaces general apparel by 150–250 basis points.


North America

Country Metric Key Driver
US 79.4% share of region Highest adult obesity prevalence and deepest specialty base [2]
Canada USD 15.24 Billion Cross-border e-commerce and department-store assortment resets [12]
Mexico 6.42% CAGR Formalizing retail and rising middle-class apparel spend [4]


North America anchors the Plus Size Clothing Market through infrastructure others lack: dedicated chains, established fit-model programs, and mature reverse-logistics networks. US Census retail-trade data shows clothing store sales recovering to pre-pandemic trend by 2024, with extended sizes outperforming the aggregate [3]. Canada's growth leans heavily on cross-border fulfillment, while Mexico's acceleration reflects a shift from informal markets to organized chains.

Europe

Country Metric Key Driver
Germany 22.1% share of region Largest apparel spend pool and strong catalog heritage [5]
UK USD 18.64 Billion Online-first specialty brands and curve-line expansion [16]
France 14.3% share of region Department-store assortment mandates [5]
Italy USD 9.51 Billion Premium fabric sourcing and tailoring tradition [5]
Spain 5.62% CAGR Fast-fashion size-run extension [17]
Nordic Countries USD 5.28 Billion High per-capita apparel spend and returns tolerance [5]
Russia 5.1% share of region Domestic manufacturing substitution [5]
Rest of Europe 4.87% CAGR Marketplace penetration in CEE [5]


Europe's distinguishing factor is regulation. The EU Strategy for Sustainable and Circular Textiles pushes durability and repairability requirements that favor better-constructed garments over disposable scaling-up [14]. Extended Producer Responsibility schemes, already live in France and phasing in elsewhere, price waste into the cost base — which disadvantages poorly fitting product that gets returned or discarded early.

Asia-Pacific

Country Metric Key Driver
China 34.8% share of region Platform commerce scale and livestream discovery
India 8.24% CAGR Urban BMI shift and organized-retail formalization [4]
Japan USD 12.06 Billion Aging demographics and comfort-led apparel demand
South Korea 8.7% share of region Creator-driven brand launches
ASEAN 7.36% CAGR Mobile marketplace penetration
Rest of Asia-Pacific USD 6.15 Billion Cross-border fulfillment corridors


Asia-Pacific is the fastest-growing bloc in the Plus Size Clothing Market, and its path differs sharply from the West. Rather than specialty chains, growth flows through marketplaces and livestream channels where size filters and user-generated fit reviews substitute for fitting rooms. China's platform ecosystem already carries deeper extended-size assortments than its physical retail suggests, while India's expansion is constrained more by supply-side pattern capability than by demand.

South America

Country Metric Key Driver
Brazil 52.6% share of region Domestic manufacturing base and strong body-positive media
Argentina USD 3.21 Billion Import substitution and local brand growth
Rest of South America 5.14% CAGR Marketplace logistics buildout


Brazil operates a rare combination — local cut-and-sew capacity plus cultural comfort with fuller silhouettes — that lets brands iterate patterns quickly and cheaply. Argentine growth is more price-driven, with currency volatility pushing consumers toward domestic labels. Logistics remain the binding constraint across the rest of the continent.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 26.4% share of region Mall retail expansion under Vision 2030 [21]
UAE USD 2.71 Billion Tourism retail and regional distribution hub status [21]
South Africa 6.18% CAGR Chain-store assortment expansion [22]
Egypt 11.2% share of region Domestic textile manufacturing and price accessibility [22]
Rest of MEA USD 3.44 Billion Cross-border e-commerce inflow [21]


Modest-wear conventions across much of the region translate into naturally looser silhouettes, which lowers the technical fit barrier and lets brands extend size runs with modest pattern rework. Saudi retail development under Vision 2030 has added significant organized floor space, while the UAE functions as the regional distribution and returns-processing hub [21].


Plus Size Clothing Market By Region, 2025-2035

Plus Size Clothing Market Segmentation

By Product Type

Segment Metric Primary Demand Driver
Casual Wear 33.09% share Entry category, forgiving fit tolerance
Formal Wear USD 62.11 Billion Return-to-office and occasion dressing
Sportswear 8.11% CAGR Athleisure crossover and stretch fabrics
Nightwear and More 11.42% share Comfort-led repeat purchase


Casual wear dominates the Plus Size Clothing Market because it demands the least pattern precision — relaxed silhouettes absorb grading error that a tailored blazer would expose. Sportswear grows fastest for the mirror-image reason: performance knits stretch across a wide body range, letting brands cover more customers with fewer patterns while charging premium prices.

By End User

Segment Metric Primary Demand Driver
Men 65.16% share Established big-and-tall retail infrastructure
Women 8.03% CAGR Designer collaborations and creator visibility
Unisex USD 19.72 Billion Streetwear and oversized silhouette adoption


Men's dominance in the Plus Size Clothing Market is a distribution artifact rather than a demand signal — big-and-tall departments have existed for decades, while women's extended sizing was routinely relegated to catalog or online-only. Women's growth now outpaces men's by more than 200 basis points as that structural gap closes.

By Price Range

Segment Metric Primary Demand Driver
Mass 68.52% share Accessibility and assortment breadth
Premium/Luxury 6.83% CAGR Superior fabrics and precise grading


Mass-market retail continues to dominate the volume and revenue share of the plus-size clothing market, driven mostly by the need for basic everyday wear, low-cost pricing and wide demographic appeal. In the meantime, the premium and luxury segment is emerging as the fastest-growing tier of price, thanks to inclusive designer collaborations, appetite for high-end materials and precise technical grading developed for different body forms.


By Distribution Channel

Segment Metric Primary Demand Driver
Offline Retail Stores USD 227.51 Billion Fit confidence and immediate availability
Online Retail Stores 10.34% CAGR AR fitting rooms and social-commerce discovery


Online is the growth engine of the Plus Size Clothing Market, but it carries the return burden that erodes its margin advantage. Physical stores retain a structural role precisely because they eliminate fit uncertainty at the point of purchase — which is why leading players now treat stores as fit-validation nodes feeding data back into online sizing engines.


Competitive Benchmarking

Concentration is low. Market Research Future estimates an HHI in the 250–350 range, with the top five players holding a combined 20–28% of global value. Fragmentation reflects the category's dual structure: global fast-fashion groups compete on price and assortment breadth, while specialty operators compete on fit credibility. Neither approach has produced a durable share leader, which leaves room for niche entrants in adaptive, maternity, and region-specific fit.

Company Est. Revenue Share Range Key Offerings for Plus Size Clothing Market Strategic Positioning
Industria de Diseño Textil (Inditex) ~5–8% Zara and Zara Home extended size runs; Lefties value tier Speed-to-market leader; rapid pattern iteration
H&M Group ~4–7% H&M+ line; COS and Weekday extended fits Volume scale with sustainability positioning
Shein ~3–6% Curve and Plus verticals across categories Ultra-fast test-and-repeat; price leadership
Fast Retailing (Uniqlo) ~3–6% LifeWear extended sizing; AIRism and HEATTECH basics Fabric-technology differentiation
Gap Inc. (Old Navy) ~3–5% BODEQUALITY in-store integrated sizing Assortment normalization pioneer
NIKE, Inc. ~2–5% Extended-size training, running, and lifestyle apparel Performance credibility and athlete marketing
adidas AG ~2–4% Extended-size performance and originals lines Sport-lifestyle crossover
Torrid Holdings ~2–4% Dedicated women's specialty apparel and intimates Pure-play fit specialist with loyalty base
FullBeauty Brands (Lane Bryant, Woman Within) ~2–3% Multi-banner catalog and digital portfolio Direct-to-consumer heritage; deep size runs
ASOS plc ~1–3% ASOS Curve and Plus own-label ranges Digital-native breadth and rapid trend response
Marks & Spencer Group ~1–2% Extended-size womenswear and menswear Fit-consistency reputation in UK market
City Chic Collective ~1–2% Fashion-forward specialty womenswear Design-led niche positioning


Recent News & Developments


  • September 3, 2026: Q2 FY2026 results — net income of $5.2 million, aided by an $11.1 million IEEPA tariff refund; CEO Lisa Harper noted July marked "a clear inflection point" with improving sales trends, and the company raised its FY2026 guidance.
  • August 24, 2026: Released FY26 audited results — underlying EBITDA nearly doubled to $12.3 million from $6.4 million the prior year, global revenue dipped 3.1% to $130.5 million, and the company ended the year with $5.2 million cash and no drawn debt.

    July 13, 2026: Reported USA revenue down 28.1% (excluding a closed wholesale business) due to a deliberate tariff-driven inventory pullback, while ANZ sales grew 7.6%.

  • June 2, 2026: Q1 FY2026 results — net sales down 7.6% YoY to $245.8 million; the company closed 169 stores over the prior year as part of a "retail store optimization" strategy shifting toward e-commerce.
  • March 19, 2026: Reported Q4/full fiscal 2025 results — $1.0 billion in net sales for the year, but a Q4 net loss of $8.1 million.
  • May 25, 2026 — Ankura Consulting Group published an analysis ("Sizing Is the New Fault Line") noting U.S. adult obesity had declined from a peak of 39.9% in 2022 to 37% in 2025, and that typical GLP-1-driven weight loss of 10–20% of body weight translates to roughly one to five clothing sizes down. The report also flagged that a leading men's plus-size retailer had cited GLP-1 usage among roughly a quarter of its customer base as a factor in a Q4 2025 sales decline and net loss.
  • April 2026 — CNN Business reported that extended sizes for women's apparel on Target's website fell 37% from March 2025 to March 2026, with a 30% drop in just the prior six months, according to retail intelligence firm EDITED. Old Navy's plus-size options fell 12% over the same comparison period. A Guggenheim Partners retail analyst noted that weight-loss medications are having significant effects across retail broadly, which could extend to clothing categories.


Plus Size Clothing Market Report Scope

Parameter Detail
Market Scope Global manufacture and retail of apparel in extended sizes across formal wear, casual wear, sportswear, nightwear and other categories, sold through online and offline channels
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.97% (2026–2035)
Market Size Checkpoints USD 334.18 Billion (2025); USD 336.36 Billion (2026); USD 424.17 Billion (2030); USD 566.82 Billion (2035)
Fastest Growing Segments Sportswear (product type); Women (end user); Premium/Luxury (price range); Online Retail Stores (distribution channel)
Companies Profiled Inditex, H&M Group, Shein, Fast Retailing, Gap Inc., NIKE, adidas, Torrid Holdings, FullBeauty Brands, ASOS plc, Marks & Spencer, City Chic Collective
Valuation Currency USD Billion, at manufacturer selling price

FAQs

What due-diligence red flags should investors screen for when evaluating Plus Size Clothing Market acquisition targets?
Check whether patterns are drafted natively or scaled from straight sizes — scaled catalogs carry hidden return liabilities. Also examine size-curve sell-through by SKU rather than aggregate margin, since blended figures hide markdown concentration in the largest sizes [11].
How should a buyer compare 3D body-scanning vendors against traditional fit-model programs?
Scanning wins on sample size and speed; live fit models still win on drape, movement, and fabric behavior. Most mature programs in the Plus Size Clothing Market run both, using scans for grading rules and models for final approval [9].
Which contractual terms matter most when sourcing extended sizes from Tier-2 suppliers?
Negotiate fabric-consumption tolerances and minimum order quantities per size, not per style — blanket MOQs force overbuying at curve extremes. Lock tech-pack ownership so pattern blocks stay with you if you switch vendors [25].
Does adaptive apparel overlap materially with the Plus Size Clothing Market?
Yes, in pattern engineering and customer overlap, though procurement channels differ. Adaptive lines often reach buyers through healthcare and institutional purchasing rather than mainstream retail, which requires separate compliance documentation .
What labelling or advertising regulations apply to size claims in the Plus Size Clothing Market?
No global standard governs size labelling, so claims are policed under general consumer-protection and misleading-advertising rules. EU digital product passport requirements will add traceability obligations for materials rather than sizing itself [14].
How do resale and rental platforms affect category economics?
Resale extends garment life and improves lifecycle cost per wear, which supports higher initial price points. Supply of extended sizes on secondary platforms remains scarce, so listings typically clear faster than straight-size equivalents .
What integration challenges arise when adding extended sizes to an existing PLM system?
Legacy PLM schemas often hard-code size ranges into style records, breaking when curves widen. Plan for master-data remapping and downstream ERP allocation logic before the first tech pack is written .    
Author
Author Author Profile Varsha More LinkedIn Senior Research Analyst
Experienced business professional with a demonstrated history of working in the CFnB industry. Skilled in market research, and market estimation. Strong professional with a Masters focused in marketing management.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of retail industry databases, fashion trade publications, consumer behavior studies, and authoritative economic and demographic sources. Key sources included the US Census Bureau, Bureau of Labor Statistics (BLS), National Retail Federation (NRF), US International Trade Commission (USITC), Eurostat, Office for National Statistics (UK), Statistics Canada, Australian Bureau of Statistics, National Bureau of Statistics of China, Ministry of Economy, Trade and Industry (Japan), World Bank Open Data, International Labour Organization (ILO), World Health Organization (WHO) Global Health Observatory (for obesity/demographic data), Organisation for Economic Co-operation and Development (OECD), MRFR Global Fashion Index, Business of Fashion (BoF), World Trade Organization (WTO) trade statistics, US Environmental Protection Agency (EPA) (for sustainability regulations), European Environment Agency (EEA), and national textile/apparel association reports from key markets including American Apparel & Footwear Association (AAFA), British Fashion Council, China National Textile and Apparel Council (CNTAC), and Japan Fashion Week Organization. These sources were used to collect apparel retail statistics, consumer spending data, body measurement demographics, import/export trade data, e-commerce growth metrics, and sustainability regulatory frameworks for casual wear, formal wear, sportswear, and other clothing categories across economy, mid-range, and premium price points.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, Chief Merchandising Officers, VPs of Product Development, heads of sustainability, supply chain directors, and e-commerce directors from plus-size clothing manufacturers, fast fashion retailers, niche brands, and OEMs were among the supply-side sources. Demand-side sources included visual merchandising directors, retail buyers from department stores and specialty boutiques, procurement leaders from multi-brand retailers, plus-size fashion influencers, and participants in consumer focus groups from various demographic groups. Primary research acquired information on issues with sizing uniformity, digital transformation tactics, omnichannel retail adoption trends, and sustainability compliance needs. It also confirmed product pipeline timings and validated market segmentation across gender and age groups.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (25%), Others (35%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and consumer expenditure analysis. The methodology included:

Identification of 50+ key manufacturers and retailers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across casual wear, formal wear, sportswear, and other categories segmented by gender (male, female) and age groups (below 15, 16-59, 60 & above)

Price tier analysis across economy, mid-range, and premium segments

Analysis of reported and modeled annual revenues specific to plus-size clothing portfolios

Coverage of retailers and brands representing 72-78% of global market share in 2024

Extrapolation using bottom-up (consumer spending × penetration rates by country) and top-down (retailer revenue validation) approaches to derive segment-specific valuations, incorporating e-commerce growth multipliers and inflation-adjusted pricing data

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















