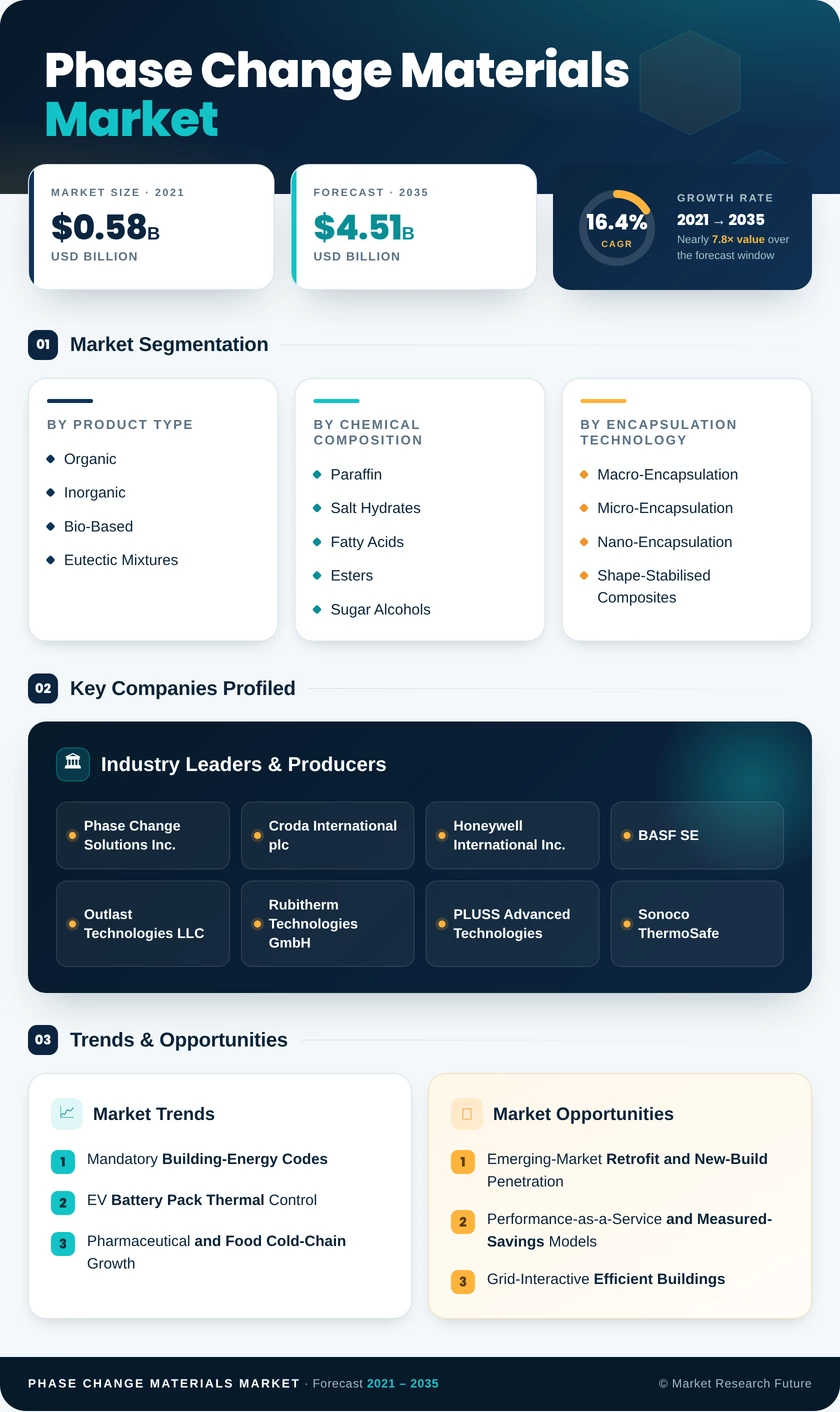
Phase Change Materials Market (2026 - 2035)

ID: MRFR/CnM/6810-CR 111 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Phase Change Materials Market Research Report Information By Product Type (Organic, Inorganic, Bio-Based, and Eutectic Mixtures), By Chemical Composition (Paraffin, Salt Hydrates, Fatty Acids and Esters, Sugar Alcohols, and Others), By Encapsulation Technology (Macro-Encapsulation, Micro-Encapsulation, Nano-Encapsulation, and Shape-Stabilised Composites), and By End-User Industry (Building and Construction, Cold Chain and Packaging, Automotive and Transportation, Electronics and Data Centres, Textiles and Consumer Goods, and Industrial and Others) – Forecast Till 2035
Phase Change Materials Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.4%
2025 Market SizeUSD 0.98 Billion
2035 Market SizeUSD 4.51 Billion
Key Players
Phase Change Solutions Inc.
Croda International plc
Honeywell International Inc.
BASF SE
Outlast Technologies LLC
Rubitherm Technologies GmbH
Opportunities
  • Emerging-Market Retrofit and New-Build Penetration
  • Performance-as-a-Service and Measured-Savings Models
  • Grid-Interactive Efficient Buildings
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Global Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Drivers Analysis | |
    1. 4.1 Mandatory Building-Energy Codes | |
    2. 4.2 EV Battery Pack Thermal Control | |
    3. 4.3 Pharmaceutical and Food Cold-Chain Growth | |
    4. 4.4 Data-Centre Cooling Load Escalation | |
    5. 4.5 Bio-Based Formulation Commercialisation | |
    6. 4.6 Salt-Hydrate Conductivity Breakthroughs | |
    7. 4.7 Utility Peak-Shaving and Demand-Response Incentives | |
  5. 5 Market Restraints Analysis | |
    1. 5.1 High Upfront Cost Versus Sensible-Heat Alternatives | |
    2. 5.2 Supercooling and Phase Separation in Inorganics | |
    3. 5.3 Flammability Classification and Code Approval | |
    4. 5.4 Encapsulation Manufacturing Scale Limits | |
    5. 5.5 Absent Standardised Performance Testing | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Emerging-Market Retrofit and New-Build Penetration | |
    2. 6.2 Performance-as-a-Service and Measured-Savings Models | |
    3. 6.3 Grid-Interactive Efficient Buildings | |
    4. 6.4 Agricultural-Residue Feedstock Integration | |
    5. 6.5 High-Value Pharmaceutical Shipping Fleets | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Sensor-Instrumented Materials and Predictive Dispatch | |
    2. 8.2 Platform Economics and Aggregated Thermal Capacity | |
    3. 8.3 Electrification Supercycle and Battery-Adjacent Demand | |
    4. 8.4 Embodied Carbon Disclosure and Bio-Based Substitution | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Product Type | | |
      1. 9.1.1 Organic | | |
      2. 9.1.2 Inorganic | | |
      3. 9.1.3 Bio-Based | | |
      4. 9.1.4 Eutectic Mixtures | |
    2. 9.2 By Chemical Composition | | |
      1. 9.2.1 Paraffin | | |
      2. 9.2.2 Salt Hydrates | | |
      3. 9.2.3 Fatty Acids and Esters | | |
      4. 9.2.4 Sugar Alcohols | | |
      5. 9.2.5 Others | |
    3. 9.3 By Encapsulation Technology | | |
      1. 9.3.1 Macro-Encapsulation | | |
      2. 9.3.2 Micro-Encapsulation | | |
      3. 9.3.3 Nano-Encapsulation | | |
      4. 9.3.4 Shape-Stabilised Composites | |
    4. 9.4 By End-User Industry | | |
      1. 9.4.1 Building and Construction | | |
      2. 9.4.2 Cold Chain and Packaging | | |
      3. 9.4.3 Automotive and Transportation | | |
      4. 9.4.4 Electronics and Data Centres | | |
      5. 9.4.5 Textiles and Consumer Goods | | |
      6. 9.4.6 Industrial and Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Phase Change Solutions Inc. | | |
      2. 10.3.2 Croda International plc | | |
      3. 10.3.3 Honeywell International Inc. | | |
      4. 10.3.4 BASF SE | | |
      5. 10.3.5 Outlast Technologies LLC | | |
      6. 10.3.6 Rubitherm Technologies GmbH | | |
      7. 10.3.7 PLUSS Advanced Technologies | | |
      8. 10.3.8 Sonoco ThermoSafe | | |
      9. 10.3.9 Cryopak (TCP Reliable Inc.) | | |
      10. 10.3.10 Microtek Laboratories Inc. | | |
      11. 10.3.11 Climator Sweden AB | | |
      12. 10.3.12 Henkel AG & Co. KGaA | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Phase Change Material Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Phase Change Material Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Estimated Contribution to CAGR, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Estimated Drag on CAGR, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Product Type, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Market Size, by Chemical Composition, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Market Size, by Encapsulation Technology, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  23. TABLE 9 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  24. TABLE 10 Regional Summary – Share, Value and Investment Themes, 2025 | |
  25. TABLE 11 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  26. TABLE 12 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  29. TABLE 15 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Market Size, by Product Type, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Market Size, by Chemical Composition, 2021–2035 (USD Billion) | |
  32. TABLE 18 North America Market Size, by Encapsulation Technology, 2021–2035 (USD Billion) | |
  33. TABLE 19 North America Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Market Size, by Product Type, 2021–2035 (USD Billion) | |
  35. TABLE 21 Europe Market Size, by Chemical Composition, 2021–2035 (USD Billion) | |
  36. TABLE 22 Europe Market Size, by Encapsulation Technology, 2021–2035 (USD Billion) | |
  37. TABLE 23 Europe Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Market Size, by Product Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 Asia-Pacific Market Size, by Chemical Composition, 2021–2035 (USD Billion) | |
  40. TABLE 26 Asia-Pacific Market Size, by Encapsulation Technology, 2021–2035 (USD Billion) | |
  41. TABLE 27 Asia-Pacific Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  42. TABLE 28 South America Market Size, by Product Type, 2021–2035 (USD Billion) | |
  43. TABLE 29 South America Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  44. TABLE 30 Middle East & Africa Market Size, by Product Type, 2021–2035 (USD Billion) | |
  45. TABLE 31 Middle East & Africa Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  46. TABLE 32 US Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  47. TABLE 33 Germany Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  48. TABLE 34 China Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  49. TABLE 35 India Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  50. TABLE 36 Brazil Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  51. TABLE 37 Saudi Arabia Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  52. TABLE 38 Competitive Benchmarking Matrix – Global Phase Change Material Market, 2026 | |
  53. TABLE 39 Company Profiles – Key Players, Global Phase Change Material Market | |
  54. TABLE 40 Recent Developments & Strategic Announcements, 2023–2025 | |
  55. TABLE 41 Report Scope & Methodology Summary | |
  56. TABLE 42 Detailed Sources and Citations | | LIST OF FIGURES | |
  57. FIGURE 1 Global Phase Change Material Market – Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  58. FIGURE 2 Industry Value Chain Analysis – Feedstock to Installed System | |
  59. FIGURE 3 Porter's Five Forces Analysis | |
  60. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  61. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  62. FIGURE 6 Driver Impact Contribution to CAGR, 2026–2035 | |
  63. FIGURE 7 Restraint Impact Drag on CAGR, 2026–2035 | |
  64. FIGURE 8 Market Share by Product Type, 2025 vs 2035 (%) | |
  65. FIGURE 9 Market Share by Chemical Composition, 2025 (%) | |
  66. FIGURE 10 Market Share by Encapsulation Technology, 2025 vs 2035 (%) | |
  67. FIGURE 11 Market Share by End-User Industry, 2025 (%) | |
  68. FIGURE 12 Regional Revenue Share, 2025 (%) | |
  69. FIGURE 13 Regional Revenue Share, 2035 (%) | |
  70. FIGURE 14 Regional CAGR Comparison, 2026–2035 (%) | |
  71. FIGURE 15 Country-Level Share within Europe, 2025 (%) | |
  72. FIGURE 16 Country-Level Share within Asia-Pacific, 2025 (%) | |
  73. FIGURE 17 Competitive Landscape – Estimated Revenue Share Ranges, 2026 | |
  74. FIGURE 18 Competitive Positioning Matrix – Innovation Intensity vs Vertical Integration | |
  75. FIGURE 19 Encapsulation Cost Curve Outlook, 2026–2035 | |
  76. FIGURE 20 Bio-Based Substitution Trajectory, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeOrganic; Inorganic; Bio-Based; Eutectic MixturesOrganicBio-Based
By Chemical CompositionParaffin; Salt Hydrates; Fatty Acids and Esters; Sugar Alcohols; OthersParaffinSalt Hydrates
By Encapsulation TechnologyMacro-Encapsulation; Micro-Encapsulation; Nano-Encapsulation; Shape-Stabilised CompositesMacro-EncapsulationMicro-Encapsulation
By End-User IndustryBuilding and Construction; Cold Chain and Packaging; Automotive and Transportation; Electronics and Data Centres; Textiles and Consumer Goods; Industrial and OthersBuilding and ConstructionAutomotive and Transportation
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaEuropeAsia-Pacific


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
OrganicStable cycling and established code listings keep it the default specification for construction
InorganicConductivity and nucleation improvements are reopening applications previously lost on reliability grounds
Bio-BasedFire classification results and procurement preferences are converting sustainability claims into bid advantage
Eutectic MixturesCustom transition windows serve narrow pharmaceutical and electronics requirements at premium pricing


Product-type competition is shifting from enthalpy claims toward verified cycle life. Organic grades will hold leadership through 2035, but bio-based alternatives close the gap fastest as European embodied-carbon rules make petrochemical origin a scoring penalty on public tenders.

By Chemical Composition

Sub-SegmentKey Trend
ParaffinVolume anchor with gradual share erosion as substitutes achieve equivalent code approvals
Salt HydratesGraphite-matrix and nucleating-agent advances lift conductivity above commercially useful thresholds
Fatty Acids and EstersBio-content credentials with lower corrosivity than inorganic alternatives
Sugar AlcoholsHigh-temperature industrial process buffering above 100°C
OthersMetallic and polymeric formulations for specialist high-conductivity duties


Composition choices increasingly follow supply security rather than performance alone. Asia-Pacific producers securing mineral off-take agreements for high-purity crystal have gained a structural cost advantage that European converters are attempting to offset through bio-based feedstock contracts.

By Encapsulation Technology

Sub-SegmentKey Trend
Macro-EncapsulationLowest cost per kilogram; dominates construction panels, pouches, and cold-storage modules
Micro-EncapsulationEnables direct integration into gypsum, textiles, and coatings, removing separate installation labour
Nano-EncapsulationPrecision electronics and instrument cooling at premium margins and low volume
Shape-Stabilised CompositesLeak-free forms that avoid discrete containment costs entirely


Containment technology now determines installed economics more than base chemistry does. Micro-encapsulation grows fastest because it eliminates a labour line item, though limited merchant line capacity worldwide continues to constrain how quickly that growth can be served.

By End-User Industry

Sub-SegmentKey Trend
Building and ConstructionEnergy codes and peak-load mandates sustain the largest revenue base through 2035
Cold Chain and PackagingReusable qualified shipper fleets shift buyers from consumables to leased assets
Automotive and TransportationBattery pack temperature uniformity requirements drive the fastest end-user growth
Electronics and Data CentresCompute density and cooling redundancy support premium pricing for validated products
Textiles and Consumer GoodsLicensed thermoregulating media in apparel and bedding
Industrial and OthersWaste heat recovery and process buffering in continuous manufacturing


End-user mix is diversifying away from construction dependence. Cold chain delivers the shortest replacement cycles and highest revenue quality, while automotive contributes the steepest growth curve as pack qualification programmes convert into series production volumes across Asia-Pacific and Europe.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.