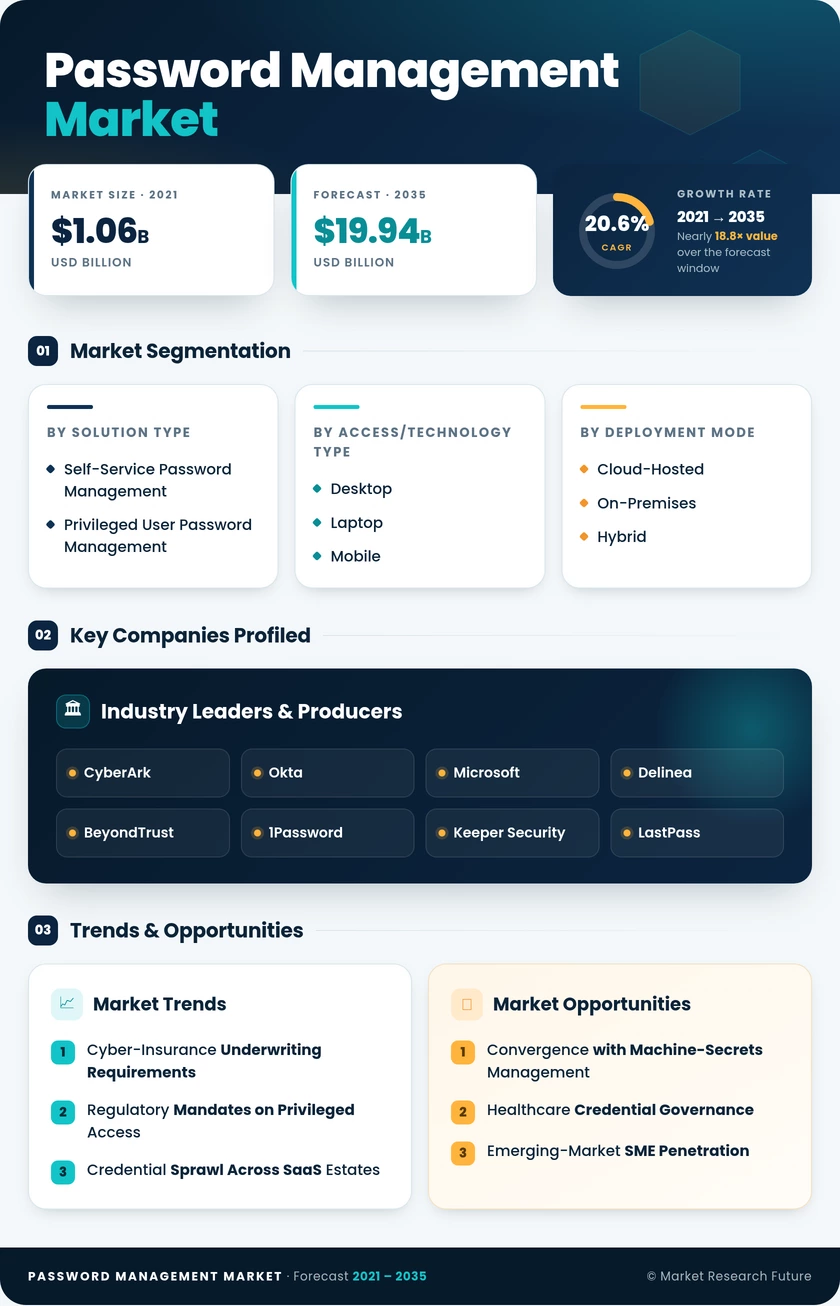
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Solution Type | Self-Service Password Management; Privileged User Password Management | Self-Service Password Management (43.6% share, 2025) | Privileged User Password Management (21.9% CAGR) |
| By Access/Technology Type | Desktop and Laptop; Mobile | Desktop and Laptop (35.8% share, 2025) | Mobile (22.2% CAGR) |
| By Deployment Mode | Cloud-Hosted; On-Premises; Hybrid | Cloud-Hosted (60.4% share, 2025) | Hybrid (22.0% CAGR) |
| By Enterprise Size | Large Enterprises; Small and Medium Enterprises | Large Enterprises (USD 1.53 Billion, 2025) | Small and Medium Enterprises (22.4% CAGR) |
| By End-User Vertical | Banking, Financial Services and Insurance (BFSI); Healthcare and Life Sciences; Other Verticals | Banking, Financial Services and Insurance (BFSI) (27.2% share, 2025) | Healthcare and Life Sciences (23.8% CAGR) |
Market Segmentation Overview
By Solution Type
| Sub-Segment | Key Trend |
| Self-Service Password Management | Helpdesk ticket deflection drives sustained enterprise renewals |
| Privileged User Password Management | Rotation, logging, and separation-of-duties mandates accelerate uptake |
Self-Service Password Management leads on installed base because reset automation produces a defensible cost case in any organization above a few hundred employees. Privileged User Password Management grows fastest, since supervisory rules in banking and healthcare demand credential rotation and session logging that self-service tools were never designed to deliver. Consumer migration toward platform-native credential storage pressures the self-service tier, while administrative accounts remain structurally out of reach for those alternatives.
By Access/Technology Type
| Sub-Segment | Key Trend |
| Desktop and Laptop | Full-featured clients remain essential for engineering and analyst workflows |
| Mobile | Biometric unlock and device programs drive fastest adoption |
Desktop and Laptop access retains the largest share because terminal integration, browser extension depth, and administrative consoles all assume a full desktop client. Mobile grows fastest as device programs put biometric vaults on every employee handset and network latency stops constraining real-time sync. The competitive complication is that platform credential stores ship free on those same handsets, so independent vendors must justify their presence through cross-platform consistency and administrative reporting that native stores do not provide.
By Deployment Mode
| Sub-Segment | Key Trend |
| Cloud-Hosted | Managed updates and elastic provisioning sustain majority share |
| On-Premises | Isolation requirements preserve defense and government demand |
| Hybrid | Split-custody architectures answer residency mandates |
Cloud-Hosted delivery holds the clear majority because it removes patching, capacity planning, and disaster recovery from buyer scope. Hybrid grows fastest, driven by European and Gulf residency rules that require privileged secrets to remain in-country while workforce credentials continue flowing to managed vaults. On-Premises does not disappear — defense and intelligence buyers with air-gapped requirements sustain a small, long-contract base that vendors service at premium pricing.
By Enterprise Size
| Sub-Segment | Key Trend |
| Large Enterprises | Audit scope and privileged estate complexity anchor absolute spending |
| Small and Medium Enterprises | Subscription pricing and self-service onboarding unlock volume |
Large Enterprises generate the majority of revenue because privileged account counts, integration surface, and audit obligations all scale with organizational size, producing six-figure annual contracts. Small and Medium Enterprises grow fastest as per-seat pricing falls and onboarding removes the professional-services barrier entirely. Insurance underwriting is the decisive accelerant at the smaller end, extending control requirements to firms that previously treated credential hygiene as an informal practice.
By End-User Vertical
| Sub-Segment | Key Trend |
| Banking, Financial Services and Insurance (BFSI) | Supervisory access-control evidence requirements sustain leadership |
| Healthcare and Life Sciences | EHR and medical-device credential sprawl drives fastest growth |
| Other Verticals | Ransomware containment motivates retail, government, and education adoption |
Banking, Financial Services and Insurance (BFSI) leads because supervisory frameworks impose the most explicit, testable access-control documentation duties of any sector, and non-compliance carries direct financial penalty. Healthcare and Life Sciences grows fastest as electronic health record ecosystems generate API keys, device accounts, and clinician shared logins beyond legacy policy reach. Other Verticals — retail, government, manufacturing, education — buy primarily as ransomware defense rather than compliance response, producing shorter sales cycles but smaller average deal sizes.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA