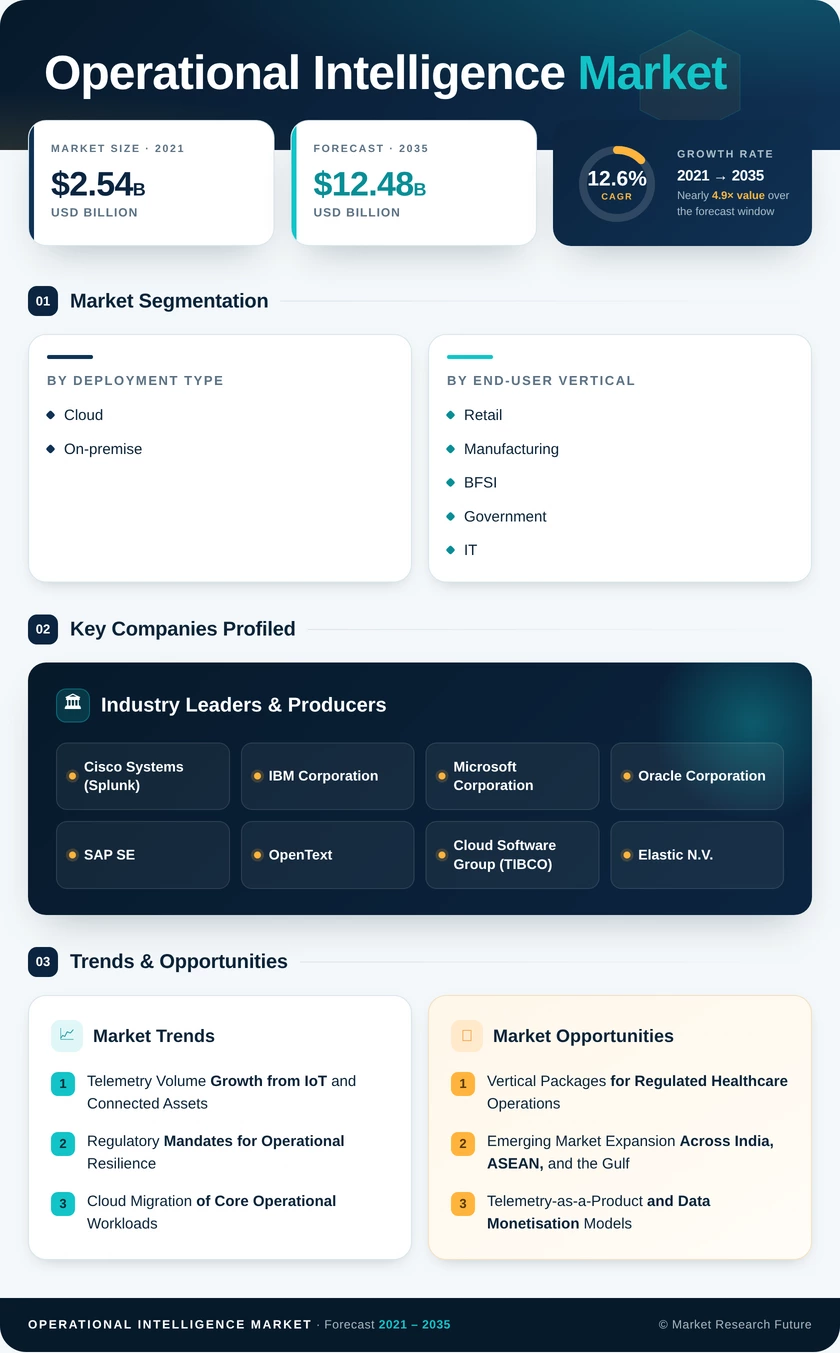
Operational Intelligence Market (2026 - 2035)

ID: MRFR/ICT/4417-HCR 100 Pages Nirmit Biswas Last Updated: September 08, 2026
Operational Intelligence Market Research Report Information By Type (Enterprise Manufacturing, Enterprise Operational Intelligence Software, IT Service Intelligence, Enterprise Security), by Application (Smart Meter Analysis), by Vertical – Forecast till 2035
Operational Intelligence Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.6%
2025 Market SizeUSD 3.81 Billion
2035 Market SizeUSD 12.48 Billion
Key Players
Cisco Systems
IBM Corporation
Microsoft Corporation
Oracle Corporation
SAP SE
OpenText
Opportunities
  • Vertical Packages for Regulated Healthcare Operations
  • Emerging Market Expansion Across India, ASEAN, and the Gulf
  • Telemetry-as-a-Product and Data Monetisation Models
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Deployment Type | |
    2. 2.2 By End-user Vertical | |
    3. 2.3 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Telemetry Volume Growth from IoT and Connected Assets | |
    2. 4.2 Regulatory Mandates for Operational Resilience | |
    3. 4.3 Cloud Migration of Core Operational Workloads | |
    4. 4.4 Convergence of Security and Operations Telemetry | |
    5. 4.5 Industry
    6. 4.0 Plant-Floor Digitalisation | |
    7. 4.6 Generative AI Copilots Inside Operations Tooling | |
    8. 4.7 Downtime Cost Pressure in Asset-Heavy Sectors | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Shortage of Skilled Data Engineering Talent | |
    2. 5.2 High Total Cost of Ownership and Implementation Complexity | |
    3. 5.3 Legacy System Fragmentation and Integration Burden | |
    4. 5.4 Data Sovereignty and Privacy Restrictions | |
    5. 5.5 Ingest-Based Pricing Escalation and Buyer Backlash | |
  6. 6 Opportunities | |
    1. 6.1 Vertical Packages for Regulated Healthcare Operations | |
    2. 6.2 Emerging Market Expansion Across India, ASEAN, and the Gulf | |
    3. 6.3 Telemetry-as-a-Product and Data Monetisation Models | |
    4. 6.4 Edge-Resident Deployment for Manufacturing and Energy | |
    5. 6.5 Managed Services for the Underserved Mid-Market | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 From Detection to Autonomous Remediation | |
    2. 8.2 Platform Economics and the Pricing Reset | |
    3. 8.3 The Edge-Cloud Continuum | |
    4. 8.4 Operations Data as Sustainability Evidence | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Deployment Type | | |
      1. 9.1.1 Cloud | | |
      2. 9.1.2 On-premise | |
    2. 9.2 By End-user Vertical | | |
      1. 9.2.1 Retail | | |
      2. 9.2.2 Manufacturing | | |
      3. 9.2.3 BFSI | | |
      4. 9.2.4 Government | | |
      5. 9.2.5 IT and Telecommunication | | |
      6. 9.2.6 Military and Defense | | |
      7. 9.2.7 Transportation and Logistics | | |
      8. 9.2.8 Healthcare | | |
      9. 9.2.9 Energy and Power | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Operational Intelligence Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Operational Intelligence Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region (USD Billion), 2021–2035 | |
  20. TABLE 6 North America Market Size, by Country (USD Billion), 2021–2035 | |
  21. TABLE 7 Europe Market Size, by Country (USD Billion), 2021–2035 | |
  22. TABLE 8 Asia-Pacific Market Size, by Country (USD Billion), 2021–2035 | |
  23. TABLE 9 South America Market Size, by Country (USD Billion), 2021–2035 | |
  24. TABLE 10 Middle East & Africa Market Size, by Country (USD Billion), 2021–2035 | |
  25. TABLE 11 Global Market Size, by Deployment Type (USD Billion), 2021–2035 | |
  26. TABLE 12 Global Market Size, by End-user Vertical (USD Billion), 2021–2035 | |
  27. TABLE 13 North America Market Size, by Deployment Type (USD Billion), 2021–2035 | |
  28. TABLE 14 North America Market Size, by End-user Vertical (USD Billion), 2021–2035 | |
  29. TABLE 15 Europe Market Size, by Deployment Type (USD Billion), 2021–2035 | |
  30. TABLE 16 Europe Market Size, by End-user Vertical (USD Billion), 2021–2035 | |
  31. TABLE 17 Asia-Pacific Market Size, by Deployment Type (USD Billion), 2021–2035 | |
  32. TABLE 18 Asia-Pacific Market Size, by End-user Vertical (USD Billion), 2021–2035 | |
  33. TABLE 19 South America Market Size, by Deployment Type (USD Billion), 2021–2035 | |
  34. TABLE 20 South America Market Size, by End-user Vertical (USD Billion), 2021–2035 | |
  35. TABLE 21 Middle East & Africa Market Size, by Deployment Type (USD Billion), 2021–2035 | |
  36. TABLE 22 Middle East & Africa Market Size, by End-user Vertical (USD Billion), 2021–2035 | |
  37. TABLE 23 Competitive Benchmarking Matrix, 2026 | |
  38. TABLE 24 Company Profiles – Key Players | |
  39. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 | |
  40. TABLE 26 Report Scope & Methodology Summary | |
  41. TABLE 27 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  42. FIGURE 1 Market Dynamics – Drivers, Restraints, and Opportunities Overview | |
  43. FIGURE 2 Industry Value Chain Analysis | |
  44. FIGURE 3 Porter's Five Forces Analysis | |
  45. FIGURE 4 Global Market Size Trend and Forecast (USD Billion), 2021–2035 | |
  46. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  47. FIGURE 6 Market Share by Deployment Type, 2025 vs 2035 | |
  48. FIGURE 7 Market Share by End-user Vertical, 2025 | |
  49. FIGURE 8 End-user Vertical Growth Rate Comparison, 2026–2035 | |
  50. FIGURE 9 Regional Market Share Distribution, 2025 | |
  51. FIGURE 10 Regional Market Share Distribution, 2035 | |
  52. FIGURE 11 Regional CAGR Comparison, 2026–2035 | |
  53. FIGURE 12 Country-Level Contribution within Asia-Pacific, 2025 | |
  54. FIGURE 13 Competitive Landscape – Estimated Vendor Share Ranges, 2026 | |
  55. FIGURE 14 Vendor Positioning Matrix – Capability vs Deployment Breadth

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Deployment TypeCloud; On-premiseCloud (61.5% share, 2025)Cloud (14.1% CAGR, 2026–2035)
By End-user VerticalRetail; Manufacturing; BFSI; Government; IT and Telecommunication; Military and Defense; Transportation and Logistics; Healthcare; Energy and PowerBFSI (19.6% share, 2025)Healthcare (15.6% CAGR, 2026–2035)


Market Segmentation Overview

By Deployment Type

Sub-SegmentKey Trend
CloudCapacity-based commercial models replace perpetual licensing; elastic ingest absorbs burst telemetry without provisioning ahead of peak
On-premiseSustained by residency mandates, defence accreditation, and sub-50-millisecond control loops that cannot tolerate cloud round trips


Cloud carries 61.5% of 2025 revenue and simultaneously grows fastest at 14.1%, a combination that is unusual and reflects how poorly fixed hardware matches irregular telemetry volumes. On-premise does not disappear; it stabilises around workloads where sovereign hosting rules or physical latency budgets rule out remote processing, which is why defence, grid operations, and semiconductor fabs keep it viable. Most large enterprises land on hybrid topologies, running scoring nodes locally while pushing retention and long-horizon modelling to cloud capacity. Vendors without a credible local runtime lose industrial tenders regardless of cloud-side capability.

By End-user Vertical

Sub-SegmentKey Trend
RetailFulfilment orchestration and checkout availability monitoring across omnichannel estates
ManufacturingLine-level yield scoring and predictive maintenance displacing shift-end review
BFSIContinuous ICT monitoring mandated by resilience regulation and payment uptime obligations
GovernmentCitizen service availability tracking and public infrastructure monitoring programmes
IT and TelecommunicationNetwork service assurance and automated fault remediation at carrier scale
Military and DefenseMission systems monitoring under accredited on-premise deployment
Transportation and LogisticsFleet telemetry, dwell-time reduction, and port throughput optimisation
HealthcareClinical asset tracking, patient flow management, and device fleet monitoring
Energy and PowerGrid stability monitoring, renewable dispatch, and asset condition analysis


BFSI leads this dimension at 19.6% of 2025 revenue because supervisory rules turned continuous monitoring into evidence a regulator can demand, not a productivity choice a CIO can defer. Manufacturing follows at USD 0.68 billion, where line-level scoring produces yield and scrap improvements that pay back within a single fiscal year. Healthcare grows fastest at 15.6%, starting from the lowest instrumentation base of any major vertical and now attracting packaged offerings built around clinical schemas rather than generic infrastructure metrics. Energy and Power remains the smallest contributor by value but shows the most concentrated deal sizes, since grid operators buy at national scale.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.