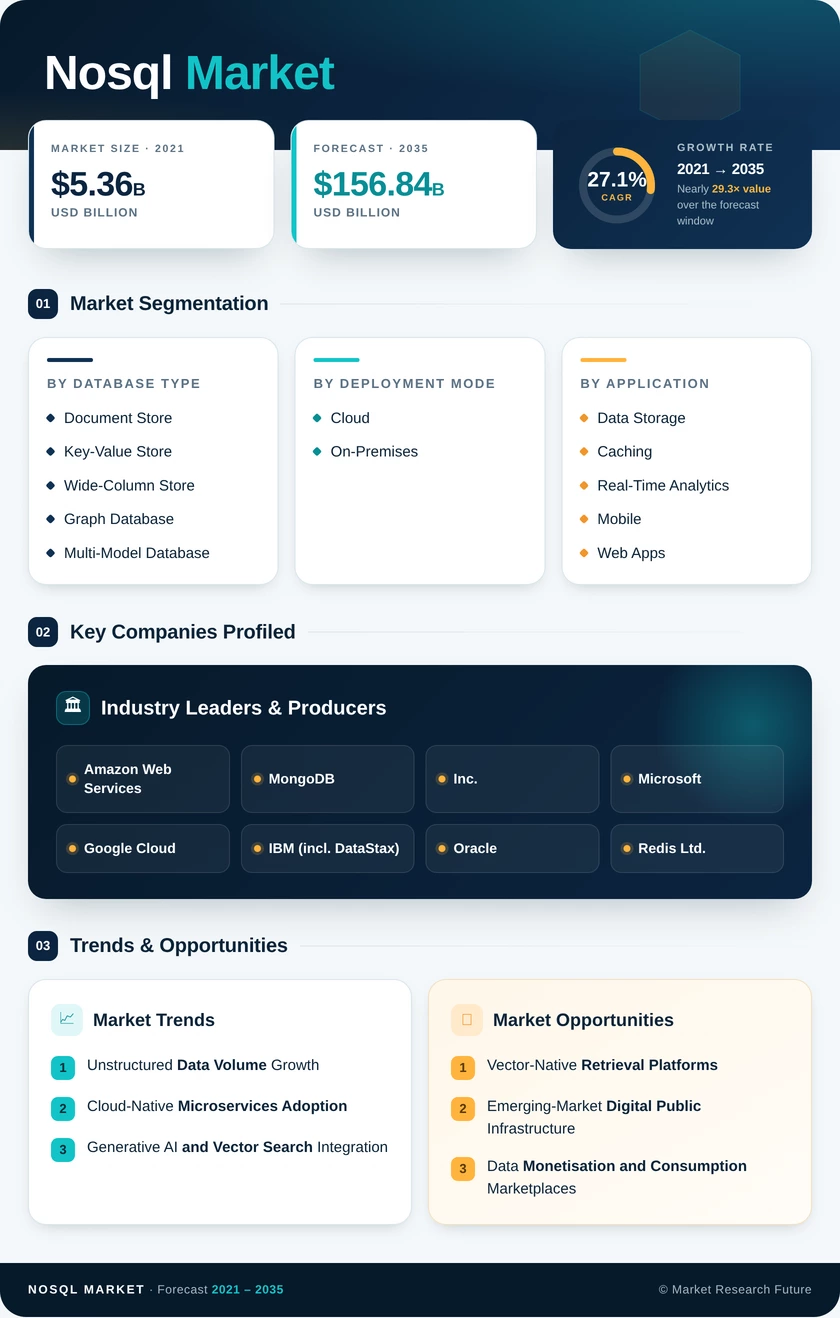
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Database Type | Document Store; Key-Value Store; Wide-Column Store; Graph Database; Multi-Model Database; In-Memory NoSQL Database | Key-Value Store (35.2% share, 2025) | Graph Database (27.0% CAGR, 2026–2035) |
| By Deployment Mode | Cloud; On-Premises | Cloud (60.7% share, 2025) | Cloud (fastest-expanding mode) |
| By Application | Data Storage and Caching; Real-Time Analytics; Mobile and Web Apps; IoT and Sensor Data Management; AI and ML Workloads; Content Management | Data Storage and Caching (31.1% share, 2025) | AI and ML Workloads (27.1% CAGR, 2026–2035) |
| By End-User Industry | Retail and E-commerce; Gaming and Entertainment; IT and Telecom; BFSI; Healthcare and Life Sciences; Manufacturing and Supply Chain; Government and Public Sector; Other Industries | Retail and E-commerce (24.7% share, 2025) | Healthcare and Life Sciences (23.8% CAGR, 2026–2035) |
| By Enterprise Size | Large Enterprises; Small and Medium Enterprises | Large Enterprises (56.9% share, 2025) | Small and Medium Enterprises (22.6% CAGR, 2026–2035) |
Market Segmentation Overview
By Database Type
| Sub-Segment | Key Trend |
| Document Store | Graph operators and vector fields embedded into document engines |
| Key-Value Store | Sustained dominance in session, cart and feature-flag caching |
| Wide-Column Store | Time-series roll-ups added for industrial telemetry retention. |
| Graph Database | Pathfinding queries adopted for fraud and identity analytics |
| Multi-Model Database | Single query layer spanning graph, document and vector data |
| In-Memory NoSQL Database | Vector similarity search layered onto millisecond cache tiers. |
Key-Value Store engines lead this dimension on 35.2% share because session and shopping-cart operations need predictable microsecond reads rather than expressive queries, and buyers rarely rearchitect a workload that already meets its latency budget. Graph Database grows fastest at 27.0% CAGR as financial-crime and identity teams reframe detection as traversal across accounts, devices and merchants — a query shape relational joins handle expensively. Document Store platforms occupy the pragmatic middle, absorbing graph and vector features so architects can consolidate licences instead of running three engines side by side.
By Deployment Mode
| Sub-Segment | Key Trend |
| Cloud | Serverless and multi-region tiers billed on consumption |
| On-Premises | Sovereign clusters with customer-managed encryption keys |
Cloud holds 60.7% of revenue and remains the fastest-expanding mode, because managed elasticity removes the cluster-operations burden that historically gated adoption among teams without dedicated database administrators. On-Premises revenue persists at USD 5.52 billion where residency law, audit obligations or deterministic latency targets rule out shared infrastructure — central banking, defence and clinical systems especially. The practical middle ground most regulated buyers now tender for pairs of local primaries with cloud replicas under one control plane.
By Application
| Sub-Segment | Key Trend |
| Data Storage and Caching | Cached objects coupled with durable persistence to cut stale reads |
| Real-Time Analytics | Sub-second decisioning embedded into gaming and payment flows |
| Mobile and Web Apps | Auto-sharded clusters absorbing unpredictable traffic spikes |
| IoT and Sensor Data Management | Edge buffering with central reconciliation for telemetry fleets |
| AI and ML Workloads | Embeddings and metadata co-located for retrieval pipelines. |
| Content Management | Flexible schemas holding mixed media and textual metadata |
Data Storage and Caching leads on 31.1% share, a position built over a decade of high-traffic web backends where operators simply will not risk a rewrite. AI and ML Workloads climb fastest at 27.1% CAGR because vector-friendly indexes let a single store serve both embedding lookup and metadata filtering, collapsing what used to be two systems and a synchronisation job. Real-Time Analytics funds much of the middle tier, with gaming and fintech operators treating query latency as a revenue variable rather than an infrastructure metric.
By End-User Industry
| Sub-Segment | Key Trend |
| Retail and E-commerce | Hourly catalogue and profile changes through peak campaigns |
| Gaming and Entertainment | Globally distributed session state and leaderboard consistency |
| IT and Telecom | Subscriber data platforms consolidated onto flexible schemas. |
| BFSI | Graph traversals replacing relational joins in fraud detection. |
| Healthcare and Life Sciences | Genomic and imaging archives under strict access controls |
| Manufacturing and Supply Chain | Time-series functions monitoring equipment anomalies. |
| Government and Public Sector | Smart-city payloads blending traffic, weather and citizen feedback |
| Other Industries | Education, energy and professional services digitisation |
Retail and E-commerce holds 24.7% of revenue because product catalogues and customer profiles mutate continuously and cannot tolerate a schema freeze during peak trading. Healthcare and Life Sciences expands fastest at 23.8% CAGR as sequencing output and imaging archives outgrow relational storage economics while HIPAA-aligned access controls mature in managed offerings. BFSI spending stays concentrated on graph traversal for payment-chain anomaly detection, and manufacturers increasingly benchmark database choice on how cleanly it ingests unrelenting sensor feeds from Industry 4.0 estates.
By Enterprise Size
| Sub-Segment | Key Trend |
| Large Enterprises | Polyglot persistence spanning legacy relational and multiple engines |
| Small and Medium Enterprises | Serverless billing removing cluster-operations headcount |
Large Enterprises command 56.9% share because their budgets support several engines running concurrently — graph for risk, document for catalogue, in-memory for session — alongside a legacy relational core nobody intends to retire. Small and Medium Enterprises grow faster at 22.6% CAGR from a smaller base, since pay-as-you-grow pricing and managed operations eliminate the specialist headcount that previously made distributed stores impractical below a certain scale. Low-code suites bundling document or graph back ends compress feature delivery timelines sharply, which is why SME adoption tends to arrive through application platforms rather than direct database procurement.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA