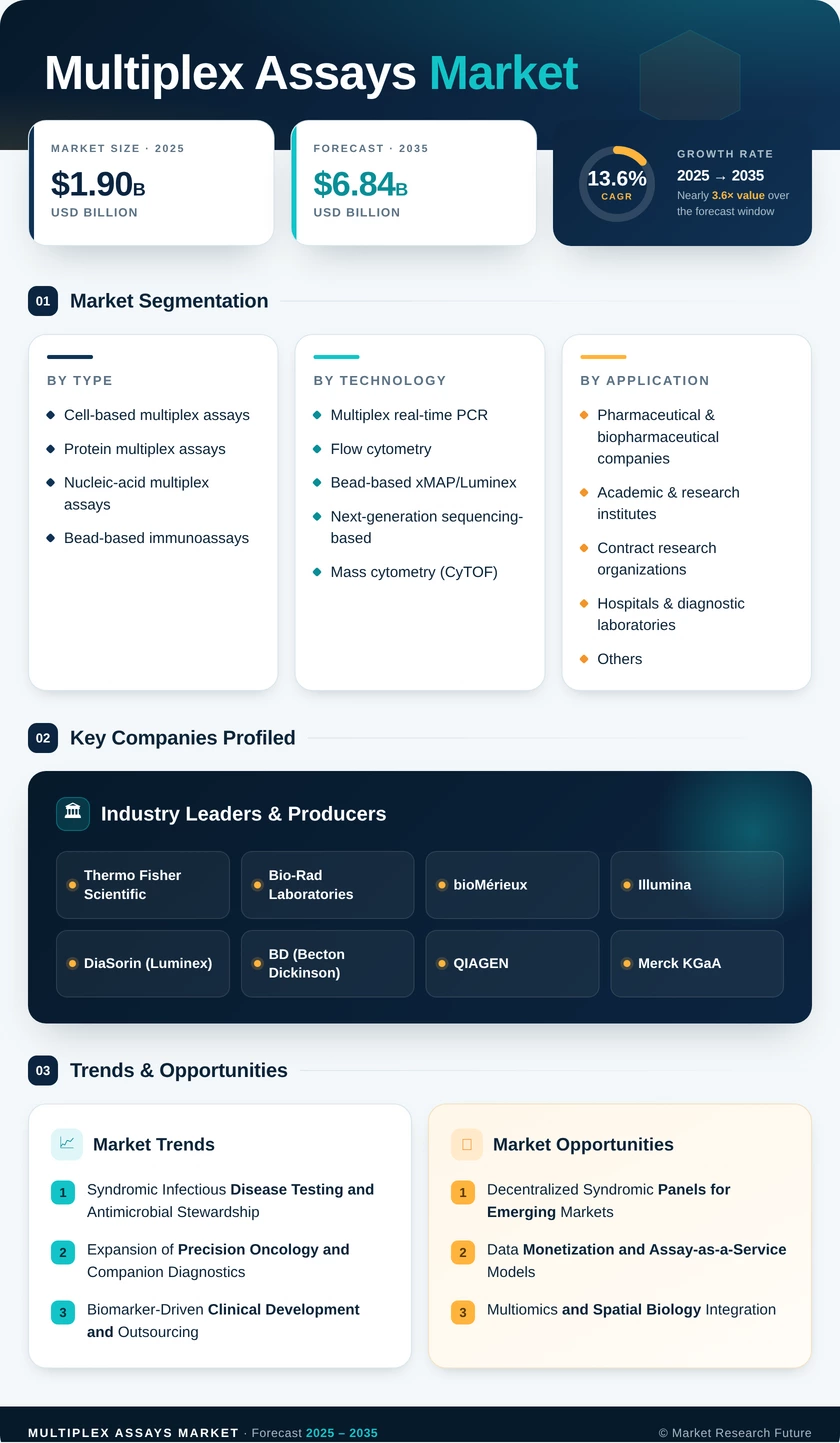
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Type | Cell-based multiplex assays, Protein multiplex assays, Nucleic-acid multiplex assays, Bead-based immunoassays | Protein multiplex assays (38.2% share) | Nucleic-acid multiplex assays (15.7% CAGR) |
| By Technology | Multiplex real-time PCR, Flow cytometry, Bead-based xMAP/Luminex, Next-generation sequencing-based, Mass cytometry (CyTOF), Microarray & others | Flow cytometry (29.8% share) | Mass cytometry (CyTOF) (14.0% CAGR) |
| By Application | Infectious disease diagnostics, Oncology & companion diagnostics, Autoimmune & allergy testing, Drug discovery & biomarker validation, Others | Infectious disease diagnostics (35.7% share) | Oncology & companion diagnostics (15.2% CAGR) |
| By End-User | Pharmaceutical & biopharmaceutical companies, Academic & research institutes, Contract research organizations, Hospitals & diagnostic laboratories, Others | Pharmaceutical & biopharmaceutical companies (42.9% share) | Contract research organizations (16.3% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East and Africa | North America (41.5% share) | Asia-Pacific (16.2% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Cell-based multiplex assays | Functional immune profiling for immuno-oncology programs |
| Protein multiplex assays | Proximity extension and aptamer panels scaling to thousands of targets |
| Nucleic-acid multiplex assays | Sequencing and CRISPR panels expanding into transplant and pathogen genotyping |
| Bead-based immunoassays | Microliter-sample cytokine quantification in trials |
Protein multiplex assays lead the type dimension because cytokine and target-engagement panels are embedded in nearly every stage of drug development. Nucleic-acid multiplex assays grow fastest, helped by regulatory acceptance of large genomic companion diagnostics and new uses in transplant monitoring. Bead-based immunoassays and Cell-based multiplex assays remain essential for quantification and functional readouts that sequencing cannot provide.
| Sub-Segment | Key Trend |
|---|
| Multiplex real-time PCR | Tiered syndromic panels shaped by payer coverage limits |
| Flow cytometry | Spectral unmixing and imaging extend instrument life |
| Bead-based xMAP/Luminex | Open platform licensed across many panel suppliers |
| Next-generation sequencing-based | Comprehensive genomic profiling for therapy selection |
| Mass cytometry (CyTOF) | 40-plus-marker single-cell panels entering clinical trials |
| Microarray & others | Stable niches in gene expression and allergen arrays |
Flow cytometry holds the largest technology share because hospitals and research cores already own large fleets that spectral and imaging upgrades keep relevant. Mass cytometry (CyTOF) grows fastest since metal-tagged antibodies avoid spectral overlap and support deeper immune profiling in trials. Multiplex real-time PCR keeps its syndromic stronghold, though payer limits on large panels are pushing suppliers toward smaller, tiered designs.
| Sub-Segment | Key Trend |
|---|
| Infectious disease diagnostics | One-hour syndromic panels supporting antibiotic stewardship |
| Oncology & companion diagnostics | Pan-cancer profiling tests tied to targeted therapies |
| Autoimmune & allergy testing | Component-resolved panels moving into primary care |
| Drug discovery & biomarker validation | Multiplex safety and efficacy readouts in lead optimization |
| Others | Metabolic, cardiovascular and transplant monitoring panels |
Infectious disease diagnostics leads applications because hospitals use multi-pathogen panels to cut time to targeted therapy and reduce empiric antibiotic use. Oncology & companion diagnostics grows fastest as each new targeted drug adds biomarkers that must be tested before prescription. Drug discovery & biomarker validation provides steady pharmaceutical demand, while Autoimmune & allergy testing benefits from broader panels in routine clinical care.
| Sub-Segment | Key Trend |
|---|
| Pharmaceutical & biopharmaceutical companies | Biomarker-guided trial designs and regulatory submissions |
| Academic & research institutes | Grant-funded early adoption of new chemistries |
| Contract research organizations | Outsourced panel validation and global sample logistics |
| Hospitals & diagnostic laboratories | Routine syndromic and oncology panel testing |
| Others | Biotech start-ups and public health laboratories |
Pharmaceutical & biopharmaceutical companies are the largest buyers, using multiplex panels for patient stratification and pharmacodynamic endpoints in regulatory filings. Contract research organizations grow fastest because sponsors prefer to outsource validated assays across global trial sites instead of duplicating instrument fleets. Academic & research institutes and Hospitals & diagnostic laboratories round out demand, with the former driving method innovation and the latter converting validated panels into routine care.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA