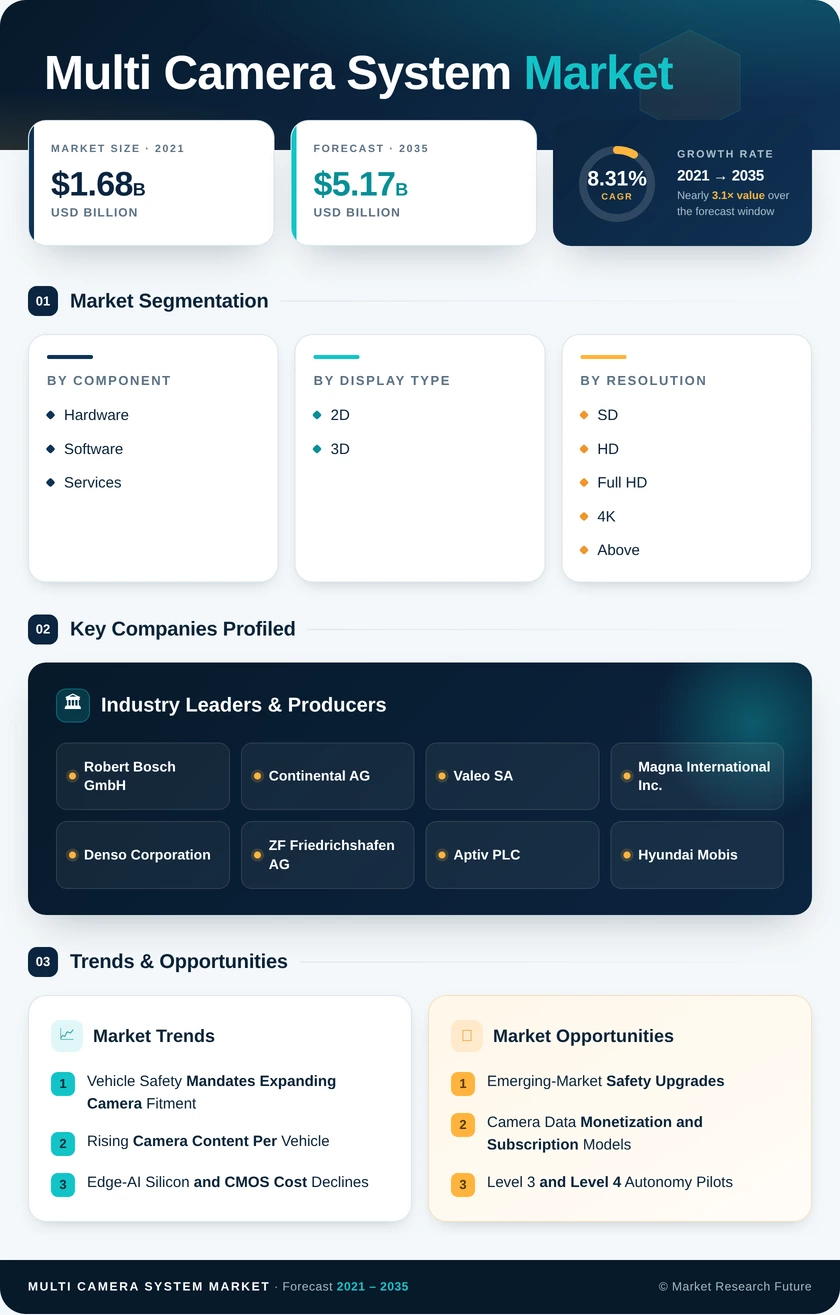
Multi Camera System Market (2026 - 2035)

ID: MRFR/AT/3914-HCR 111 Pages Triveni Bhoyar Last Updated: October 12, 2026
Multi Camera System Market Research Report By Component (Hardware, Software, Services), By Display Type (2D, 3D), By Resolution (SD, HD and Full HD, 4K and Above), By End-User Industry (Automotive, Industrial Manufacturing and Robotics, Media, Entertainment and Broadcasting, Sports and Motion Analytics, Healthcare and Medical Imaging, Other End-User Industries) - Forecast to 2035
Multi Camera System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.31%
2025 Market SizeUSD 2.32 Billion
2035 Market SizeUSD 5.17 Billion
Key Players
Robert Bosch GmbH
Continental AG
Valeo SA
Magna International Inc.
Denso Corporation
ZF Friedrichshafen AG
Opportunities
  • Emerging-Market Safety Upgrades
  • Camera Data Monetization and Subscription Models
  • Level 3 and Level 4 Autonomy Pilots
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Component | |
    2. 2.2 By Display Type | |
    3. 2.3 By Resolution | |
    4. 2.4 By End-User Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Vehicle Safety Mandates Expanding Camera Fitment | |
    2. 4.2 Rising Camera Content Per Vehicle | |
    3. 4.3 Edge-AI Silicon and CMOS Cost Declines | |
    4. 4.4 Electric Vehicle Platform Growth | |
    5. 4.5 Smart-City and Public-Safety Programs | |
    6. 4.6 Sports Broadcasting and Volumetric Capture | |
    7. 4.7 Industrial Automation and Robotics Vision | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 High Integration and Calibration Costs | |
    2. 5.2 Privacy and AI Regulation | |
    3. 5.3 Semiconductor Supply Volatility | |
    4. 5.4 Bandwidth and Storage Burden of Multi-Stream 4K | |
    5. 5.5 Cybersecurity Compliance Costs | |
  6. 6 Opportunities | |
    1. 6.1 Emerging-Market Safety Upgrades | |
    2. 6.2 Camera Data Monetization and Subscription Models | |
    3. 6.3 Level 3 and Level 4 Autonomy Pilots | |
    4. 6.4 Healthcare and Medical Imaging Arrays | |
    5. 6.5 Managed-Service Roll-Ups | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 South Korea | | |
      4. 7.3.4 India | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Perception and Sensor Fusion | |
    2. 8.2 Platform Economics and Software Monetization | |
    3. 8.3 Immersive Media and Volumetric Capture | |
    4. 8.4 Sustainability and Data Governance | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Hardware | | |
      2. 9.1.2 Software | | |
      3. 9.1.3 Services | |
    2. 9.2 By Display Type | | |
      1. 9.2.1 2D | | |
      2. 9.2.2 3D | |
    3. 9.3 By Resolution | | |
      1. 9.3.1 SD | | |
      2. 9.3.2 HD and Full HD | | |
      3. 9.3.3 4K and Above | |
    4. 9.4 By End-User Industry | | |
      1. 9.4.1 Automotive | | |
      2. 9.4.2 Industrial Manufacturing and Robotics | | |
      3. 9.4.3 Media, Entertainment and Broadcasting | | |
      4. 9.4.4 Sports and Motion Analytics | | |
      5. 9.4.5 Healthcare and Medical Imaging | | |
      6. 9.4.6 Other End-User Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Robert Bosch GmbH | | |
      2. 10.3.2 Continental AG | | |
      3. 10.3.3 Valeo SA | | |
      4. 10.3.4 Magna International Inc. | | |
      5. 10.3.5 Denso Corporation | | |
      6. 10.3.6 ZF Friedrichshafen AG | | |
      7. 10.3.7 Aptiv PLC | | |
      8. 10.3.8 Hyundai Mobis | | |
      9. 10.3.9 Sony Semiconductor Solutions | | |
      10. 10.3.10 Canon Inc. | | |
      11. 10.3.11 Axis Communications AB | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Summary, 2025 and 2035 | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis | |
  18. TABLE 4 Restraints Impact Analysis | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America Market, by Country | |
  21. TABLE 7 Europe Market, by Country | |
  22. TABLE 8 Asia-Pacific Market, by Country | |
  23. TABLE 9 South America Market, by Country | |
  24. TABLE 10 Middle East & Africa Market, by Country | |
  25. TABLE 11 Market, by Component, 2025–2035 | |
  26. TABLE 12 Market, by Display Type, 2025–2035 | |
  27. TABLE 13 Market, by Resolution, 2025–2035 | |
  28. TABLE 14 Market, by End-User Industry, 2025–2035 | |
  29. TABLE 15 Competitive Benchmarking Matrix | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | |
  32. TABLE 18 Segmentation Quick Reference | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  34. FIGURE 2 Industry Value Chain Analysis | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  37. FIGURE 5 Market Share, by Component, 2025 | |
  38. FIGURE 6 Market Share, by Display Type, 2025 | |
  39. FIGURE 7 Market Share, by Resolution, 2025 | |
  40. FIGURE 8 Market Share, by End-User Industry, 2025 | |
  41. FIGURE 9 Regional Market Share, 2025 | |
  42. FIGURE 10 Regional Growth Comparison, 2026–2035 | |
  43. FIGURE 11 Competitive Landscape Positioning Map | |
  44. FIGURE 12 Estimated Revenue Share Ranges of Key Players

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentHardware; Software; ServicesHardware (57.6% share)Services (9.15% CAGR)
By Display Type2D; 3D2D (64.9% share)3D (10.05% CAGR)
By ResolutionSD; HD and Full HD; 4K and AboveHD and Full HD (47.9% share)4K and Above (11.45% CAGR)
By End-User IndustryAutomotive; Industrial Manufacturing and Robotics; Media, Entertainment and Broadcasting; Sports and Motion Analytics; Healthcare and Medical Imaging; Other End-User IndustriesAutomotive (50.3% share)Sports and Motion Analytics (10.85% CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-Pacific (35.6% share)Middle East & Africa (8.72% CAGR)


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
HardwareOn-sensor AI and modular ECU boards reused across vehicle platforms
SoftwareLicensable stitching, calibration and perception algorithms
ServicesManaged integration and multi-year maintenance contracts


Hardware leads with a 57.6% share because every deployment still starts with imagers, lenses and processing boards, and automotive volumes keep unit demand high. Services grow fastest at a 9.15% CAGR as factories, campuses and cities hand integration with MES, ERP and security platforms to specialists. Software sits between the two, gaining share as calibration and perception code is sold separately from the camera itself.

By Display Type

Sub-SegmentKey Trend
2DRetained in cost-sensitive control rooms and basic rear-view displays
3DStitched bird's-eye views for vehicles and city-scale command centers


2D holds a 64.9% share because most monitoring consoles and entry-level vehicle displays are built around flat feeds, and replacing them carries retraining costs. 3D expands at a 10.05% CAGR as truck makers and public-safety agencies adopt stitched panoramic views that remove blind zones. GPU-equipped displays and depth-aware arrays make 3D practical outside premium installations.

By Resolution

Sub-SegmentKey Trend
SDLong-retention wide-area coverage in large camera estates
HD and Full HDDefault tier balancing clarity, bandwidth and storage
4K and Above8-megapixel automotive sensors and compact 4K domes


HD and Full HD leads with a 47.9% share because it meets most detection needs without overloading networks or storage. 4K and Above grows fastest at an 11.45% CAGR as automotive programs adopt 8-megapixel sensors for long-range night-time classification. SD survives where operators run tens of thousands of endpoints and value retention length over image detail.

By End-User Industry

Sub-SegmentKey Trend
AutomotiveMandated rear, front and panoramic cameras per vehicle
Industrial Manufacturing and RoboticsMulti-view inspection cells and robot guidance
Media, Entertainment and BroadcastingMulti-angle live production with remote operation
Sports and Motion AnalyticsPermanent stadium arrays feeding stats and replays
Healthcare and Medical ImagingStereo vision for surgical robots and patient monitoring
Other End-User IndustriesRetail checkout, agriculture and infrastructure inspection


Automotive dominates with a 50.3% share because UNECE and NHTSA rules make multiple cameras standard on new vehicles. Sports and Motion Analytics grows fastest at a 10.85% CAGR as venues install permanent synchronized arrays and single-operator PTZ control reduces production crews. Industrial Manufacturing and Robotics and Healthcare and Medical Imaging add higher-margin demand tied to depth perception and precision.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.