Moisture Analyzer Market (2026 - 2035)

ID: MRFR/SEM/5971-CR 116 Pages Ankit Gupta Last Updated: September 15, 2026
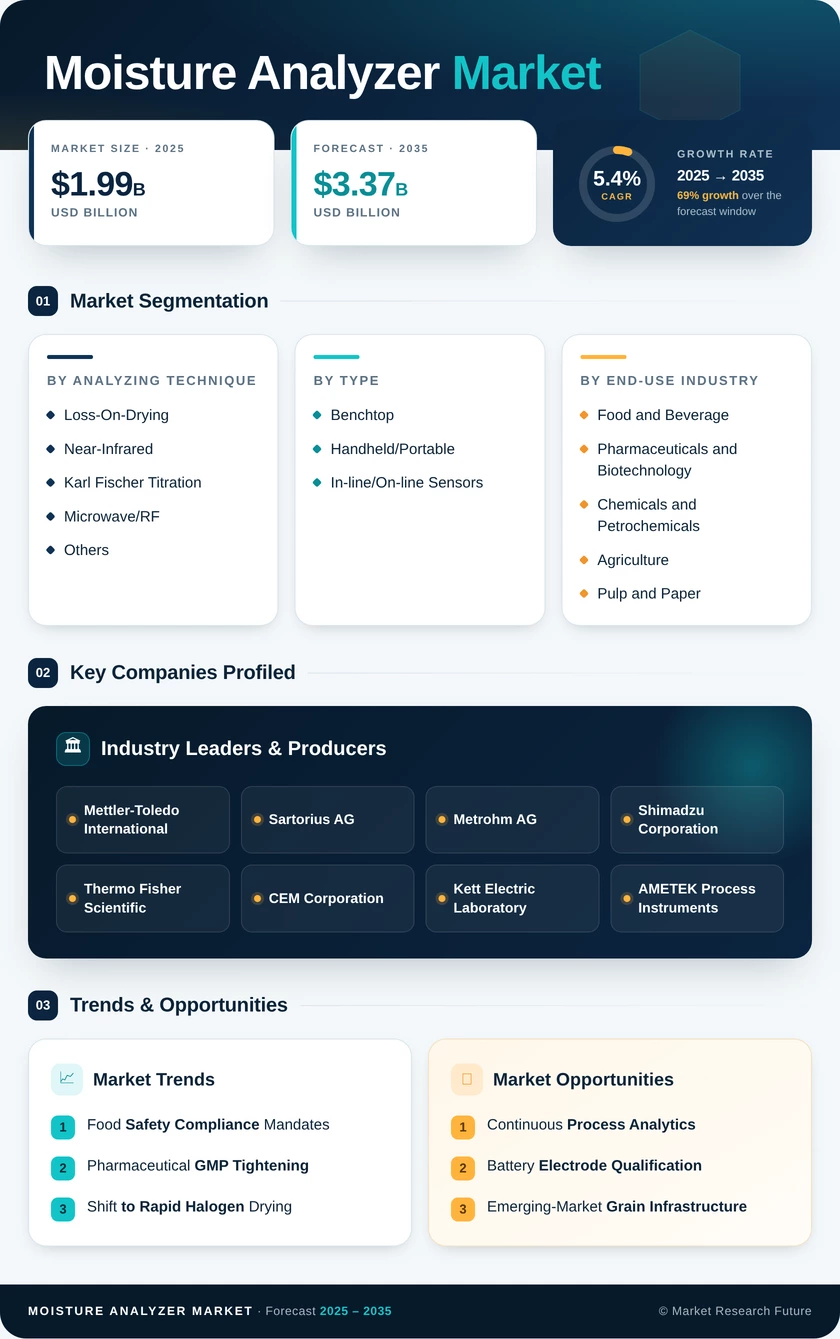
Moisture Analyzer Market Size, Share and Research Report By Analyzing Technique (Loss-On-Drying, Near-Infrared, Karl Fischer Titration, Microwave/RF, Others), By Equipment Type (Benchtop, Handheld/Portable, In-line/On-line Sensors), By End-Use Industry (Food and Beverage, Pharmaceuticals and Biotechnology, Chemicals and Petrochemicals, Agriculture and Feed, Pulp and Paper, Others), By Component (Moisture Analyzer Instrument, Sensors and Probes, Consumables) and By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Industry Forecast to 2035
Moisture Analyzer Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.4%
2025 Market SizeUSD 1.99 Billion
2035 Market SizeUSD 3.37 Billion
Key Players
Mettler-Toledo International
Sartorius AG
Metrohm AG
Shimadzu Corporation
Thermo Fisher Scientific
CEM Corporation
Opportunities
  • Continuous Process Analytics
  • Battery Electrode Qualification
  • Emerging-Market Grain Infrastructure
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Report Takeaways |
    1. 2.1 Takeaways by Technology |
    2. 2.2 Takeaways by Sector |
    3. 2.3 Takeaways by Geography
  3. 3 Global Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Dynamics — Drivers |
    1. 4.1 Food Safety Compliance Mandates |
    2. 4.2 Pharmaceutical GMP Tightening |
    3. 4.3 Shift to Rapid Halogen Drying |
    4. 4.4 Process Line Integration of Sensors |
    5. 4.5 Battery and Electronics Materials Quality Control |
    6. 4.6 Agricultural Grain Trading Standards |
    7. 4.7 Laboratory Data-Integrity Digitization
  5. 5 Market Dynamics — Restraints |
    1. 5.1 High Capital Cost of Titration Systems |
    2. 5.2 Extended Replacement Cycles for Bench Units |
    3. 5.3 Method Validation Burden |
    4. 5.4 Skilled Operator Scarcity |
    5. 5.5 Reagent Supply and Disposal Costs
  6. 6 Market Opportunity Analysis |
    1. 6.1 Continuous Process Analytics |
    2. 6.2 Battery Electrode Qualification |
    3. 6.3 Emerging-Market Grain Infrastructure |
    4. 6.4 Instrument Data Monetization |
    5. 6.5 Contract Testing Laboratory Expansion |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 United States | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 United Kingdom | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Chemometric Model Automation |
    2. 8.2 Servitization of Instrument Fleets |
    3. 8.3 Energy Efficiency in Industrial Drying |
    4. 8.4 Traceability and Digital Compliance
  9. 9 Segmentation Analysis |
    1. 9.1 By Analyzing Technique | |
      1. 9.1.1 Loss-On-Drying | |
      2. 9.1.2 Near-Infrared | |
      3. 9.1.3 Karl Fischer Titration | |
      4. 9.1.4 Microwave/RF | |
      5. 9.1.5 Others |
    2. 9.2 By Equipment Type | |
      1. 9.2.1 Benchtop | |
      2. 9.2.2 Handheld/Portable | |
      3. 9.2.3 In-line/On-line Sensors |
    3. 9.3 By End-Use Industry | |
      1. 9.3.1 Food and Beverage | |
      2. 9.3.2 Pharmaceuticals and Biotechnology | |
      3. 9.3.3 Chemicals and Petrochemicals | |
      4. 9.3.4 Agriculture and Feed | |
      5. 9.3.5 Pulp and Paper | |
      6. 9.3.6 Others |
    4. 9.4 By Component | |
      1. 9.4.1 Moisture Analyzer Instrument | |
      2. 9.4.2 Sensors and Probes | |
      3. 9.4.3 Consumables
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Mettler-Toledo International | |
      2. 10.3.2 Sartorius AG | |
      3. 10.3.3 Metrohm AG | |
      4. 10.3.4 Shimadzu Corporation | |
      5. 10.3.5 A&D Company | |
      6. 10.3.6 Thermo Fisher Scientific | |
      7. 10.3.7 CEM Corporation | |
      8. 10.3.8 Kett Electric Laboratory | |
      9. 10.3.9 AMETEK Process Instruments | |
      10. 10.3.10 Bruker Corporation | |
      11. 10.3.11 PCE Instruments
  11. 11 Recent Developments & News
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Valuation Currency & Units |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Moisture Analyzer Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Moisture Analyzer Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis – Estimated Contribution to CAGR |
  19. TABLE 4 Restraint Impact Analysis – Estimated Drag on CAGR |
  20. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Market Size, by Analyzing Technique, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Market Size, by Equipment Type, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Market Size, by End-Use Industry, 2021–2035 (USD Billion) |
  29. TABLE 14 Global Market Size, by Component, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Market Size, by Analyzing Technique, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Market Size, by End-Use Industry, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Market Size, by Analyzing Technique, 2021–2035 (USD Billion) |
  33. TABLE 18 Europe Market Size, by End-Use Industry, 2021–2035 (USD Billion) |
  34. TABLE 19 Asia-Pacific Market Size, by Analyzing Technique, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Market Size, by End-Use Industry, 2021–2035 (USD Billion) |
  36. TABLE 21 South America Market Size, by Equipment Type, 2021–2035 (USD Billion) |
  37. TABLE 22 Middle East & Africa Market Size, by Equipment Type, 2021–2035 (USD Billion) |
  38. TABLE 23 Competitive Benchmarking Matrix, 2026 |
  39. TABLE 24 Company Profiles – Key Players |
  40. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 |
  41. TABLE 26 Report Scope & Methodology Summary |
  42. TABLE 27 Detailed Sources & Citations Index
  43. 16 LIST OF FIGURES |
  44. FIGURE 1 Market Dynamics Snapshot – Drivers, Restraints and Opportunities |
  45. FIGURE 2 Industry Value Chain Analysis |
  46. FIGURE 3 Porter's Five Forces Assessment |
  47. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) |
  48. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 (%) |
  49. FIGURE 6 Market Share by Analyzing Technique, 2025 vs 2035 (%) |
  50. FIGURE 7 Market Share by Equipment Type, 2025 (%) |
  51. FIGURE 8 Market Share by End-Use Industry, 2025 (%) |
  52. FIGURE 9 Market Share by Component, 2025 (%) |
  53. FIGURE 10 Regional Revenue Share Distribution, 2025 (%) |
  54. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  55. FIGURE 12 Country-Level Contribution within Asia-Pacific, 2025 (%) |
  56. FIGURE 13 Competitive Positioning Matrix – Scale versus Technology Breadth |
  57. FIGURE 14 Estimated Revenue Share of Leading Suppliers, 2026 (%) |
  58. FIGURE 15 Technology Adoption Curve – Bench versus In-line Instrumentation

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Analyzing TechniqueLoss-On-Drying; Near-Infrared; Karl Fischer Titration; Microwave/RF; OthersLoss-On-DryingNear-Infrared
By Equipment TypeBenchtop; Handheld/Portable; In-line/On-line SensorsBenchtopIn-line/On-line Sensors
By End-Use IndustryFood and Beverage; Pharmaceuticals and Biotechnology; Chemicals and Petrochemicals; Agriculture; Pulp and Paper; OthersFood and BeveragePharmaceuticals and Biotechnology
By ComponentMoisture Analyzer Instrument; Sensors and Probes; ConsumablesMoisture Analyzer InstrumentSensors and Probes
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Analyzing Technique

Sub-SegmentKey Trend
Loss-On-DryingHalogen heating displaces convection ovens as default routine method
Near-InfraredAutomated chemometric calibration lowers the specialist barrier.
Karl Fischer TitrationReagent-reduced cells cut hazardous waste per determination.
Microwave/RFAdoption widens in slurries and high-solids bulk materials.
OthersThermogravimetric and NMR platforms serve research applications.


Technique selection now depends less on tradition and more on where the measurement occurs. Laboratories retain drying and titration for compendial defensibility, while production floors adopt spectroscopic and microwave approaches that read without destroying the sample.

By Equipment Type

Sub-SegmentKey Trend
BenchtopCompliance-ready electronic records become a purchase prerequisite
Handheld/PortableRuggedized units expand across grain elevators and warehouses.
In-line/On-line SensorsClosed-loop dryer control delivers measurable energy savings.


Form factor decisions increasingly follow process architecture. Facilities running continuous lines are shifting budget from laboratory hardware to embedded sensing, while regulated batch manufacturers keep bench instruments at the centre of release testing.

By End-Use Industry

Sub-SegmentKey Trend
Food and BeverageShelf-life documentation drives per-line instrument density
Pharmaceuticals and BiotechnologySterile manufacturing rules tighten residual-water evidence.
Chemicals and PetrochemicalsFeedstock specification narrows acceptable tolerance.
AgricultureGrading standards revisions force meter replacement
Pulp and PaperEnergy cost reframes sensors as an operations investment.
OthersBattery, ceramics and textile applications emerge steadily.


Regulatory intensity predicts spending better than sector size does. Pharmaceutical buyers accept premium pricing for audit defensibility, whereas agricultural purchasers optimize hard for cost per unit deployed across many sites.

By Component

Sub-SegmentKey Trend
Moisture Analyzer InstrumentReplacement cycles lengthen, pushing vendors toward services
Sensors and ProbesRetrofit projects generate outsized attached software revenue.
ConsumablesRecurring reagent and pan sales stabilize supplier margins.


Component economics are shifting the vendor business model. Hardware alone no longer sustains growth given long installed-life, so suppliers are competing on consumables, calibration contracts, and compliance software subscriptions.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.