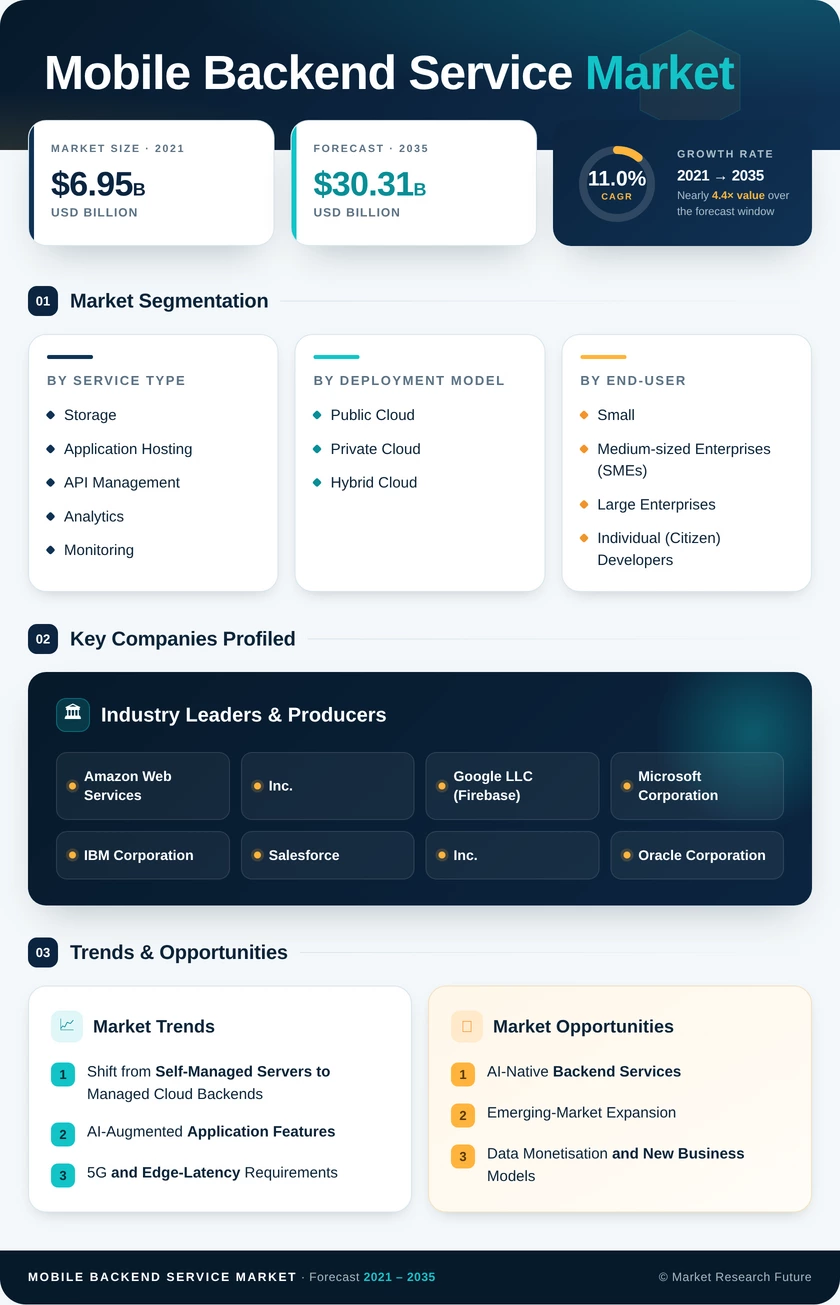
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Service Type | Storage, Application Hosting, API Management, Analytics and Monitoring | Application Hosting (39.5% share) | Analytics and Monitoring (23.4% CAGR) |
| By Deployment Model | Public Cloud, Private Cloud, Hybrid Cloud | Public Cloud (73.5% share) | Hybrid Cloud (26.2% CAGR) |
| By End-User | Small and Medium-sized Enterprises (SMEs), Large Enterprises, Individual (Citizen) Developers | Large Enterprises (54.6% share) | Small and Medium-sized Enterprises (SMEs) (23.3% CAGR) |
| By Platform | iOS, Android, Cross-Platform / Multiexperience | Android (51.8% share) | Cross-Platform / Multiexperience (15.6% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East and Africa | Asia-Pacific (35.4% share) | North America (12.6% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Storage | Growth tied to media uploads and user-generated content |
| Application Hosting | Container orchestration and CDN routing bundled into single-click stacks |
| API Management | Rising microservice counts and partner API exposure |
| Analytics and Monitoring | Observability and AI-model tracing become contract requirements |
Application Hosting leads because every app needs elastic compute for unpredictable traffic, and providers now bundle routing and secrets management with it. Analytics and Monitoring grows fastest as buyers demand latency, cost and model-behaviour telemetry. Storage and API Management expand steadily alongside media-heavy apps and microservice estates.
| Sub-Segment | Key Trend |
|---|
| Public Cloud | Default choice for start-ups and product-led growth |
| Private Cloud | Restricted to finance, defence and other regulated workloads |
| Hybrid Cloud | Edge and on-premises data planes linked to cloud control planes |
Public Cloud dominates because provisioning takes minutes and global regions come pre-built. Hybrid Cloud grows fastest as hospitals, factories and banks keep sensitive data local while using cloud authentication and analytics. Private Cloud remains a niche limited by cost and operational overhead.
| Sub-Segment | Key Trend |
|---|
| Small and Medium-sized Enterprises (SMEs) | Usage-based tiers replace in-house operations teams |
| Large Enterprises | Integration with single sign-on, audit and policy engines |
| Individual (Citizen) Developers | Free tiers and visual tooling for rapid prototypes |
Large Enterprises lead on spend because customer-facing banking, retail and logistics apps carry large user bases and governance requirements. SMEs grow fastest since subscription pricing gives them push messaging, geo-queries and authentication without dedicated staff. Individual (Citizen) Developers remain a smaller but strategic entry funnel for vendors.
| Sub-Segment | Key Trend |
|---|
| iOS | Privacy manifest rules make SDK compliance a buying criterion |
| Android | Installed-base scale across emerging economies |
| Cross-Platform / Multiexperience | Single-codebase frameworks sharing one backend |
Android leads because of its installed base in Asia-Pacific, Africa and South America, where most new app users come online. Cross-Platform / Multiexperience grows fastest as Flutter and React Native teams standardise on one backend for mobile and web. iOS remains valuable for its higher spend per user and stricter SDK privacy rules.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA