MEA Lubricants Market (2026 - 2035)

ID: MRFR/CnM/19911-CR 128 Pages Chitranshi Jaiswal Last Updated: October 12, 2026
MEA Lubricants Market Research Report Information By Group (Group I, Group II, Group III, Group IV, and Group V), By Base Stock (Bio-based Lubricant, Mineral Oil Lubricant, Synthetic Lubricant, and Semi-synthetic Lubricant), By Product Type (Engine Oil, Transmission and Hydraulic Fluid, Metalworking Fluid, General Industrial Oil, Gear Oil, and Other Product Types), and By End-user Industry (Power Generation, Automotive and Other Transportation, Heavy Equipment, Metallurgy and Metalworking, Chemical Manufacturing, and Other End-user Industries) – Forecast Till 2035
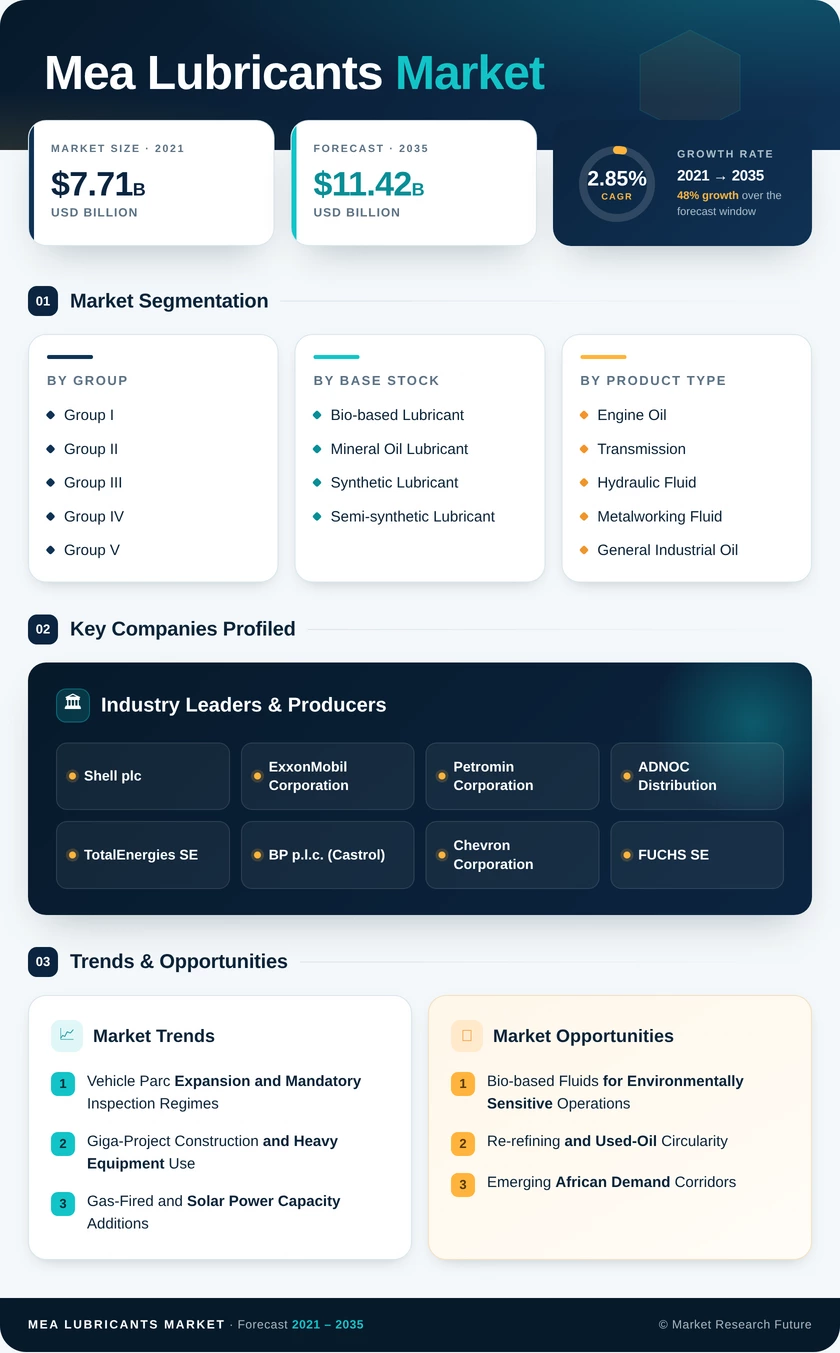
MEA Lubricants Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)2.85%
2025 Market SizeUSD 8.62 billion
2035 Market SizeUSD 11.42 billion
Key Players
Shell plc
ExxonMobil Corporation
Petromin Corporation
ADNOC Distribution
TotalEnergies SE
BP p.l.c.
Opportunities
  • Bio-based Fluids for Environmentally Sensitive Operations
  • Re-refining and Used-Oil Circularity
  • Emerging African Demand Corridors
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Group | |
    2. 2.2 By Base Stock | |
    3. 2.3 By Product Type | |
    4. 2.4 By End-user Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Market Size (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Vehicle Parc Expansion and Mandatory Inspection Regimes | |
    2. 4.2 Giga-Project Construction and Heavy Equipment Use | |
    3. 4.3 Gas-Fired and Solar Power Capacity Additions | |
    4. 4.4 Base Oil Upgrading and Local Supply Security | |
    5. 4.5 Industrial Localization Programs | |
    6. 4.6 Premiumization Through OEM Specifications | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Electric Vehicle Adoption | |
    2. 5.2 Extended Drain Intervals | |
    3. 5.3 Counterfeit and Substandard Product | |
    4. 5.4 Base Oil and Crude Price Volatility | |
    5. 5.5 Sanctions and Trade Restrictions | |
  6. 6 Opportunities | |
    1. 6.1 Bio-based Fluids for Environmentally Sensitive Operations | |
    2. 6.2 Re-refining and Used-Oil Circularity | |
    3. 6.3 Emerging African Demand Corridors | |
    4. 6.4 Condition Monitoring and Lubrication-as-a-Service | |
    5. 6.5 EV Thermal Management and E-Fluids | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Saudi Arabia | |
    2. 7.2 United Arab Emirates | |
    3. 7.3 Iran | |
    4. 7.4 Qatar | |
    5. 7.5 Kuwait | |
    6. 7.6 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Predictive Maintenance and Digital Oil Analysis | |
    2. 8.2 Electrification and E-Fluid Portfolios | |
    3. 8.3 Base Oil Export Hub Economics | |
    4. 8.4 Circularity and ESG Disclosure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Group | | |
      1. 9.1.1 Group I | | |
      2. 9.1.2 Group II | | |
      3. 9.1.3 Group III | | |
      4. 9.1.4 Group IV | | |
      5. 9.1.5 Group V | |
    2. 9.2 By Base Stock | | |
      1. 9.2.1 Bio-based Lubricant | | |
      2. 9.2.2 Mineral Oil Lubricant | | |
      3. 9.2.3 Synthetic Lubricant | | |
      4. 9.2.4 Semi-synthetic Lubricant | |
    3. 9.3 By Product Type | | |
      1. 9.3.1 Engine Oil | | |
      2. 9.3.2 Transmission and Hydraulic Fluid | | |
      3. 9.3.3 Metalworking Fluid | | |
      4. 9.3.4 General Industrial Oil | | |
      5. 9.3.5 Gear Oil | | |
      6. 9.3.6 Other Product Types | |
    4. 9.4 By End-user Industry | | |
      1. 9.4.1 Power Generation | | |
      2. 9.4.2 Automotive and Other Transportation | | |
      3. 9.4.3 Heavy Equipment | | |
      4. 9.4.4 Metallurgy and Metalworking | | |
      5. 9.4.5 Chemical Manufacturing | | |
      6. 9.4.6 Other End-user Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Shell plc | | |
      2. 10.3.2 ExxonMobil Corporation | | |
      3. 10.3.3 Petromin Corporation | | |
      4. 10.3.4 Behran Oil Company | | |
      5. 10.3.5 ADNOC Distribution | | |
      6. 10.3.6 TotalEnergies SE | | |
      7. 10.3.7 Sepahan Oil Company | | |
      8. 10.3.8 Emirates National Oil Company (ENOC) | | |
      9. 10.3.9 BP p.l.c. (Castrol) | | |
      10. 10.3.10 Iranol Oil Company | | |
      11. 10.3.11 Chevron Corporation | | |
      12. 10.3.12 FUCHS SE | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Market Snapshot Summary, 2025–2035 | |
  16. TABLE 2 Market Size & Forecast, by Revenue (USD billion), 2021–2035 | |
  17. TABLE 3 Year-over-Year Growth Analysis, 2021–2035 | |
  18. TABLE 4 Driver Impact Analysis | |
  19. TABLE 5 Restraints Impact Analysis | |
  20. TABLE 6 Regional Summary, by Country, 2025 | |
  21. TABLE 7 Saudi Arabia Demand Hubs, 2025 | |
  22. TABLE 8 United Arab Emirates Demand Hubs, 2025 | |
  23. TABLE 9 Iran Demand Hubs, 2025 | |
  24. TABLE 10 Qatar Demand Hubs, 2025 | |
  25. TABLE 11 Kuwait Demand Hubs, 2025 | |
  26. TABLE 12 Rest of Middle East and Africa Demand Hubs, 2025 | |
  27. TABLE 13 Market Size, by Group, 2021–2035 (USD billion) | |
  28. TABLE 14 Market Size, by Base Stock, 2021–2035 (USD billion) | |
  29. TABLE 15 Market Size, by Product Type, 2021–2035 (USD billion) | |
  30. TABLE 16 Market Size, by End-user Industry, 2021–2035 (USD billion) | |
  31. TABLE 17 Market Size, by Country, 2021–2035 (USD billion) | |
  32. TABLE 18 Saudi Arabia Market Size, by Product Type, 2021–2035 (USD billion) | |
  33. TABLE 19 United Arab Emirates Market Size, by Product Type, 2021–2035 (USD billion) | |
  34. TABLE 20 Iran Market Size, by Product Type, 2021–2035 (USD billion) | |
  35. TABLE 21 Qatar Market Size, by Product Type, 2021–2035 (USD billion) | |
  36. TABLE 22 Kuwait Market Size, by Product Type, 2021–2035 (USD billion) | |
  37. TABLE 23 Rest of Middle East and Africa Market Size, by Product Type, 2021–2035 (USD billion) | |
  38. TABLE 24 Competitive Benchmarking Matrix, 2025 | |
  39. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 | |
  40. TABLE 26 Report Scope and Methodology | |
  41. TABLE 27 Detailed Sources and Citations | | LIST OF FIGURES | |
  42. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  43. FIGURE 2 Industry Value Chain Analysis | |
  44. FIGURE 3 Porter's Five Forces Analysis | |
  45. FIGURE 4 Market Size Trend, 2021–2035 (USD billion) | |
  46. FIGURE 5 Year-over-Year Growth Rate, 2021–2035 | |
  47. FIGURE 6 Market Share, by Group, 2025 | |
  48. FIGURE 7 Market Share, by Base Stock, 2025 | |
  49. FIGURE 8 Market Share, by Product Type, 2025 | |
  50. FIGURE 9 Market Share, by End-user Industry, 2025 | |
  51. FIGURE 10 Market Share, by Country, 2025 | |
  52. FIGURE 11 Country Growth Comparison, 2026–2035 CAGR | |
  53. FIGURE 12 Competitive Landscape, Estimated Revenue Share Ranges, 2025 | |
  54. FIGURE 13 Market Concentration and Positioning Map

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By GroupGroup I, Group II, Group III, Group IV, Group VGroup I (43.4% share)Group III (3.6% CAGR)
By Base StockBio-based Lubricant, Mineral Oil Lubricant, Synthetic Lubricant, Semi-synthetic LubricantMineral Oil Lubricant (64.9% share)Bio-based Lubricant (3.35% CAGR)
By Product TypeEngine Oil, Transmission and Hydraulic Fluid, Metalworking Fluid, General Industrial Oil, Gear Oil, Other Product TypesEngine Oil (40.1% share)Transmission and Hydraulic Fluid (3.22% CAGR)
By End-user IndustryPower Generation, Automotive and Other Transportation, Heavy Equipment, Metallurgy and Metalworking, Chemical Manufacturing, Other End-user IndustriesAutomotive and Other Transportation (48.3% share)Power Generation (3.31% CAGR)
By RegionSaudi Arabia, United Arab Emirates, Iran, Qatar, Kuwait, Rest of Middle East and AfricaSaudi Arabia (34.6% share)United Arab Emirates (3.42% CAGR)


Market Segmentation Overview

By Group

Sub-SegmentKey Trend
Group IRetained for cost-sensitive splash-lubricated and moderate-temperature equipment
Group IIGaining share as domestic hydroprocessing capacity expands
Group IIISpecified by OEMs for turbocharged engines in extreme heat
Group IVUsed in high-performance synthetic engine and gear formulations
Group VServes ester-based turbine and refrigeration applications


Group I leads because cost-sensitive industrial buyers still run compressors and gensets on solvent-refined oils with proven additive recipes. Group III grows fastest as OEMs require its lower volatility and higher viscosity index for engines working in sustained 50 °C heat. Group II sits between them, benefiting directly from Luberef's capacity shift at Yanbu.

By Base Stock

Sub-SegmentKey Trend
Bio-based LubricantEster hydraulic and metal-forming fluids adopted under carbon-reduction pledges
Mineral Oil LubricantDominant on cost and regional refining availability
Synthetic LubricantRising with low-viscosity OEM specifications
Semi-synthetic LubricantBlends offering a performance-cost compromise for fleets


Mineral Oil Lubricant dominates because Gulf refineries supply abundant, low-cost base oil compatible with most additive packages. Bio-based Lubricant grows fastest as logistics and petrochemical operators write biodegradability into tenders, although oxidative stability still raises formulation cost. Semi-synthetic Lubricant blends absorb buyers who want better performance without full synthetic pricing.

By Product Type

Sub-SegmentKey Trend
Engine OilStable replacement demand under periodic vehicle inspection programs
Transmission and Hydraulic FluidStrong pull from construction, port and tunnel-boring fleets
Metalworking FluidExpanding with new CNC fabrication capacity
General Industrial OilTied to compressors, pumps and process equipment
Gear OilSupported by industrial gearbox and mining conveyor demand
Other Product TypesProcess oils and specialty fluids for niche uses


Engine Oil leads on the back of a vehicle parc above 15 million units and inspection-driven service frequency. Transmission and Hydraulic Fluid grows fastest because giga-project equipment needs high-viscosity-index anti-wear fluids in desert conditions. Metalworking Fluid follows new machining capacity at fabrication hubs serving NEOM and Ras Al Khair.

By End-user Industry

Sub-SegmentKey Trend
Power GenerationGas turbine and solar-hybrid additions require varnish-resistant fluids
Automotive and Other TransportationLargest volume base from cars and road freight
Heavy EquipmentConstruction and mining fleet hours drive consumption
Metallurgy and MetalworkingSteel and aluminum capacity sustains demand.
Chemical ManufacturingPetrochemical expansions in Jubail and Ruwais
Other End-user IndustriesMarine, agriculture and food processing niches


Automotive and Other Transportation leads thanks to dense private car ownership and busy road-freight corridors. Power Generation grows fastest as F-class turbines and concentrated solar plants demand high-temperature fluids that conventional mineral oils struggle to match. Heavy Equipment remains a large value pool tied to construction activity under Vision 2030.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.