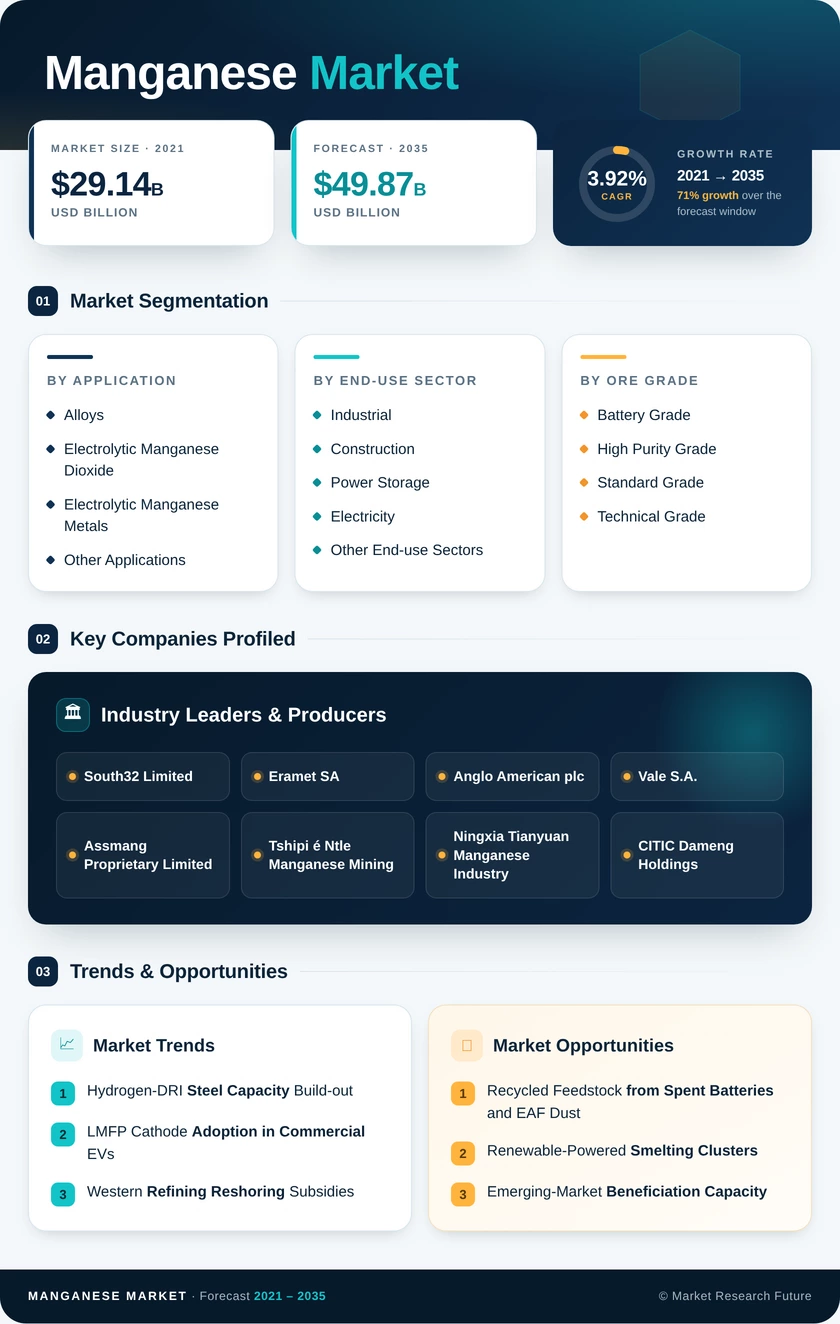
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Application | Alloys; Electrolytic Manganese Dioxide; Electrolytic Manganese Metals; Other Applications | Alloys (62.9% share, 2025) | Electrolytic Manganese Dioxide (6.62% CAGR) |
| By End-use Sector | Industrial; Construction; Power Storage and Electricity; Other End-use Sectors | Industrial (49.4% share, 2025) | Power Storage and Electricity (6.79% CAGR) |
| By Ore Grade | Battery Grade; High Purity Grade; Standard Grade; Technical Grade | Standard Grade (54.9% share, 2025) | Battery Grade (6.91% CAGR) |
Market Segmentation Overview
By Application
| Sub-Segment | Key Trend |
| Alloys | Hydrogen-DRI conversion raises alloy addition intensity per tonne of crude steel |
| Electrolytic Manganese Dioxide | Zinc-manganese and grid-storage pilots revive demand beyond portable cells |
| Electrolytic Manganese Metals | Stainless and specialty producers tighten purity specifications |
| Other Applications | Feed, water treatment, and ceramics demand tracks GDP growth |
Alloys lead because steelmakers consume ferroalloy additions in direct proportion to crude steel output, and the shift to direct reduced iron routes increases rather than reduces that intensity. Electrolytic Manganese Dioxide grows fastest as utility procurement for long-duration storage rewards chemistries built on abundant inputs, and as portable cell volumes hold their base. Electrolytic Manganese Metals occupy a narrower band where specification, not price, governs supplier selection. Other Applications add volume stability without shifting the growth profile.
By End-use Sector
| Sub-Segment | Key Trend |
| Industrial | Steel mills and foundries anchor baseline consumption |
| Construction | Rebar-intensive South Asian and Gulf projects sustain demand to 2028 |
| Power Storage and Electricity | LMFP cathodes and stationary storage drive premium-tier growth |
| Other End-use Sectors | Electronics, agriculture, and ceramics grow near GDP |
Industrial buyers lead by a wide margin because metallurgical consumption dwarfs every other channel, and mill utilization rates set the pace for the entire sector. Power Storage and Electricity grows fastest as heavy-duty vehicle platforms qualify LMFP cathodes and utilities tender for long-duration capacity where input abundance beats energy density. Construction remains substantial but decelerates after 2028 as Chinese property consumption settles, leaving South Asian infrastructure as the marginal driver. Other End-use Sectors move with general economic activity.
By Ore Grade
| Sub-Segment | Key Trend |
| Battery Grade | Cathode impurity limits restrict qualified supply to select deposits |
| High Purity Grade | Stainless and electronics buyers sustain steady premium demand |
| Standard Grade | Commodity smelting feedstock exposed to carbon border costs |
| Technical Grade | Agricultural micronutrient niche with limited pricing power |
Standard Grade holds the largest share because commodity ferroalloy smelting consumes the bulk of mined tonnage, though carbon border pricing is beginning to penalize coal-smelted output from this feedstock. Battery Grade grows fastest as cathode precursor specifications on iron, potassium, and heavy metals exclude most conventional deposits, concentrating qualified supply among a handful of Australian and Botswanan projects. High Purity Grade serves stainless and electronics demand at steady rates. Technical Grade stays confined to low-margin agricultural use.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA