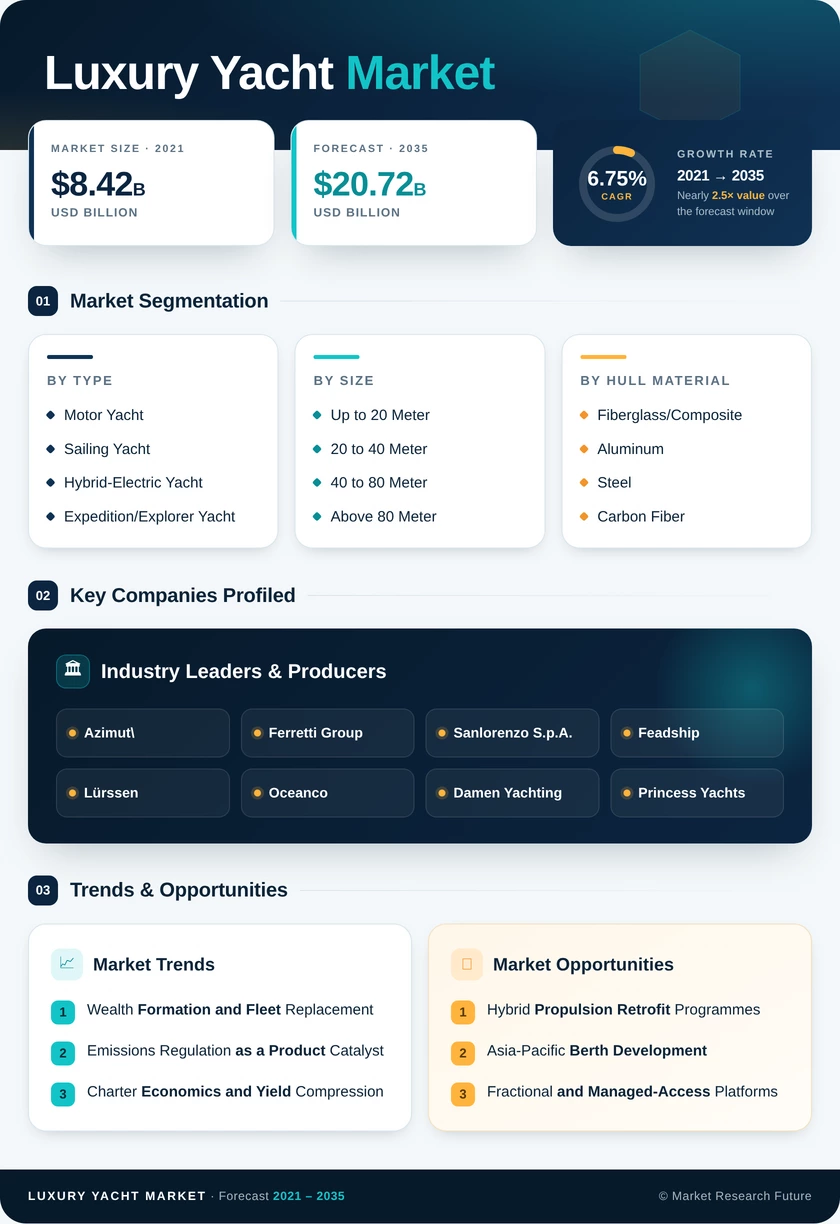
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | Motor Yacht, Sailing Yacht, Hybrid-Electric Yacht, Expedition/Explorer Yacht | Motor Yacht | Hybrid-Electric Yacht |
| By Size | Up to 20 Meter, 20 to 40 Meter, 40 to 80 Meter, Above 80 Meter | 20 to 40 Meter | Above 80 Meter |
| By Hull Material | Fiberglass/Composite, Aluminum, Steel, Carbon Fiber | Fiberglass/Composite | Carbon Fiber |
| By Propulsion System | Diesel, Diesel-Electric/Hybrid, Gas Turbine, Fully Electric | Diesel | Fully Electric |
| By End-User | Private Individuals, Charter Companies, Fractional-Ownership Clubs, Corporate/Institutional | Private Individuals | Fractional-Ownership Clubs |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Europe | Asia-Pacific |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| Motor Yacht | Interior volume and passage-speed expectations sustain default status across all length bands |
| Sailing Yacht | Performance heritage and lower fuel burn retain a committed owner base |
| Hybrid-Electric Yacht | Serial hybrid drivetrains move from custom request to catalogue option |
| Expedition/Explorer Yacht | Ice-class notation and extended tankage open polar and remote itineraries |
Type segmentation is deceptively stable. Motor yachts hold their share through the forecast, but the internal composition of that share changes materially as hybrid drivetrains become standard specification rather than premium upgrade.
By Size
| Sub-Segment | Key Trend |
| Up to 20 Meter | Entry-point ownership and day-charter fleets, most price-sensitive band |
| 20 to 40 Meter | Optimal charter yield per berth-metre; deepest brokerage liquidity |
| 40 to 80 Meter | Long-range private cruising with full-time crew complements |
| Above 80 Meter | Low unit volume, extreme value per delivery, longest lead times |
Length dictates almost everything downstream — berth access, crew size, regulatory code, and material choice. The mid-band dominates because it is the only segment where charter revenue reliably offsets a meaningful share of running cost.
By Hull Material
| Sub-Segment | Key Trend |
| Fiberglass/Composite | Mould amortisation across series production keeps unit costs lowest |
| Aluminum | Weight advantage becomes decisive above 40 metres and in fast displacement hulls |
| Steel | Preferred for large displacement and ice-strengthened explorer builds |
| Carbon Fiber | Migrating from performance sailing into fast planing motor applications |
Material selection follows a predictable logic tied to length and speed target. Carbon's growth reflects widening autoclave capacity and improved resin systems rather than any change in owner preference.
By Propulsion System
| Sub-Segment | Key Trend |
| Diesel | Global fuel availability and service depth keep it the default for offshore range |
| Diesel-Electric/Hybrid | Silent hotel load at anchor drives the strongest specification demand |
| Gas Turbine | Confined to high-speed niche applications with specialist service needs |
| Fully Electric | Viable today on tenders, inland vessels, and short-range coastal cruising |
Propulsion is the dimension undergoing genuine disruption. Diesel retains dominance on range and infrastructure, but owners increasingly specify hybrid capability for the eight hours a night when generators would otherwise run.
By End-User
| Sub-Segment | Key Trend |
| Private Individuals | Wealth formation and replacement cycles anchor baseline demand |
| Charter Companies | Opportunistic buyers who absorb brokerage inventory during soft periods |
| Fractional-Ownership Clubs | Subscription structures cut capital entry cost by roughly 85% |
| Corporate/Institutional | Hospitality and brand programmes, sensitive to disclosure obligations |
End-user segmentation is where new business models are reshaping the demand base. Fractional platforms do not compete with outright ownership so much as recruit buyers who would never have written the full cheque.
By Geography
| Sub-Segment | Key Trend |
| North America | Refit infrastructure depth and tariff-driven interest in domestic construction |
| Europe | Yard concentration, brokerage services, and mature charter itineraries |
| Asia-Pacific | Berth capacity buildout unlocking latent wealth-implied demand |
| South America | Coastal cruising corridors constrained by import duty and currency volatility |
| Middle East & Africa | Sovereign marina programmes creating capacity where none existed |
Geographic performance tracks infrastructure more closely than wealth. Asia holds abundant qualifying buyers; what it has lacked is somewhere to put the vessels, and that constraint is now being addressed at scale.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA