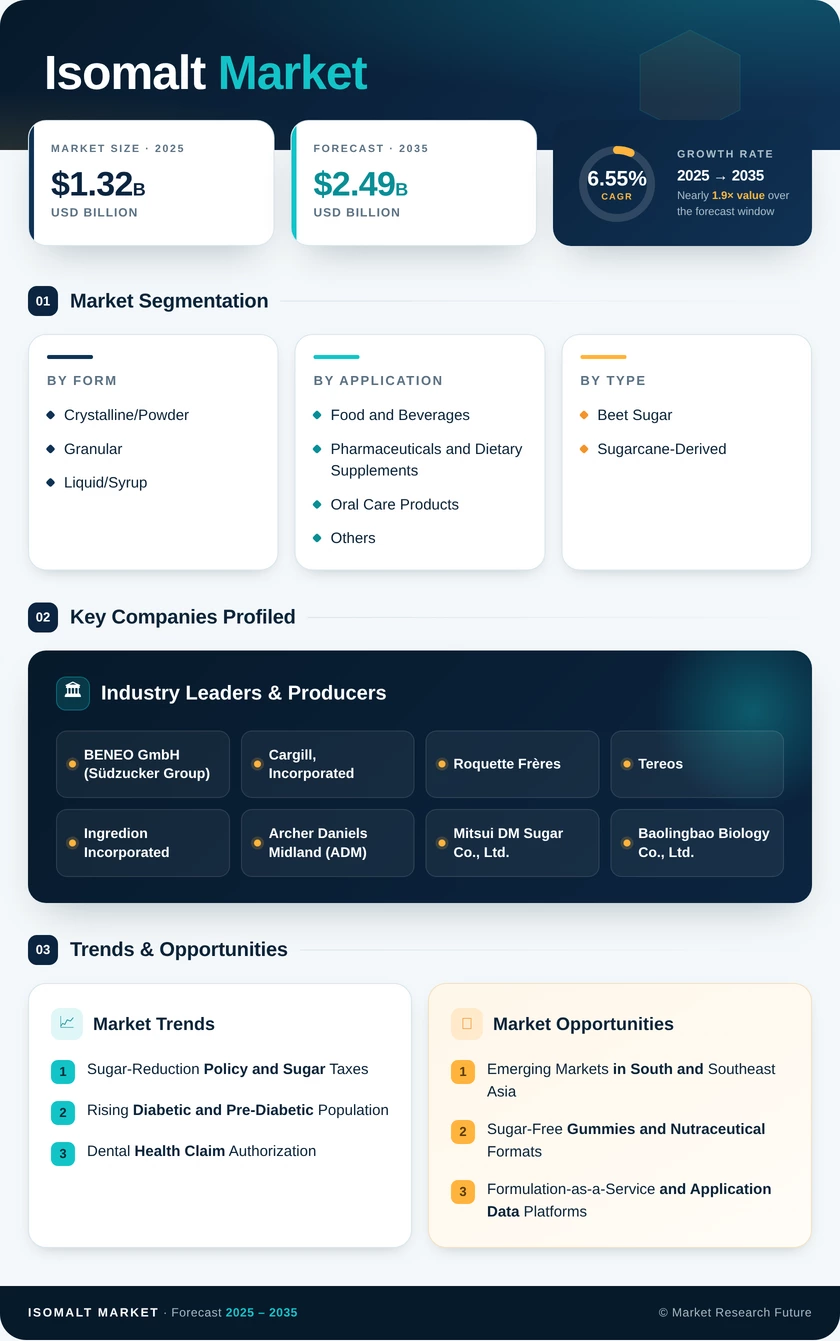
Isomalt Market (2026 - 2035)

ID: MRFR/FnB/25373-HCR 128 Pages Harshita Gorde Last Updated: October 07, 2026
Isomalt Market Size, Share, Industry Trend & Analysis Research Report By Form (Crystalline/Powder, Granular, Liquid/Syrup), By Application (Food and Beverages, Pharmaceuticals and Dietary Supplements, Oral Care Products, Others), By Raw Material Type (Beet Sugar, Sugarcane-Derived), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
Isomalt Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.55%
2025 Market SizeUSD 1.32 Billion
2035 Market SizeUSD 2.49 Billion
Key Players
BENEO GmbH
Cargill
Incorporated
Roquette Frères
Tereos
Ingredion Incorporated
Opportunities
  • Emerging Markets in South and Southeast Asia
  • Sugar-Free Gummies and Nutraceutical Formats
  • Formulation-as-a-Service and Application Data Platforms
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Form | |
    2. 2.2 By Application | |
    3. 2.3 By Raw Material Type | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Sugar-Reduction Policy and Sugar Taxes | |
    2. 4.2 Rising Diabetic and Pre-Diabetic Population | |
    3. 4.3 Dental Health Claim Authorization | |
    4. 4.4 Oral-Care Formulation Uptake | |
    5. 4.5 Heat Stability in Bakery and Hard Candy | |
    6. 4.6 Pharmaceutical Direct-Compression Demand | |
    7. 4.7 Cane-Based Capacity Diversification | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Digestive Tolerance and Laxative Labeling | |
    2. 5.2 Price Premium and Beet Feedstock Volatility | |
    3. 5.3 Competition from Allulose and High-Intensity Sweeteners | |
    4. 5.4 Concentrated Production Base | |
    5. 5.5 Category Perception Risk After Sweetener Safety Studies | |
  6. 6 Opportunities | |
    1. 6.1 Emerging Markets in South and Southeast Asia | |
    2. 6.2 Sugar-Free Gummies and Nutraceutical Formats | |
    3. 6.3 Formulation-as-a-Service and Application Data Platforms | |
    4. 6.4 Cane-Based Production Hubs in South America | |
    5. 6.5 Pediatric and Diabetic-Friendly Medicines | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Process Efficiency and Enzyme Technology | |
    2. 8.2 A Tightening Regulatory Cycle | |
    3. 8.3 Sustainability and Scope 3 Reporting | |
    4. 8.4 Blended Sweetener Systems | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Form | | |
      1. 9.1.1 Crystalline/Powder | | |
      2. 9.1.2 Granular | | |
      3. 9.1.3 Liquid/Syrup | |
    2. 9.2 By Application | | |
      1. 9.2.1 Food and Beverages | | |
      2. 9.2.2 Pharmaceuticals and Dietary Supplements | | |
      3. 9.2.3 Oral Care Products | | |
      4. 9.2.4 Others | |
    3. 9.3 By Raw Material Type | | |
      1. 9.3.1 Beet Sugar | | |
      2. 9.3.2 Sugarcane-Derived | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Isomalt Market Summary Metrics, 2025–2035 | |
  16. TABLE 2 Global Isomalt Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Global Isomalt Market, by Region, 2025 | |
  20. TABLE 6 North America Isomalt Market, by Country, 2025 | |
  21. TABLE 7 Europe Isomalt Market, by Country, 2025 | |
  22. TABLE 8 Asia-Pacific Isomalt Market, by Country, 2025 | |
  23. TABLE 9 South America Isomalt Market, by Country, 2025 | |
  24. TABLE 10 Middle East & Africa Isomalt Market, by Country, 2025 | |
  25. TABLE 11 Global Isomalt Market, by Form, 2025 | |
  26. TABLE 12 Global Isomalt Market, by Application, 2025 | |
  27. TABLE 13 Global Isomalt Market, by Raw Material Type, 2025 | |
  28. TABLE 14 Competitive Benchmarking Matrix, Global Isomalt Market | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | |
  31. TABLE 17 Segmentation Quick Reference | | LIST OF FIGURES | |
  32. FIGURE 1 Global Isomalt Market Dynamics Overview | |
  33. FIGURE 2 Isomalt Value Chain Analysis | |
  34. FIGURE 3 Porter's Five Forces Analysis, Global Isomalt Market | |
  35. FIGURE 4 Global Isomalt Market Size Trend, 2021–2035 (USD Billion) | |
  36. FIGURE 5 Global Isomalt Market Share, by Form, 2025 | |
  37. FIGURE 6 Global Isomalt Market Share, by Application, 2025 | |
  38. FIGURE 7 Global Isomalt Market Share, by Raw Material Type, 2025 | |
  39. FIGURE 8 Global Isomalt Market Share, by Region, 2025 | |
  40. FIGURE 9 Country-Level Share Comparison, by Region, 2025 | |
  41. FIGURE 10 Competitive Landscape: Estimated Revenue Share Ranges of Key Players

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By FormCrystalline/Powder, Granular, Liquid/SyrupCrystalline/Powder (50.4% share)Liquid/Syrup (7.28% CAGR)
By ApplicationFood and Beverages, Pharmaceuticals and Dietary Supplements, Oral Care Products, OthersFood and Beverages (68.5% share)Oral Care Products (8.21% CAGR)
By Raw Material TypeBeet Sugar, Sugarcane-DerivedBeet Sugar (66.6% share)Sugarcane-Derived (7.85% CAGR)
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaEurope (35.6% share)Asia-Pacific (8.57% CAGR)


Market Segmentation Overview

By Form

Sub-SegmentKey Trend
Crystalline/PowderPreferred for precise dosing and long shelf life in candy production
GranularBridges flow handling and dissolution speed for mid-scale producers
Liquid/SyrupGains share on automated, continuous production lines


Crystalline/Powder leads at a 50.4% share because hard-candy makers need solid material that stores well and doses accurately. Liquid/Syrup grows fastest at a 7.28% CAGR as large producers convert to pumpable inputs that cut labor on automated lines. Granular grades serve producers who want easier flow than fine powder without moving to liquid handling.

By Application

Sub-SegmentKey Trend
Food and BeveragesSugar-free confectionery and heat-stable bakery reformulation
Pharmaceuticals and Dietary SupplementsDirect-compression tablets and sugar-free chewables
Oral Care ProductsApproved dental health claims drive toothpaste and mouthrinse use
OthersSpecialty decoration and niche industrial uses


Food and Beverages hold a 68.5% share, led by sugar-free hard candy and gum that rely on isomalt's low hygroscopicity. Oral Care Products grow fastest at an 8.21% CAGR because regulators in the US and EU recognize tooth-friendly claims for qualifying sugar replacers. Pharmaceuticals and Dietary Supplements add steady, high-margin demand through pharmacopoeia-grade tablet excipients.

By Raw Material Type

Sub-SegmentKey Trend
Beet SugarAnchored by established European conversion capacity
Sugarcane-DerivedExpands on year-round harvests and lower tropical feedstock costs


Beet Sugar dominates with a 66.6% share, reflecting the concentration of conversion plants in Germany and wider Europe. Sugarcane-Derived output grows fastest at a 7.85% CAGR as producers seek cheaper, year-round feedstock in Asia and South America. Since the enzymatic and hydrogenation steps are identical for both, feedstock choice depends on cost and supply security rather than product quality.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.