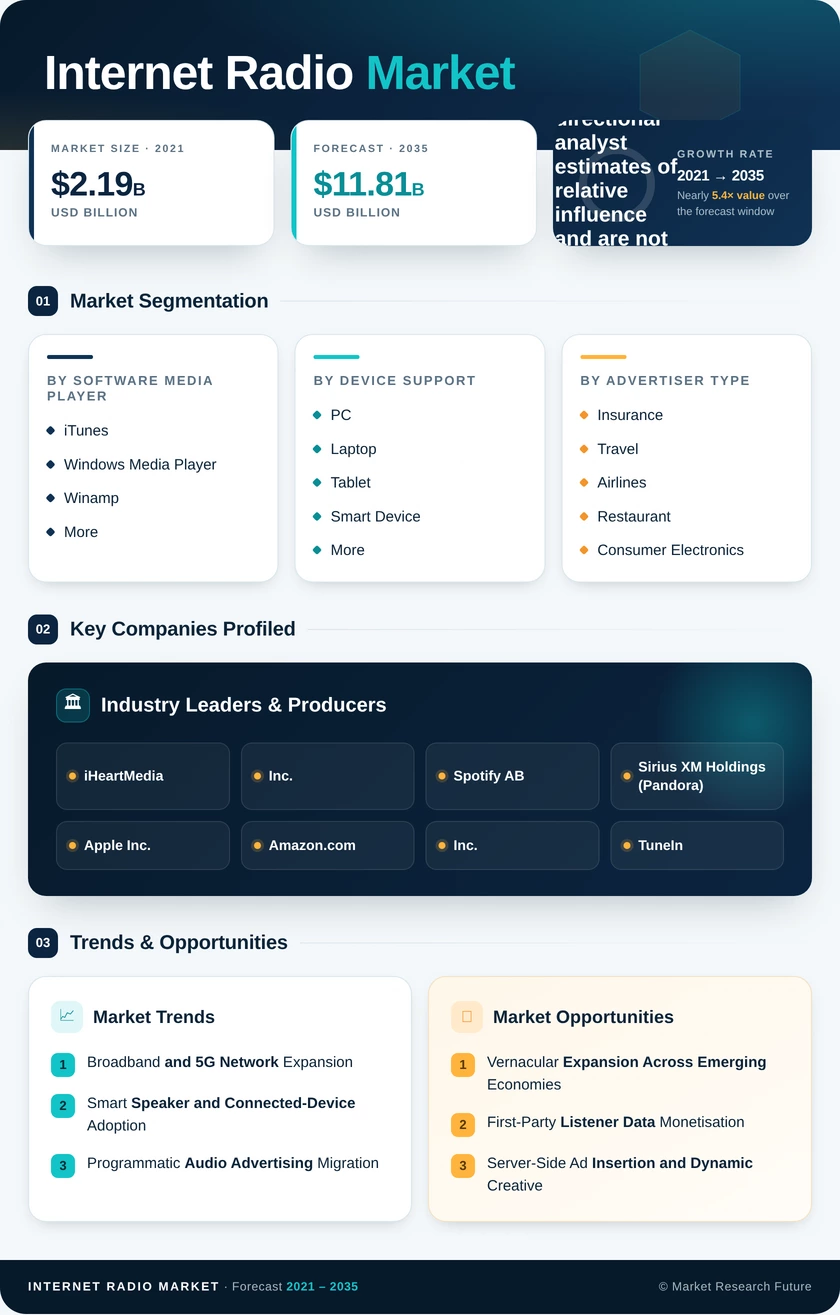
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Software Media Player | iTunes; Windows Media Player; Winamp; and More | iTunes (36.6% share, 2025) | and More (16.6% CAGR, 2026–2035) |
| By Device Support | PC; Laptop; Tablet; Smart Device; and More | PC (30.9% share, 2025) | Smart Device (21.0% CAGR, 2026–2035) |
| By Advertiser Type | Insurance; Travel and Airlines; Restaurant; Consumer Electronics; Media and Entertainment; and More | Media and Entertainment (27.5% share, 2025) | Consumer Electronics (17.2% CAGR, 2026–2035) |
Market Segmentation Overview
By Software Media Player
| Sub-Segment | Key Trend |
| iTunes | Closed-loop integration across device, operating system, and storefront sustains low churn |
| Windows Media Player | Enterprise desktop estates preserve installed base despite limited cloud synchronisation |
| Winamp | Skin customisation and local library management retain a committed enthusiast following |
| and More | HTML5 and cloud players gain share through low-latency delivery and server-side ad insertion |
iTunes leads this dimension because Apple controls playback, identity, and payment within one ecosystem, keeping higher-income listeners inside a single billing relationship. The "and More" group grows fastest as browser-based players remove installation friction entirely and support server-side ad insertion that desktop executables handle poorly. Windows Media Player survives on corporate imaging policies rather than listener preference, while Winamp's appeal remains tied to local file collections that cloud-first listeners no longer maintain.
By Device Support
| Sub-Segment | Key Trend |
| PC | Continuous background listening during working hours sustains the longest average sessions |
| Laptop | Hybrid work patterns shift listening between home rooms without breaking the stream |
| Tablet | Larger displays favour visual schedules, cover art, and interactive station browsing |
| Smart Device | Voice queries collapse discovery to a single utterance, lifting total listening hours |
| and More | Automotive head units with embedded eSIMs convert commute time into incremental reach |
PC holds the leading position on session duration, since office listening runs uninterrupted alongside other tasks in a way mobile use rarely does. Smart Device expands fastest as prominence rules force device makers to surface licensed stations in voice results, rewarding broadcasters that publish structured metadata. Tablet occupies a visual middle ground for household listening, while the "and More" category matters strategically because dashboard listening displaces AM/FM rather than cannibalising existing digital sessions.
By Advertiser Type
| Sub-Segment | Key Trend |
| Insurance | Direct-response mechanics and measurable attribution sustain steady year-round budgets |
| Travel and Airlines | Seasonal booking windows concentrate spend into geo-targeted campaign bursts |
| Restaurant | Dayparted proximity targeting aligns creative with meal-time purchase intent |
| Consumer Electronics | Product launches pair with voice-activated creative demonstrating device functionality |
| Media and Entertainment | Film, gaming, and streaming-video promotions align with leisure-oriented listening |
| and More | Retail, financial services, and public-sector campaigns broaden the demand base |
Media and Entertainment holds the largest share because its creative aligns naturally with audiences already in a content-discovery mindset, producing recall that keeps CPMs resilient through soft advertising cycles. Consumer Electronics grows fastest, driven by launch calendars that increasingly favour audio formats where voice-activated creative can demonstrate a product in the moment of exposure. Insurance and Restaurant categories provide the stable base through measurable direct-response mechanics, and Travel and Airlines contribute the seasonal peaks that lift fourth-quarter inventory pricing.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA