Internet of Everything Market (2026 - 2035)

ID: MRFR/ICT/5376-HCR 100 Pages Ankit Gupta Last Updated: September 08, 2026
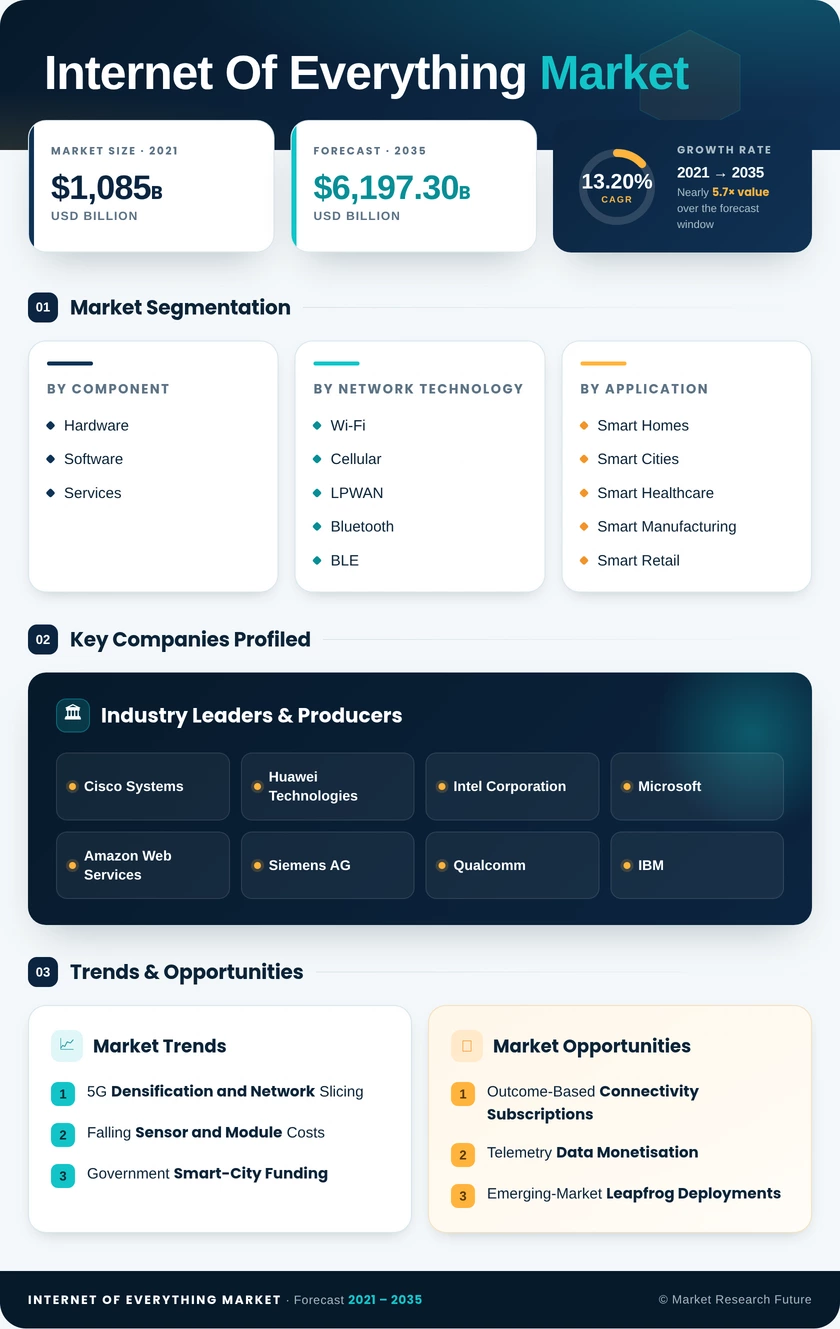
Internet of Everything Market Size, Share and Research Report By Component (Hardware, Software, and Services), By Network Technology (Wi-Fi, Cellular, LPWAN, Bluetooth and BLE, NFC, Satellite IoT, and Wired Ethernet), By Application (Smart Homes, Smart Cities, Smart Healthcare, Smart Manufacturing, and Smart Retail), By Industry Vertical (Manufacturing, Retail, BFSI, IT and Telecom, Healthcare, Energy and Utilities, and Transportation and Logistics) – Industry Forecast Till 2035.
Internet of Everything Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)13.20%
2025 Market SizeUSD 1,790.0 Billion
2035 Market SizeUSD 6,197.3 Billion
Key Players
Cisco Systems
Huawei Technologies
Intel Corporation
Microsoft
Amazon Web Services
Siemens AG
Opportunities
  • Outcome-Based Connectivity Subscriptions
  • Telemetry Data Monetisation
  • Emerging-Market Leapfrog Deployments
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Component | |
    2. 2.2 By Network Technology | |
    3. 2.3 By Application | |
    4. 2.4 By Industry Vertical | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Estimate (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 5G Densification and Network Slicing | |
    2. 4.2 Falling Sensor and Module Costs | |
    3. 4.3 Government Smart-City Funding | |
    4. 4.4 Edge Inference and On-Device Analytics | |
    5. 4.5 Industrial Predictive Maintenance ROI | |
    6. 4.6 Non-Terrestrial Network Coverage Extension | |
    7. 4.7 Regulated Remote Patient Monitoring | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Cybersecurity Exposure and Breach Liability | |
    2. 5.2 Fragmented Standards and Interoperability Gaps | |
    3. 5.3 Data Sovereignty and Cross-Border Transfer Rules | |
    4. 5.4 Integration Skills Shortage | |
    5. 5.5 Legacy Brownfield Retrofit Cost | |
  6. 6 Opportunities | |
    1. 6.1 Outcome-Based Connectivity Subscriptions | |
    2. 6.2 Telemetry Data Monetisation | |
    3. 6.3 Emerging-Market Leapfrog Deployments | |
    4. 6.4 Private Network Deployments for Industrial Sites | |
    5. 6.5 Regulated Healthcare Endpoint Expansion | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Operations and Agentic Control Loops | |
    2. 8.2 Platform Consolidation and Ecosystem Economics | |
    3. 8.3 Electrification and Grid-Edge Instrumentation | |
    4. 8.4 Sustainability Reporting as a Procurement Driver | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Hardware | | |
      2. 9.1.2 Software | | |
      3. 9.1.3 Services | |
    2. 9.2 By Network Technology | | |
      1. 9.2.1 Wi-Fi | | |
      2. 9.2.2 Cellular | | |
      3. 9.2.3 LPWAN | | |
      4. 9.2.4 Bluetooth and BLE | | |
      5. 9.2.5 NFC | | |
      6. 9.2.6 Satellite IoT | | |
      7. 9.2.7 Wired Ethernet | |
    3. 9.3 By Application | | |
      1. 9.3.1 Smart Homes | | |
      2. 9.3.2 Smart Cities | | |
      3. 9.3.3 Smart Healthcare | | |
      4. 9.3.4 Smart Manufacturing | | |
      5. 9.3.5 Smart Retail | |
    4. 9.4 By Industry Vertical | | |
      1. 9.4.1 Manufacturing | | |
      2. 9.4.2 Retail | | |
      3. 9.4.3 BFSI | | |
      4. 9.4.4 IT and Telecom | | |
      5. 9.4.5 Healthcare | | |
      6. 9.4.6 Energy and Utilities | | |
      7. 9.4.7 Transportation and Logistics | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Internet Of Everything Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Internet Of Everything Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Internet Of Everything Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Internet Of Everything Market Size, by Component, 2021–2035 (USD Billion) | |
  26. TABLE 12 Internet Of Everything Market Size, by Network Technology, 2021–2035 (USD Billion) | |
  27. TABLE 13 Internet Of Everything Market Size, by Application, 2021–2035 (USD Billion) | |
  28. TABLE 14 Internet Of Everything Market Size, by Industry Vertical, 2021–2035 (USD Billion) | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2026 | |
  30. TABLE 16 Company Profiles – Key Players | |
  31. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 | |
  32. TABLE 18 Report Scope & Methodology Summary | |
  33. TABLE 19 Detailed Sources and Citations | |
  34. TABLE 20 Segmentation Quick Reference Matrix | | LIST OF FIGURES | |
  35. FIGURE 1 Internet Of Everything Market Dynamics – Drivers, Restraints and Opportunities | |
  36. FIGURE 2 Industry Value Chain Analysis | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  39. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  40. FIGURE 6 Market Share by Component, 2024 vs 2035 | |
  41. FIGURE 7 Market Share by Network Technology, 2024 vs 2035 | |
  42. FIGURE 8 Market Share by Application, 2024 vs 2035 | |
  43. FIGURE 9 Market Share by Industry Vertical, 2024 vs 2035 | |
  44. FIGURE 10 Regional Revenue Share, 2025 | |
  45. FIGURE 11 Regional CAGR Comparison, 2026–2035 | |
  46. FIGURE 12 Country-Level Share within Asia-Pacific, 2025 | |
  47. FIGURE 13 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  48. FIGURE 14 Strategic Positioning Matrix – Key Vendors

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentHardware; Software; ServicesHardware (41.7% share, 2024)Services (13.25% CAGR)
By Network TechnologyWi-Fi; Cellular; LPWAN; Bluetooth and BLE; NFC; Satellite IoT; Wired EthernetWi-Fi (38.5% share, 2024)Cellular – 5G (13.74% CAGR)
By ApplicationSmart Homes; Smart Cities; Smart Healthcare; Smart Manufacturing; Smart RetailSmart Cities (25.3% share, 2024)Smart Healthcare (13.62% CAGR)
By Industry VerticalManufacturing; Retail; BFSI; IT and Telecom; Healthcare; Energy and Utilities; Transportation and LogisticsManufacturing (20.9% share, 2024)Healthcare (13.82% CAGR)


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
HardwareModule deflation expands viable use cases as installed cost falls below payback thresholds
SoftwareDevice management and analytics platforms consolidate toward hyperscaler-anchored ecosystems
ServicesManaged connectivity and outcome-based contracting convert one-time margin into recurring revenue


Hardware holds the largest component share at 41.7% because every deployment begins with sensors, microcontrollers, and connectivity modules, and refresh cycles sustain replacement volume independent of new projects. Services grow fastest at a 13.25% CAGR as enterprises conclude that operating heterogeneous device estates across multiple jurisdictions is not a core competency, pushing orchestration and integration to specialist providers. Software occupies the middle position, monetising data that hardware generates while inheriting the consolidation pressure affecting all platform layers.

By Network Technology

Sub-SegmentKey Trend
Wi-FiWi-Fi 7 throughput gains slow cellular substitution inside campus environments
CellularNetwork slicing and Release 18 non-terrestrial support extend addressable use cases
LPWANMulti-year battery life sustains dominance in metering and asset tracking
Bluetooth and BLESub-USD-2 modules drive proximity, wearable and indoor positioning volume
NFCContactless authentication anchors payment and access-control endpoints
Satellite IoTConstellation pricing brings remote-asset telemetry within commercial reach
Wired EthernetPoE and deterministic control retain industrial installations resistant to wireless


Wi-Fi leads at 38.5% share on unlicensed spectrum economics and installed access-point density, and Wi-Fi 7's throughput headroom defends that position within buildings. Cellular grows fastest — 13.74% for 5G — because wide-area mobility, slice-level service guarantees and standardised satellite roaming address requirements Wi-Fi structurally cannot meet. LPWAN and Wired Ethernet persist in their respective niches: the former wherever a decade of battery life outweighs bandwidth, the latter wherever control loops tolerate no jitter.

By Application

Sub-SegmentKey Trend
Smart HomesMatter interoperability reduces multi-vendor friction in consumer installations
Smart CitiesMunicipal procurement aggregates traffic, lighting and waste telemetry into single tenders
Smart HealthcareReimbursement codes let providers fund devices from clinical rather than IT budgets
Smart ManufacturingPredictive maintenance payback clears capital committees without subsidy
Smart RetailInventory accuracy and shrink reduction anchor the deployment case


Smart Cities dominate at 25.3% share because municipal contracts bundle multiple telemetry categories into procurements far larger than any single enterprise deployment. Smart Healthcare advances fastest at 13.62% as reimbursement pathways widen and virtual-ward programmes demonstrate readmission reductions that justify device spend clinically. Smart Manufacturing sits between them on absolute value, growing steadily rather than sharply because retrofit timing follows plant turnaround schedules rather than technology availability.

By Industry Vertical

Sub-SegmentKey Trend
ManufacturingCondition monitoring and quality analytics deliver sub-eighteen-month payback
RetailShrink reduction and real-time inventory visibility drive endpoint density
BFSIUsage-based insurance and branch telemetry extend connectivity into financial workflows
IT and TelecomNetwork monitoring and edge hosting expand with distributed compute footprints
HealthcareConnected diagnostics and cold-chain compliance scale under regulatory clearance
Energy and UtilitiesMetering mandates and grid-edge visibility set deployment timing
Transportation and LogisticsFleet telematics and cargo integrity monitoring reduce claims exposure


Manufacturing anchors vertical spending at 20.9% share, built on two decades of predictive maintenance and quality analytics investment that survives economic cycles because returns are measurable in avoided downtime. Healthcare grows fastest at a 13.82% CAGR as connected inhalers, glucose monitors, and cold-chain sensors transition from pilot to standard of care under widening reimbursement. Energy and Utilities remain the most policy-sensitive vertical, where metering mandates rather than internal payback calculations determine when deployments proceed.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.