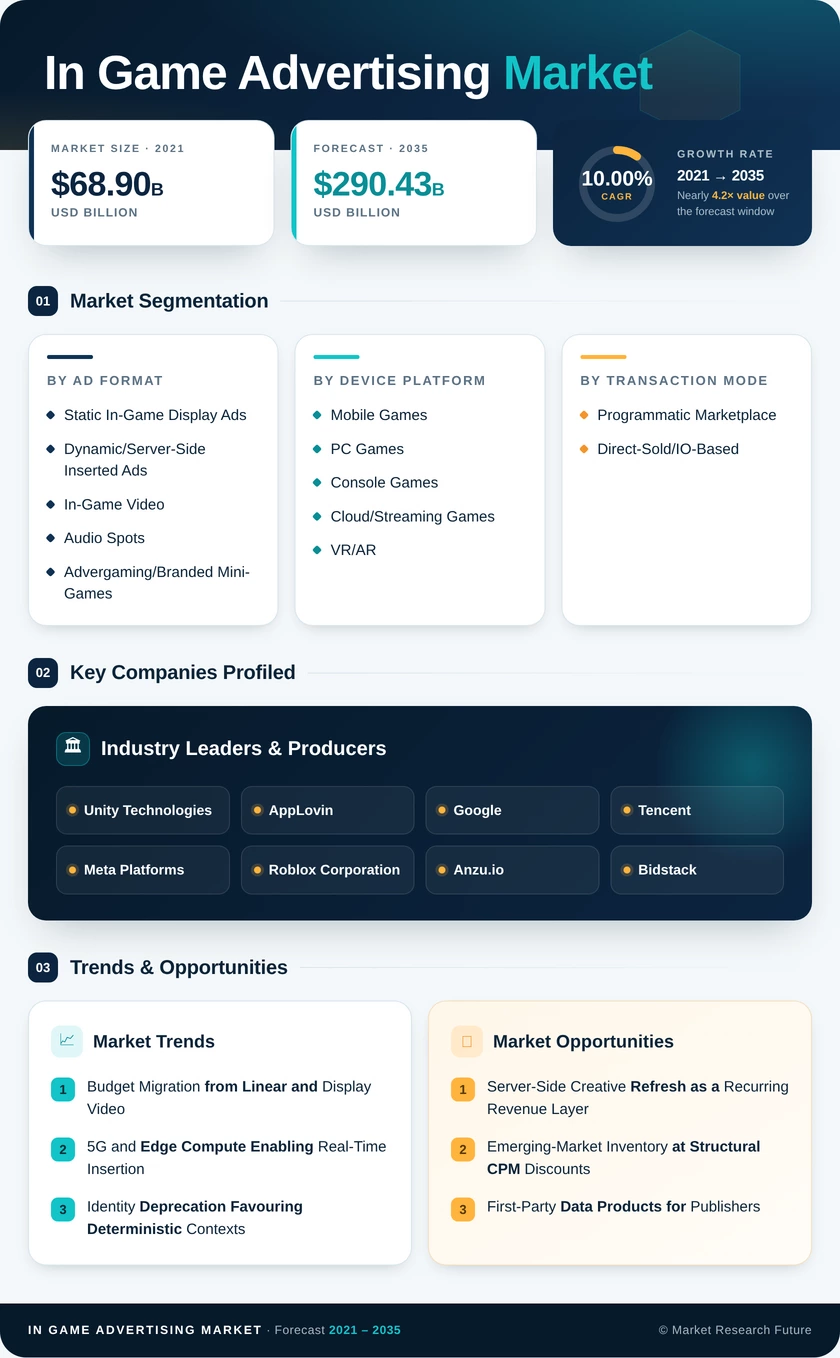
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Ad Format | Static In-Game Display Ads; Dynamic/Server-Side Inserted Ads; In-Game Video and Audio Spots; Advergaming/Branded Mini-Games; Rewarded/Playable and Other Formats | Static In-Game Display Ads (41.58% share, 2025) | Rewarded/Playable and Other Formats (10.89% CAGR, 2026–2035) |
| By Device Platform | Mobile Games; PC Games; Console Games; Cloud/Streaming Games; VR/AR and Metaverse Environments | Mobile Games (USD 48.90 Billion, 2025) | Cloud/Streaming Games (10.85% CAGR, 2026–2035) |
| By Transaction Mode | Programmatic Marketplace; Direct-Sold/IO-Based | Direct-Sold/IO-Based (52.90% share, 2025) | Programmatic Marketplace (11.30% CAGR, 2026–2035) |
Market Segmentation Overview
By Ad Format
| Sub-Segment | Key Trend |
| Static In-Game Display Ads | Texture-level placements remain the default entry point for new advertisers. |
| Dynamic/Server-Side Inserted Ads | Creative swaps without client patches extend monetizable title lifespan. |
| In-Game Video and Audio Spots | Transferable video assets shorten creative production timelines. |
| Advergaming/Branded Mini-Games | Bespoke builds command premium CPMs but limit campaign scale. |
| Rewarded/Playable and Other Formats | Explicit value exchange sustains completion rates above other formats. |
Static In-Game Display Ads lead at 41.58% because a billboard or wall texture demands almost no engine work and delivers forecastable impressions, which suits media planners running annual commitments. Rewarded/Playable and Other Formats grow fastest at 10.89% since players accept advertising they opted into for in-game currency, sidestepping the backlash that has constrained forced formats on console. Dynamic/Server-Side Inserted Ads occupy the strategic middle, giving publishers static-like operational simplicity while letting advertisers refresh creative mid-flight — a workflow legacy client-side pipelines could not support.
By Device Platform
| Sub-Segment | Key Trend |
| Mobile Games | Reward mechanics embedded natively in free-to-play design loops |
| PC Games | Long sessions and competitive viewership sustain premium pricing. |
| Console Games | Platform holders proceed cautiously after visible community pushback. |
| Cloud/Streaming Games | Server-side rendering makes insertion and verification structurally simple. |
| VR/AR and Metaverse Environments | Experiential brand showrooms attract automotive and consumer goods budgets. |
Mobile Games generate the largest absolute revenue at USD 48.90 billion because freemium economics made advertising a design primitive rather than an afterthought. At the same time, PC Games hold 38.10% on the strength of session duration and esports-adjacent brand familiarity. Cloud/Streaming Games expand fastest at 10.85%: when the game already renders on a server, real-time ad decisioning requires no client SDK and viewability can be verified at source. Console Games trail in growth despite large audiences, since platform holders remain wary of the review-bombing risk demonstrated in recent AAA experiments.
By Transaction Mode
| Sub-Segment | Key Trend |
| Programmatic Marketplace | OpenRTB schema extensions now describe 3D object placements natively |
| Direct-Sold/IO-Based | Custom quests and branded virtual goods require studio collaboration. |
Direct-Sold/IO-Based deals retain 52.90% share because the highest-value executions — branded in-world quests, co-designed virtual items, narrative integrations — depend on creative workshops between advertiser and studio that no automated pipe replicates. Programmatic Marketplace inventory compounds faster at 11.30% as bid-request schemas gained fidelity for 3D placements and unified frequency capping became available across titles, eliminating the manual insertion-order overhead that limited mid-market buyers. The dimension is heading toward a barbell structure: tentpole storytelling sold directly, and the long tail of standardized inventory traded on exchanges.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA