In building Wireless Market (2026 – 2035)

In-Building Wireless Market Size, Share and Research Report By Component Type (Distributed Antenna Systems, Small Cells, Antenna, Repeaters, Cables), By Technology (4G/LTE, 5G NR, Wi-Fi 6/6E, Wi-Fi 7), By Frequency Band (Less Than 1 GHz, 1–6 GHz, More Than 6 GHz), By End-User Industry (Commercial, Industrial, Residential, Public-Safety and Government) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/8999-HCR 200 Pages Ankit Gupta Last Updated: September 15, 2026
In building Wireless Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.00%
Key Players
CommScope
Corning
JMA Wireless
SOLiD
Ericsson
Nokia
Opportunities
  • Wi-Fi 7 and Cellular Convergence Platforms
  • Smart-Building IoT as an Anchor Application
  • Emerging-Market Urbanization and New Construction

In building Wireless Market Summary

The In-building Wireless Market was valued at USD 24.10 Billion in 2025 and is projected to reach USD 26.96 Billion in 2026, growing to USD 74.77 Billion by 2035 at a CAGR of 12.00% during the forecast period (2026–2035). This trajectory reflects the reality that roughly 80% of all mobile data traffic now originates or terminates inside buildings, yet indoor coverage remains the weakest link in carrier networks [1]. National 5G deployment mandates — including the FCC's updated spectrum-sharing framework and the EU's Digital Decade targets — are accelerating capital flows into the In-building Wireless Market as carriers and property owners seek to close persistent coverage gaps [2].

A generational technology shift is underway. Passive analog repeater architectures installed during the 3G era are giving way to digital, software-defined platforms that converge cellular, Wi-Fi 6E, and private 5G on a single fiber backbone. The U.S. Department of Commerce allocated over USD 1.5 billion between 2023 and 2025 to broadband infrastructure grants that explicitly include indoor connectivity requirements for hospitals, transit hubs, and public-safety buildings [3]. This injection of public capital is drawing matching private investment and reshaping the competitive field within the In-building Wireless Market.

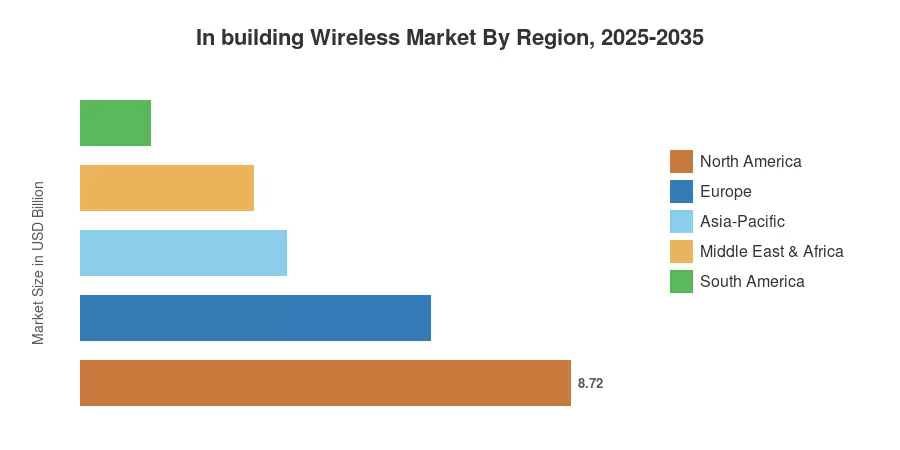
North America remained the dominant region in 2025 with a 36.2% revenue share, anchored by carrier-driven stadium, airport, and enterprise deployments across the United States. Asia-Pacific is the fastest-growing region, registering a projected CAGR of 15.20% through 2035, propelled by China's aggressive smart-building programs and India's rapid 5G indoor rollouts. Europe held the second-largest share at 25.8%, supported by EU co-funding mechanisms for connected hospitals and rail stations. The decade ahead will see the In-building Wireless Market evolve from a carrier-coverage remedy into a platform layer for IoT, positioning, and real-time analytics inside built environments.


Key Report Takeaways

• By Component Type

  • Distributed Antenna Systems accounted for the largest component share in 2025, generating 40.3% of total In-building Wireless Market revenue.
  • Small Cells are the fastest-expanding component category, forecast to grow at a CAGR of 14.60% through 2035 as enterprises adopt private-network architectures.

• By Technology

  • 4G/LTE technology dominated in-building deployments in 2025 with an estimated 59.7% share of the In-building Wireless Market.
  • 5G NR is advancing at a projected 15.20% CAGR, driven by venue operators upgrading to high-capacity indoor radios.

• By Region

  • North America led the global In-building Wireless Market in 2025, commanding a 36.2% revenue share.
  • Asia-Pacific is projected to register the fastest CAGR of 15.20% through 2035, underpinned by smart-city mandates across China and India.


Market Size and Forecast (2021–2035)

Market Research Future's sizing model triangulates operator capital-expenditure disclosures, vendor shipment data, and building-permit analytics across 45 countries. Historical figures (2021–2024) draw on audited company reports, while the forecast period (2026–2035) applies a demand-side regression calibrated to 5G spectrum-auction timelines and commercial real-estate construction starts.

In building Wireless Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
5G SA Core & Mid-Band Expansion ~2.8% Global Short-term (≤2 yr)
Smart-Building Codes & Green Mandates ~2.2% Europe, Asia-Pacific Medium-term (2–4 yr)
Public-Safety Communication Regulations ~1.5% North America, Europe Short-term (≤2 yr)
Enterprise Private-Network Adoption ~1.8% North America, Asia-Pacific Medium-term (2–4 yr)
Neutral-Host & Shared-Infrastructure Models ~1.4% Global Medium-term (2–4 yr)
Stadium & Large-Venue Densification ~1.0% North America, Europe Short-term (≤2 yr)
AI-Driven Network Planning & Optimization ~0.9% Global Long-term (≥4 yr)


5G SA Core and Mid-Band Spectrum Rollouts

Between 2021 and 2025, mobile operators globally have committed over USD 120 billion in mid-band (3.3-4.2 GHz) spectrum auctions, and the indoor propagation issues at these frequencies make dedicated in-building radio infrastructure a must-have, not a nice-to-have [2]. The move from 5G Non-Standalone to Standalone core designs enables network slicing, which is monetized by building owners through differential SLAs to tenants. The 2024 FCC amendment to CBRS rules has removed further restrictions to indoor shared-spectrum deployments, further spurring an enterprise small-cell installation boom across healthcare campuses and logistics warehouses in the United States [12].


Public-Safety Communication Mandates

In North America and the EU, fire code rules currently dictate minimum in-building signal levels for first-response radio systems. International Fire Code Section 510 and NFPA 1225 require that buildings over a particular size have signal enhancement systems and that they are checked at the time of occupancy [7]. In the U.S. alone, approximately 1.2 million commercial buildings remain without adequate public safety coverage, producing a continuing backlog of installations that feed the In-building Wireless Market year after year.


Enterprise Private-Network Adoption

Ports, manufacturing facilities, and hospital systems are building private 5G networks to enable ultra-reliable, low-latency applications such as autonomous guided vehicles and remote surgical monitoring. By the end of 2024, Germany’s “5G Campus” licensing regime had awarded more than 350 local network licenses, each including in-building radio equipment . Such private deployments allow facilities to skip carrier schedules and have control over spectrum, security, and quality of service – and are spurring demand for specialized indoor antenna arrays and edge-computing gateways.


Neutral-Host Shared-Infrastructure Models

Neutral-host platforms permit numerous carriers to share in-building systems, leading to reductions in per-operator costs of as much as 40% according to industry benchmarks . This model is attractive to real estate owners, such as airports, shopping malls, and multi-tenant office towers, because it turns connectivity infrastructure into a landlord-provided amenity. The strategy is gaining ground in the In-building Wireless Market as carriers are under margin pressure and looking for OPEX-light coverage expansion pathways, particularly in mid-tier markets where the economics of the single operator do not support solo construction.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High Upfront Deployment Costs ~–1.6% Global Short-term (≤2 yr)
Complex Multi-Stakeholder Coordination ~–1.2% Global Medium-term (2–4 yr)
RF Interference in Dense Environments ~–0.8% Urban markets Long-term (≥4 yr)
Permitting & Building-Code Fragmentation ~–0.7% Europe, South America Medium-term (2–4 yr)
Carrier CAPEX Retrenchment Cycles ~–0.5% North America, Europe Short-term (≤2 yr)


High Upfront Deployment Costs

A full-scale distributed antenna placement in a 500,000 sq ft commercial property can cost between USD 1.5 million and USD 4 million, depending on building construction materials and the number of carrier frequencies supported . Retrofitting older concrete-and-steel structures involves extra costs for structural study and cabling. While the neutral-host models help to offset some of the expense, for many mid-market property owners, the capital investment remains expensive, leading to the delay or down-scoping of projects that would otherwise contribute to the expansion of the In-building Wireless Market.


Complex Multi-Stakeholder Coordination

An in-building wireless project typically requires alignment among the building owner, one or more mobile operators, the system integrator, the equipment vendor, and often a public-safety authority having jurisdiction. This multi-party negotiation process can stretch project timelines from six months to over eighteen months, especially when carrier backhaul provisioning and landlord lease negotiations stall . The coordination burden is a well-documented friction point in the In-building Wireless Market, and it disproportionately affects mid-tier venues where no single stakeholder has the financial incentive to drive the project forward unilaterally.


In building Wireless Market Opportunities

Wi-Fi 7 and Cellular Convergence Platforms

The arrival of Wi-Fi 7 (IEEE 802.11be) introduces multi-link operation and 320 MHz channels that rival private 5G throughput, creating an opening for converged platforms that manage both protocols through a unified controller. Equipment vendors offering integrated cellular-and-Wi-Fi hardware on a single fiber-optic backbone are positioned to capture greenfield commercial developments that want one infrastructure investment rather than two.

Smart-Building IoT as an Anchor Application

Indoor connectivity is no longer just about voice and data bars. Building-management platforms now route HVAC telemetry, occupancy sensing, and digital-twin feeds over the same in-building radio layer that serves smartphones. The global smart-building automation sector is projected to exceed USD 130 billion by 2030, and every sensor-dense deployment requires reliable low-latency indoor wireless — a tailwind that extends the addressable scope of the In-building Wireless Market beyond traditional carrier economics [6].

Emerging-Market Urbanization and New Construction

Rapid urbanization in Southeast Asia, the Middle East, and Sub-Saharan Africa is producing millions of square meters of new commercial floor space annually. These greenfield buildings can integrate in-building systems at the construction stage — at roughly 30% lower cost than retrofits — making them attractive early adopters.

Data Monetization Through Indoor-Location Analytics

In-building radio infrastructure generates granular foot-traffic and device-density data that retailers, airports, and healthcare campuses can monetize for wayfinding, targeted advertising, and operational optimization. Location-analytics revenues are growing at over 20% annually, and embedding positioning capabilities into DAS and small-cell networks creates a recurring revenue stream that improves the ROI calculus for property owners investing in the In-building Wireless Market.

As-a-Service and Managed Connectivity Models

A shift from capital-expenditure to operational-expenditure models is lowering the entry barrier for building owners. Managed-service providers now offer in-building connectivity as a monthly subscription, bundling equipment, monitoring, and software updates. This approach particularly resonates in the hospitality and co-working segments, where tenants rotate frequently, and infrastructure flexibility matters more than ownership.


In building Wireless Market Future Outlook

AI-Driven Network Automation and Self-Optimizing Buildings

Machine-learning algorithms will increasingly manage RF planning, interference mitigation, and capacity allocation inside buildings without human intervention. A recent market report projects that by 2030, 60% of large enterprise indoor networks will incorporate closed-loop AI optimization, cutting operational costs by up to 25% . This shift from static RF design to continuous, data-driven tuning raises system performance while reducing the specialized labor that currently constrains rapid deployment.

Open-RAN and Disaggregated Indoor Architectures

The O-RAN Alliance's indoor-specific work groups are developing interoperable small-cell and DAS interfaces that decouple hardware from software, breaking vendor lock-in. Operators such as Rakuten, Dish Network, and 1&1 have committed to Open-RAN principles, and their indoor strategies will pressure incumbents to open their platforms. By the early 2030s, disaggregated in-building radio stacks could reduce equipment costs by 20–30% and give building owners greater flexibility to swap components without full system replacement [18].

Energy Efficiency and ESG-Aligned Deployments

Sustainability is becoming a procurement criterion for the In-building Wireless Market. Next-generation radio units consume up to 40% less power per gigabit than legacy DAS head-ends, and equipment vendors are beginning to publish product-level carbon-footprint disclosures aligned with SBTi guidelines [19]. The EU's Energy Efficiency Directive revision, effective 2025-2026, impose energy-performance benchmarks on building technical systems — including telecommunications infrastructure — incentivizing low-power designs.

Convergence with Indoor Positioning and Digital-Twin Ecosystems

High-accuracy indoor positioning (sub-meter precision) enabled by 5G NR positioning reference signals and ultra-wideband integration is transforming in-building wireless networks from connectivity pipes into spatial-intelligence platforms. Airports, logistics centers, and hospitals are layering asset-tracking, wayfinding, and crowd-analytics applications on top of the same radio infrastructure. The IEA estimates that digital-twin-enabled building management could reduce commercial-building energy consumption by 10–15% by 2035, creating a direct link between indoor connectivity investment and sustainability outcomes [20].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 36.2% share (2025) Public-safety mandates, carrier densification, stadium connectivity
Europe USD 6.22 Billion (2025) EU Digital Decade, green-building codes, rail connectivity
Asia-Pacific 15.20% CAGR (2026–2035) 5G build-out, smart-city programs, new commercial construction
South America 5.2% share (2025) Carrier network extension, airport modernization
Middle East & Africa 12.80% CAGR (2026–2035) Mega-project developments, tourism infrastructure
Total USD 24.10 Billion (2025) —

The In-building Wireless Market spans five major regions with distinct demand drivers, regulatory frameworks, and maturity levels. North America leads in deployed base and average system complexity, while Asia-Pacific is closing the gap at an accelerated pace.


North America

Country Key Metric Key Driver
United States 78.5% of regional share FCC mandates, enterprise private 5G
Canada CAGR 11.40% Transit and healthcare upgrades
Mexico USD 0.52 Billion (2025) Airport and commercial-mall expansion


The United States dominates North America's In-building Wireless Market, driven by stringent IFC Section 510 compliance requirements and aggressive carrier densification in Tier-1 metro areas. Canada's federal government earmarked CAD 800 million for rural and indoor broadband under its Universal Broadband Fund, while Mexico's Aeropuertos del Sureste group initiated DAS modernization across 12 airport terminals in 2024 [7] [12].

Europe

Country Key Metric Key Driver
Germany 22.4% of regional share 5G Campus licenses, Industry 4.0
United Kingdom CAGR 11.80% Shared Rural Network extension indoors
France USD 0.89 Billion (2025) Grand Paris Express transit connectivity
Italy CAGR 10.90% Hospitality-sector upgrades
Spain 8.1% of regional share Smart-tourism venues
Nordic Countries USD 0.58 Billion (2025) Healthcare digitalization
Russia CAGR 9.20% Metro and commercial builds
Rest of Europe 11.3% of regional share Mixed commercial retrofit


Germany's 5G Campus licensing framework has made it the In-building Wireless Market leader in Europe, with over 350 active private-network permits by late 2024 concentrated in automotive and logistics sectors. The UK's Building Safety Act introduced connectivity provisions for high-rise structures, while France's Grand Paris Express — a EUR 36 billion transit project — includes integrated in-tunnel and in-station wireless coverage requirements [16].

Asia-Pacific

Country Key Metric Key Driver
China 38.2% of regional share Smart-building mandates, carrier CAPEX
India CAGR 16.50% 5G indoor rollout, commercial construction
Japan USD 0.92 Billion (2025) Venue connectivity for events, rail stations
South Korea 14.8% of regional share KT and SKT indoor 5G
ASEAN CAGR 15.80% Airport and hospitality growth
Rest of Asia-Pacific 7.5% of regional share Mixed enterprise demand


China's Ministry of Industry and Information Technology mandated indoor 5G coverage in all newly constructed Grade-A commercial buildings from 2024, creating a structural demand floor that sustains the In-building Wireless Market across the region. India's Reliance Jio and Bharti Airtel each committed over USD 2 billion to indoor 5G infrastructure through 2027, while Japan invested heavily in venue connectivity ahead of international sporting events and Expo 2025 Osaka .

South America

Country Key Metric Key Driver
Brazil 62.0% of regional share Airport and commercial expansion
Argentina CAGR 11.50% Urban commercial retrofit
Rest of South America USD 0.18 Billion (2025) Mining and hospitality


Brazil anchors South America's demand through modernization of its 35 major airport terminals and rapid shopping-center development in São Paulo, Rio de Janeiro, and secondary metros. Regulatory pressure from ANATEL to guarantee indoor emergency-call quality is pushing building owners toward professional in-building solutions rather than consumer-grade repeaters [16].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 31.5% of regional share NEOM, giga-projects
UAE CAGR 13.40% Smart-city programs, tourism venues
South Africa USD 0.19 Billion (2025) Commercial real-estate upgrades
Egypt CAGR 12.10% New Administrative Capital
Rest of MEA 22.0% of regional share Mixed infrastructure


Saudi Arabia's Vision 2030 giga-projects — including NEOM, The Red Sea, and Diriyah Gate — each specify fully integrated indoor wireless infrastructure from the design phase, supporting the In-building Wireless Market through massive greenfield construction. The UAE's Smart Dubai initiative mandates high-density indoor coverage in all government and commercial properties, and Egypt's New Administrative Capital includes over 20 million square meters of connectivity-ready office space [3].


In building Wireless Market By Region, 2025-2035

In building Wireless Market Segmentation

By Component Type

Segment Key Metric Primary Demand Driver
Distributed Antenna Systems 40.3% share (2025) Legacy venue deployments, public-safety mandates
Small Cells CAGR 14.60% Private 5G enterprise networks
Antenna USD 3.37 Billion (2025) Passive infrastructure refresh
Repeaters 8.9% share (2025) SMB and residential coverage extension
Cables CAGR 10.20% Fiber-to-the-antenna upgrades


The In-building Wireless Market remains anchored by Distributed Antenna Systems, which serve large-footprint venues such as airports, convention centers, and hospital campuses where multi-carrier, multi-band coverage is non-negotiable. DAS installations tend to be capital-intensive but deliver the broadest indoor propagation, making them the default choice for venues exceeding 200,000 square feet. Public-safety signal mandates reinforce this dominance because fire-code compliance typically requires a DAS-grade system rather than a small-cell overlay.

Small Cells represent the fastest-growing component segment in the In-building Wireless Market, propelled by enterprise private 5G deployments that demand dense, low-latency radio access in manufacturing plants, warehouses, and healthcare facilities. Unlike DAS, small cells operate as self-contained base stations with integrated backhaul intelligence, making them easier to deploy in modular configurations. Their unit cost has declined roughly 15% between 2022 and 2025, further accelerating adoption among mid-market enterprises.

By Technology

Segment Key Metric Primary Demand Driver
4G/LTE 59.7% share (2025) Installed-base incumbency, broad device support
5G NR CAGR 15.20% Carrier densification, URLLC use cases
Wi-Fi 6/6E USD 4.15 Billion (2025) Enterprise LAN convergence
Wi-Fi 7 CAGR 18.50% Multi-link operation, greenfield campuses


4G/LTE retains the largest technology share because the global installed base of in-building systems was overwhelmingly provisioned for LTE bands, and most carrier traffic still runs on 4G cores even where 5G overlay exists. Rip-and-replace economics favor incremental upgrades — adding a 5G radio head to an existing DAS rather than building anew — which sustains the LTE share through mid-decade.

5G NR is the fastest-growing technology segment, fueled by carrier 5G SA rollouts that unlock network slicing, ultra-reliable low-latency communication, and enhanced positioning inside buildings. Venue owners that host high-density events — sports arenas, exhibition halls, transportation hubs — are prioritizing 5G upgrades to meet user expectations for multi-gigabit throughput on personal devices.

By Frequency Band

Segment Key Metric Primary Demand Driver
1–6 GHz (Mid-Band) 62.1% share (2025) 5G C-band indoor coverage
Less Than 1 GHz (Low-Band) USD 3.62 Billion (2025) Building penetration, IoT backhaul
More Than 6 GHz (mmWave/High-Band) CAGR 15.30% Ultra-high-capacity venue deployments


The 1–6 GHz (Mid-Band) segment leads the market with a dominant 62.1% share in 2025, driven heavily by operator deployments of 5G C-band spectrum to balance broad indoor coverage requirements with high-speed data capacity. Meanwhile, the More Than 6 GHz (mmWave/High-Band) segment represents the fastest-growing frequency band, projecting a market-leading CAGR of 15.30%, fueled by increasing demand for ultra-high-capacity millimeter-wave solutions across high-density venues, stadiums, and specialized enterprise environments.

By End-User Industry

Segment Key Metric Primary Demand Driver
Commercial 47.9% share (2025) Office, retail, hospitality connectivity
Industrial CAGR 14.10% Industry 4.0, private 5G in factories
Residential USD 3.13 Billion (2025) Multi-dwelling unit coverage extension
Public-Safety and Government 9.4% share (2025) Fire-code mandates, mission-critical comms


The Commercial segment leads the In-Building Wireless Market by end-user industry with a dominant 47.9% share in 2025, driven by surging tenant and customer demand for seamless cellular connectivity across enterprise office spaces, retail complexes, and hospitality venues. Meanwhile, the Industrial segment represents the fastest-growing end-user sector, projecting a market-leading CAGR of 14.10%, propelled by the rapid rollout of Industry 4.0 automation, smart manufacturing protocols, and dedicated private 5G networks across factory floors and logistics hubs.


Competitive Benchmarking

The In-building Wireless Market exhibits medium concentration, with the top five vendors capturing an estimated 48–55% of global revenue. Fragmentation increases outside North America, where regional integrators and local antenna manufacturers hold meaningful share in Asia-Pacific and the Middle East. Vendor consolidation has accelerated since 2023 as major players pursue end-to-end portfolios that span antenna hardware, digital transport, cloud-based management, and professional services .

Company Est. Revenue Share Range Key Offerings Strategic Positioning
CommScope ~10–14% ERA digital DAS, fiber-to-the-antenna, OneCell small cells Full-stack venue connectivity leader
Corning ~8–12% Evolv optical DAS, SpiderCloud small cells Fiber-native indoor architecture
JMA Wireless ~5–8% TEKO distributed massive MIMO, XRAN platform Open-RAN indoor pioneer
SOLiD ~4–7% ALLIANCE digital DAS, neutral-host platform Multi-operator shared infrastructure
Ericsson ~5–8% Radio Dot System, indoor 5G small cells Carrier ecosystem integration
Nokia ~4–7% Indoor small cells, Modular Private Wireless Private-network and campus solutions
Comba Telecom ~3–5% Multi-band DAS, fiber distribution systems Cost-competitive Asia-Pacific reach
Dali Wireless ~2–4% Digital DAS, multi-band repeaters Software-defined signal distribution
Cel-Fi (Nextivity) ~2–4% Smart signal boosters, QUATRA small-cell system SMB and residential coverage
Cobham Advanced Electronic Solutions ~2–3% Public-safety DAS, bi-directional amplifiers First-responder communication focus


Recent News & Developments

  • CommScope (February 2024): Expanded its ERA® Digital DAS ecosystem by introducing high-capacity optical expansion units, enabling enterprises to simplify indoor 5G C-band signal transport while reducing head-end footprint and power consumption across large venues.
  • Ericsson (February 2024): Unveiled its indoor 5G precision location software suite integrated into the Ericsson Radio Dot System, enabling sub-meter indoor positioning alongside multi-carrier 5G connectivity for enterprise digital-twin applications.
  • FCC (September 2024): Issued Enforcement Bureau Order DA 24-892 terminating investigations into carrier cybersecurity and cloud vendor data protection practices, reinforcing data compliance standards across communications infrastructure.


  • SOLiD (August 2023): Opened a North American engineering and support center in Dallas, Texas, to accelerate DAS deployments for healthcare and hospitality sectors [Ref: SOLiD Press Release].


In building Wireless Market Report Scope

Parameter Detail
Market Scope Global In-building Wireless Market — hardware, software, and services
Study Period 2021–2035
CAGR Window 2026–2035 (12.00%)
Base Year 2025 (USD 24.10 Billion)
Forecast Endpoint 2035 (USD 74.77 Billion)
Fastest Growing Segment 5G NR (by technology); Small Cells (by component); Asia-Pacific (by region)
Companies Profiled CommScope, Corning, JMA Wireless, SOLiD, Ericsson, Nokia, Comba Telecom, Dali Wireless, Cel-Fi, Cobham
Valuation Currency USD Billion

FAQs

How does building construction material affect In-building Wireless Market system selection?
Dense materials like low-emissivity glass and reinforced concrete attenuate RF signals by 20–35 dB, often requiring active DAS or small cells rather than passive repeaters. System designers conduct site-specific RF surveys to match equipment to the building envelope .
What ROI timeline should property owners expect from an In-building Wireless Market investment?
Most commercial deployments achieve payback within 3–5 years through tenant retention premiums, carrier lease revenue, and reduced churn. Neutral-host configurations shorten payback by splitting costs across multiple operators .
How does the In-building Wireless Market address spectrum-licensing complexity for private networks?
Shared-spectrum frameworks like CBRS in the U.S. and local licensing in Germany allow enterprises to deploy indoor 5G without traditional carrier agreements. These regulatory models have simplified procurement significantly since 2023 [12].
What role does fiber-optic cabling play in modern in-building deployments?
Fiber serves as the backbone transport layer connecting headend equipment to remote radio units across floors. Single-mode fiber future-proofs installations for bandwidth growth beyond current 5G capacity requirements [Ref: Corning 2024].
How do building owners manage ongoing maintenance and software updates for In-building Wireless Market infrastructure?
Managed-service contracts that bundle monitoring, patching, and hardware refresh are now the norm for 60% of new installations. These OPEX models shift lifecycle risk from the building owner to the service provider .
What cybersecurity considerations apply to in-building wireless networks?
Indoor networks carry enterprise and tenant data, making them targets for rogue access points and man-in-the-middle attacks. Zero-trust segmentation and encrypted backhaul are becoming standard design requirements in the In-building Wireless Market [15].
Can existing 4G DAS infrastructure be upgraded to support 5G without full replacement?
Many digital DAS platforms support software-activated 5G overlays by adding new remote radio heads to existing fiber runs. Full replacement is typically needed only for legacy analog systems installed before 2018 [18].    
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory filings, standards development organizations, peer-reviewed telecommunications journals, and authoritative ICT industry databases. Key sources included the US Federal Communications Commission (FCC), UK Office of Communications (Ofcom), European Telecommunications Standards Institute (ETSI), 3rd Generation Partnership Project (3GPP), Telecommunications Industry Association (TIA), Institute of Electrical and Electronics Engineers (IEEE), Building Industry Consulting Service International (BICSI), Wireless Infrastructure Association (WIA), OnGo Alliance (CBRS), Small Cell Forum, HetNet Forum, Global mobile Suppliers Association (GSA), Cisco Visual Networking Index, Ericsson Mobility Report, CTIA Wireless Industry Association, OECD Communications Statistics, World Bank ICT indicators, International Telecommunication Union (ITU) databases, National Telecommunications and Information Administration (NTIA), and national telecom regulatory authority reports from key 5G deployment markets. These sources were used to collect spectrum allocation data, infrastructure deployment permits, DAS (Distributed Antenna Systems) regulation mandates, small cell siting policies, enterprise mobility statistics, and regulatory frameworks governing indoor wireless coverage across commercial, industrial, and public safety verticals.


Primary Research

As part of the primary research process, interviews were conducted with stakeholders from both the supply-side and the demand-side in order to acquire qualitative and quantitative perspectives. The supply-side sources consisted of vice presidents of wireless infrastructure, heads of DAS product lines, general managers of small cell divisions, CBRS solution architects, and business development directors from distributed antenna system vendors, small cell manufacturers, neutral host operators, and structured cabling original equipment manufacturers. The demand-side sources included chief technology officers and vice presidents of network engineering coming from mobile network operators (MNOs), wireless infrastructure procurement leads coming from commercial real estate investment trusts (REITs), chief information officers coming from healthcare and hospitality businesses, facilities management directors coming from smart buildings, and public safety communication managers coming from government agencies. Through primary research, we were able to evaluate the timetables for technological adoption, prove the sustainability of the neutral host business model, and obtain insights on private 5G network deployments, cabling infrastructure requirements, and venue partnership frameworks.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (35%), Others (33%)

• By Region: North America (32%), Europe (28%), Asia-Pacific (30%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through infrastructure deployment mapping and equipment revenue analysis. The methodology included:

• Identification of 35+ key infrastructure vendors and system integrators across North America, Europe, Asia-Pacific, and Middle East & Africa

• Product mapping across distributed antenna systems (active/passive DAS), small cells/femtocells, repeaters and signal boosters, 5G NR indoor radios, structured cabling assemblies, and headend equipment

• Analysis of reported and modeled annual revenues specific to in-building wireless portfolios, including both hardware sales and managed services contracts

• Coverage of manufacturers and neutral host operators representing 65-70% of global market share in 2024

• Extrapolation using bottom-up (square footage covered × deployment density × ASP by venue type) and top-down (carrier capex allocation and enterprise IT spend validation) approaches to derive segment-specific valuations across commercial offices, healthcare facilities, hospitality venues, transportation hubs, industrial manufacturing, and educational campuses

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















