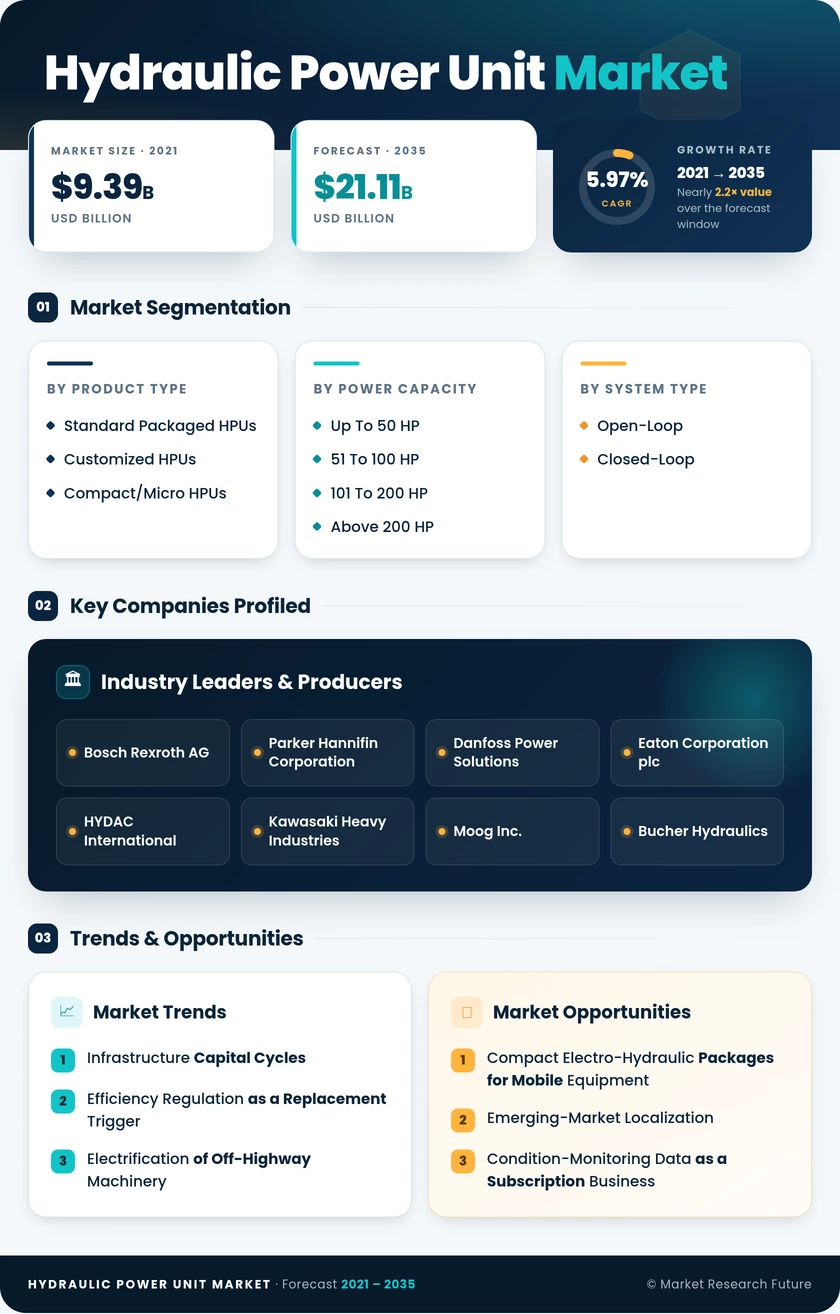
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Standard Packaged HPUs; Customized HPUs; Compact/Micro HPUs | Standard Packaged HPUs | Customized HPUs |
| By Power Capacity | Up To 50 HP; 51 To 100 HP; 101 To 200 HP; Above 200 HP | Above 200 HP | Up To 50 HP |
| By System Type | Open-Loop; Closed-Loop | Open-Loop | Closed-Loop |
| By Mobility | Stationary; Mobile | Stationary | Mobile |
| By End User | Manufacturing; Construction; Agriculture; Mining; Energy and Utilities; Others | Manufacturing | Construction |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Standard Packaged HPUs | Catalog configurators shorten quote-to-ship cycles for predictable duty applications. |
| Customized HPUs | Manifold consolidation and application-matched footprints protect supplier pricing power. |
| Compact/Micro HPUs | Machine-integrated packaging expands as mobile equipment electrifies. |
Product mix is bifurcating. Volume flows toward configurable catalog units where digital selection tools now compress lead times to days, while engineering value concentrates in customized and compact assemblies that resist commoditization.
By Power Capacity
| Sub-Segment | Key Trend |
| Up To 50 HP | Fastest expansion, driven by battery-electric mobile platforms |
| 51 To 100 HP | Steady industrial replacement demand across material handling |
| 101 To 200 HP | Efficiency retrofits dominate; variable-speed conversion accelerating. |
| Above 200 HP | Largest revenue contribution from mining, steel and primary metals |
Capacity demand splits by geography as much as by application. Mature economies concentrate spending in the mid and upper bands through retrofit, while emerging manufacturing hubs add small and mid-capacity units alongside new assembly capacity.
By System Type
| Sub-Segment | Key Trend |
| Open-Loop | Remains the cost and serviceability default across general industry |
| Closed-Loop | Energy recovery and precision control drive above-market growth. |
Closed-loop adoption tracks electricity pricing closely. Where industrial tariffs are high, recovery of deceleration energy shortens payback enough to justify the added component count and commissioning complexity.
By Mobility
| Sub-Segment | Key Trend |
| Stationary | Regulatory replacement cycles sustain the installed-base majority |
| Mobile | Highest growth and engineering content per unit shipped. |
Mobility is the dimension most reshaped by electrification. Fixed-plant demand grows steadily on compliance-driven replacement, whereas mobile demand grows on design-in wins that lock suppliers into decade-long platform relationships.
By End User
| Sub-Segment | Key Trend |
| Manufacturing | Servo conversion of press and forming lines dominates spending |
| Construction | Infrastructure programs and fleet renewal drive fastest sector growth. |
| Agriculture | Harvester and sprayer mechanization deepens in emerging economies. |
| Mining | Commodity reinvestment cycles govern order timing. |
| Energy and Utilities | Turbine, gate and tracker actuation expands with renewable capacity. |
| Others | Marine, aerospace, ground support and specialty applications |
End-use concentration is easing as construction and energy applications grow faster than manufacturing. Suppliers building diversified vertical coverage insulate themselves against the sharp cyclicality that single-sector specialists face.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA