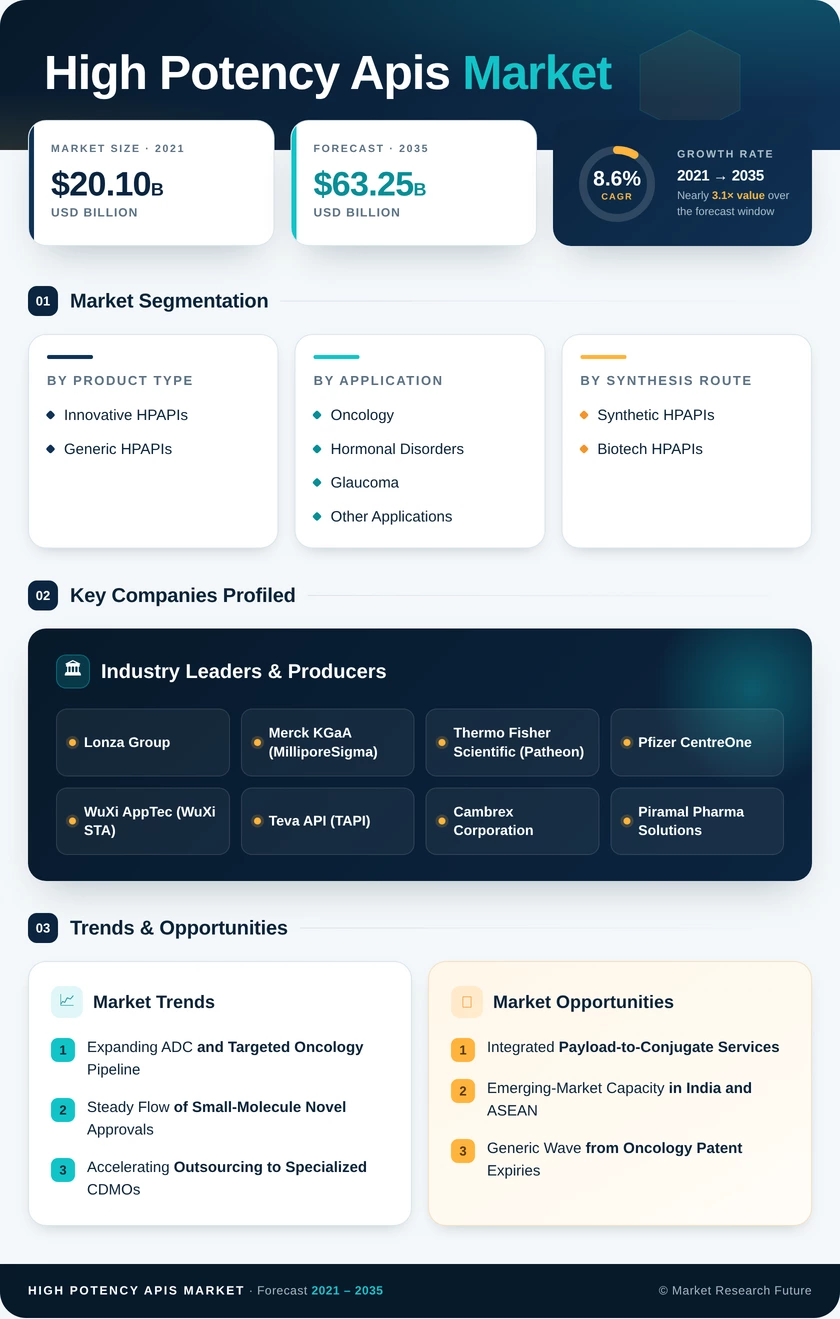
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Type | Innovative HPAPIs, Generic HPAPIs | Innovative HPAPIs – 58.2% share (2025) | Generic HPAPIs – 10.5% CAGR (2026–2035) |
| By Application | Oncology, Hormonal Disorders, Glaucoma, Other Applications | Oncology – 68.2% share (2025) | Glaucoma – 11.9% CAGR (2026–2035) |
| By Synthesis Route | Synthetic HPAPIs, Biotech HPAPIs | Synthetic HPAPIs – 65.7% share (2025) | Biotech HPAPIs – 10.7% CAGR (2026–2035) |
| By Manufacturer Type | Captive Manufacturers, Merchant Manufacturers | Captive Manufacturers – 51.5% share (2025) | Merchant Manufacturers – 11.5% CAGR (2026–2035) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America – 41.5% share (2025) | Asia-Pacific – 10.4% CAGR (2026–2035) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
|---|---|
| Innovative HPAPIs | Multi-year exclusivity contracts for first-in-class oncology molecules |
| Generic HPAPIs | Process replication ahead of oncology patent expiries |
Innovative HPAPIs lead with a 58.2% share because patent protection allows sponsors to absorb the cost of dedicated containment and pay premium supplier rates. Generic HPAPIs grow fastest at a 10.5% CAGR as exclusivity ends on major oncology drugs from 2026. Winners in the generic segment will be producers that can match originator impurity profiles and validate containment quickly enough to file first.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Oncology | ADC payloads and targeted small molecules expand volumes |
| Hormonal Disorders | Stable demand for potent steroids and hormonal agents |
| Glaucoma | Sustained-release implants using ultra-low-dose potent compounds |
| Other Applications | Immunology and specialty indications emerge |
Oncology dominates at a 68.2% share because chemotherapy agents and ADC payloads demand the strictest exposure controls. Glaucoma grows fastest at an 11.9% CAGR, driven by implants that release potent drugs over months at microgram doses. Hormonal Disorders remain a steady second pool built on long-established steroidal therapies.
By Synthesis Route
| Sub-Segment | Key Trend |
|---|---|
| Synthetic HPAPIs | Shift from batch reactors to continuous-flow chemistry |
| Biotech HPAPIs | Scale-up of peptide, oligonucleotide and conjugate capacity |
Synthetic HPAPIs hold a 65.7% share thanks to installed chemical capacity and well-understood process routes. Biotech HPAPIs grow faster at a 10.7% CAGR as peptides, oligonucleotides and biologic carriers progress through late-stage pipelines. Suppliers that can couple synthetic payloads to biologic carriers capture value from both routes.
By Manufacturer Type
| Sub-Segment | Key Trend |
|---|---|
| Captive Manufacturers | Continued in-house investment to protect IP on strategic molecules |
| Merchant Manufacturers | Acquisitions and capacity-reservation contracts expand footprint |
Captive Manufacturers retain a 51.5% share as large pharmaceutical companies keep strategic molecules and process know-how in-house. Merchant Manufacturers grow fastest at an 11.5% CAGR because biotech sponsors lack containment assets and larger companies favor flexible outsourcing. Recent acquisitions of contract capacity show investors betting on the merchant model.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA