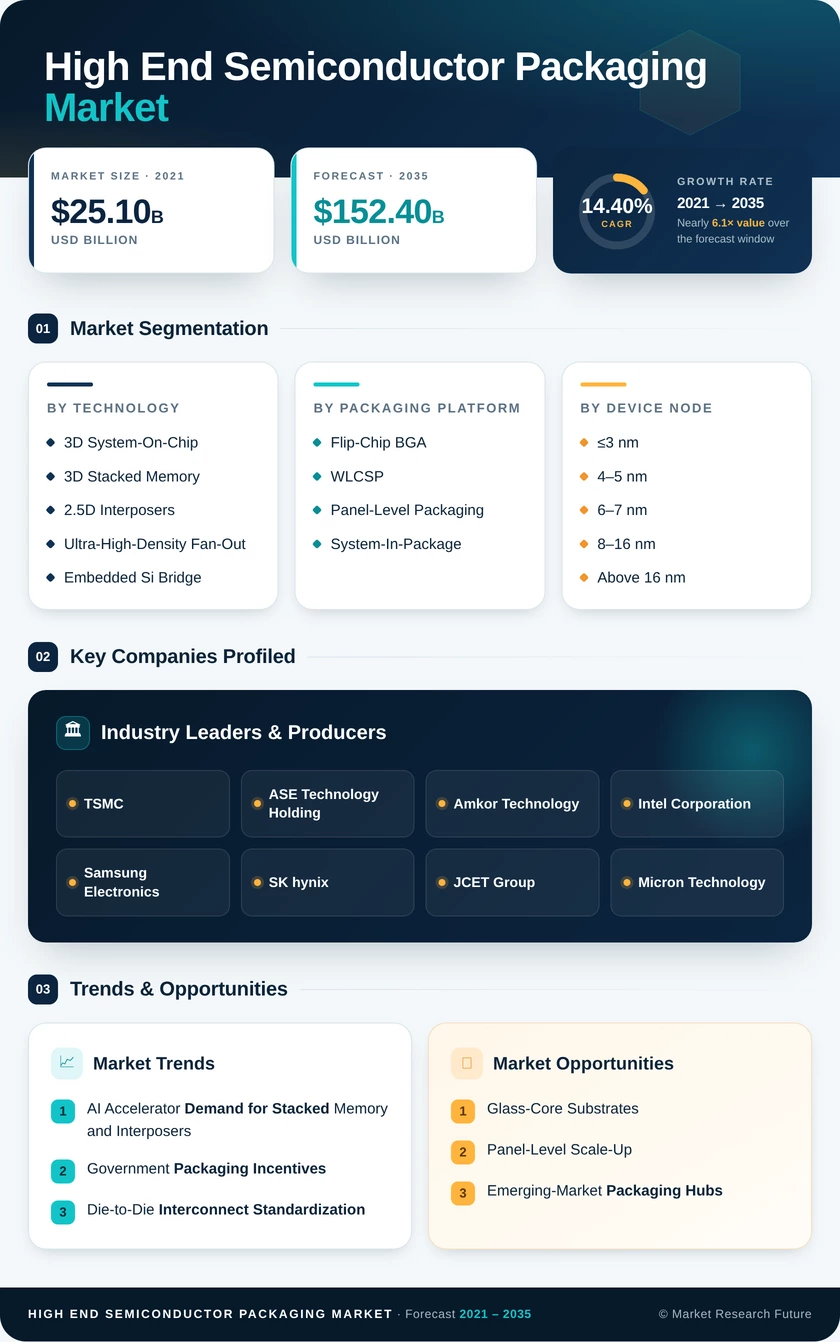
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Technology | 3D System-On-Chip, 3D Stacked Memory, 2.5D Interposers, Ultra-High-Density Fan-Out, Embedded Si Bridge | 3D Stacked Memory (34.8% share) | Embedded Si Bridge (15.21% CAGR) |
| By Packaging Platform | Flip-Chip BGA, WLCSP, Panel-Level Packaging, System-In-Package | Flip-Chip BGA (36.60% share) | Panel-Level Packaging (15.35% CAGR) |
| By Device Node | ≤3 nm, 4–5 nm, 6–7 nm, 8–16 nm, Above 16 nm | 6–7 nm (39.21% share) | ≤3 nm (15.17% CAGR) |
| By End User | Consumer Electronics, Data Center and High-Performance Computing, Automotive and ADAS, Telecom and Infrastructure, Aerospace and Defense, Industrial and Medical | Consumer Electronics (28.32% share) | Automotive and ADAS (15.11% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (64.5% share) | Middle East & Africa (17.2% CAGR) |
Market Segmentation Overview
By Technology
| Sub-Segment | Key Trend |
|---|---|
| 3D System-On-Chip | Hybrid bonding enables logic-on-logic stacking |
| 3D Stacked Memory | HBM stack heights rise with each generation |
| 2.5D Interposers | Interposers grow past multiple reticle limits |
| Ultra-High-Density Fan-Out | Finer redistribution layers for mobile processors |
| Embedded Si Bridge | Localized bridges replace full silicon interposers |
3D Stacked Memory leads this dimension because each AI accelerator carries several HBM stacks, and HBM4's wider interface raises stacking content per device. Embedded Si Bridge grows fastest since it delivers die-to-die bandwidth only at die edges, lowering silicon cost against 2.5D Interposers. 3D System-On-Chip remains tied to hybrid bonding yields before reaching broad volume.
By Packaging Platform
| Sub-Segment | Key Trend |
|---|---|
| Flip-Chip BGA | Larger body sizes for accelerators and switches |
| WLCSP | Thinner profiles for mobile and wearables |
| Panel-Level Packaging | Warpage control and glass panels under development |
| System-In-Package | Integration of compute, memory, and RF in one module |
Flip-Chip BGA leads because high-pin-count compute and networking devices depend on their low electrical parasitics and mature reliability record. Panel-Level Packaging grows fastest as rectangular panels cut cost per unit area, though automotive-grade reliability has not yet been demonstrated at scale. System-In-Package gains share as module makers combine more functions within one footprint.
By Device Node
| Sub-Segment | Key Trend |
|---|---|
| ≤3 nm | Power density drives thermally optimized interposers |
| 4–5 nm | Mainstay node for current accelerators |
| 6–7 nm | Cost-performance balance for networking and automotive |
| 8–16 nm | Used for I/O and controller dies |
| Above 16 nm | Analog, RF, and power companion dies |
6–7 nm holds the largest share because networking, automotive, and mainstream compute products balance cost and performance there. ≤3 nm grows fastest as flagship AI and smartphone processors migrate to the newest nodes, where high power density and costly known-good-die testing make package design central to performance. Older nodes persist as companion dies in mixed-node packages.
By End User
| Sub-Segment | Key Trend |
|---|---|
| Consumer Electronics | Longer refresh cycles in premium devices |
| Data Center and High-Performance Computing | Highest value per package from AI accelerators |
| Automotive and ADAS | Central compute adoption in Level 3 vehicles |
| Telecom and Infrastructure | Open RAN favors modular multi-die designs |
| Aerospace and Defense | Hermetic, radiation-hardened packages |
| Industrial and Medical | Edge AI in imaging and robotics |
Consumer Electronics remains the largest end user, but slower smartphone and PC replacement cycles are moderating its growth. Automotive and ADAS expand fastest because Level 3 vehicles embed several high-performance processors that need thermally robust, AEC-Q100-qualified packages. Data Center and High-Performance Computing carry the highest value per package, while Aerospace and Defense stay a premium niche.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA