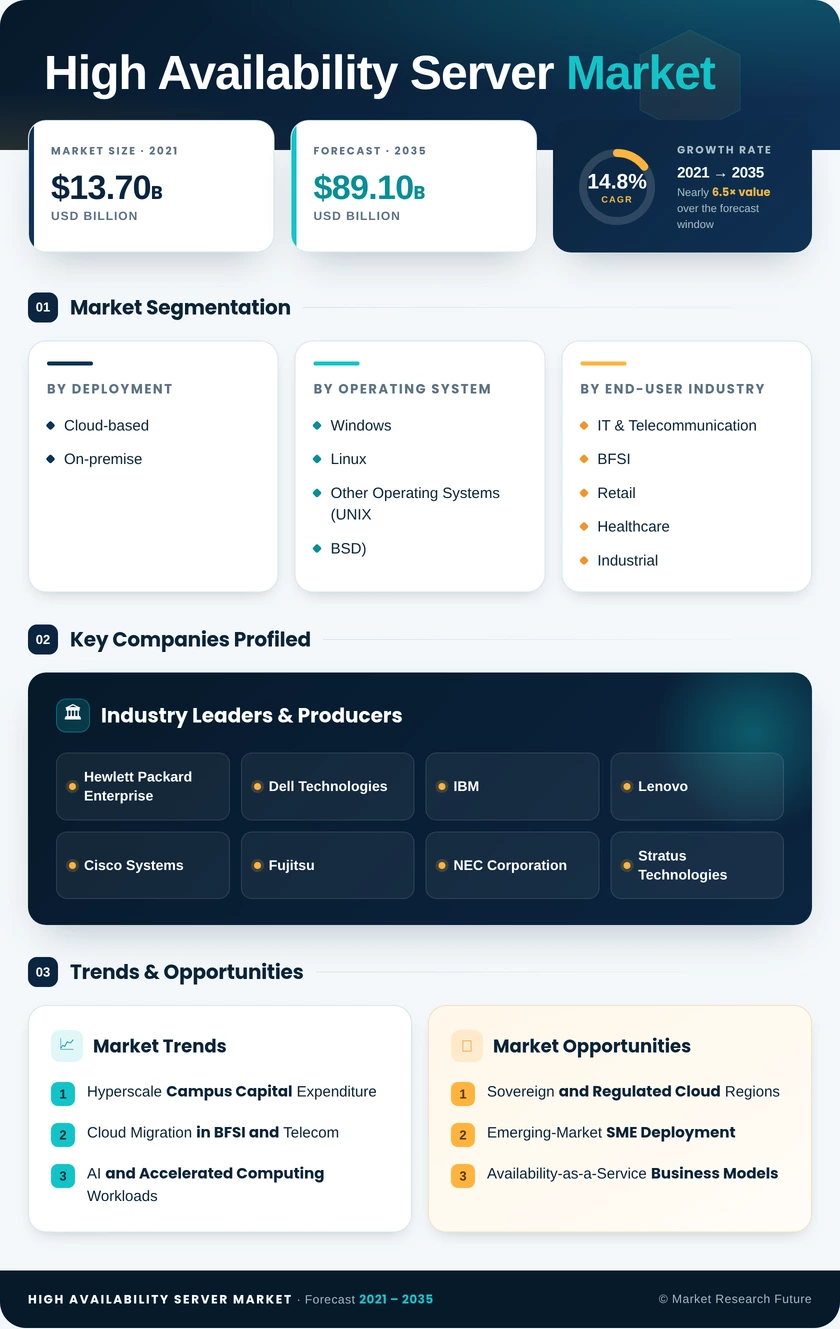
High Availability Server Market (2026 - 2035)

ID: MRFR/ICT/24885-CR 111 Pages Ankit Gupta Last Updated: September 17, 2026
High Availability Server Market Size, Share and Research Report By Deployment (Cloud-based and On-premise), By Operating System (Windows, Linux, and Other Operating Systems including UNIX and BSD), By End-user Industry (IT & Telecommunication, BFSI, Retail, Healthcare, Industrial, and Other End-user Industries), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035.
High Availability Server Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.8%
2025 Market SizeUSD 22.4 Billion
2035 Market SizeUSD 89.1 Billion
Key Players
Hewlett Packard Enterprise
Dell Technologies
IBM
Lenovo
Cisco Systems
Fujitsu
Opportunities
  • Sovereign and Regulated Cloud Regions
  • Emerging-Market SME Deployment
  • Availability-as-a-Service Business Models
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Deployment | |
    2. 2.2 By Operating System | |
    3. 2.3 By End-user Industry | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Hyperscale Campus Capital Expenditure | |
    2. 4.2 Cloud Migration in BFSI and Telecom | |
    3. 4.3 AI and Accelerated Computing Workloads | |
    4. 4.4 Regulatory Resilience Mandates | |
    5. 4.5 Edge Computing and 5G Core Densification | |
    6. 4.6 Energy-Efficient Processor Design | |
    7. 4.7 SME Price Accessibility | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Capital and Licensing Cost of Redundant Architectures | |
    2. 5.2 Software-Level Resilience Displacing Hardware Redundancy | |
    3. 5.3 Component Supply Constraints and Lead Times | |
    4. 5.4 Power and Cooling Interconnection Delays | |
    5. 5.5 Shortage of Resilient-Systems Engineering Skills | |
  6. 6 Opportunities | |
    1. 6.1 Sovereign and Regulated Cloud Regions | |
    2. 6.2 Emerging-Market SME Deployment | |
    3. 6.3 Availability-as-a-Service Business Models | |
    4. 6.4 Healthcare Digitisation and Clinical Continuity | |
    5. 6.5 Telecom Edge Monetisation | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Operations and Predictive Failover | |
    2. 8.2 Platform Economics and Consumption Pricing | |
    3. 8.3 Energy Constraint as the Binding Variable | |
    4. 8.4 Consolidation Around Fewer Certified Platforms | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Deployment | | |
      1. 9.1.1 Cloud-based | | |
      2. 9.1.2 On-premise | |
    2. 9.2 By Operating System | | |
      1. 9.2.1 Windows | | |
      2. 9.2.2 Linux | | |
      3. 9.2.3 Other Operating Systems (UNIX, BSD) | |
    3. 9.3 By End-user Industry | | |
      1. 9.3.1 IT & Telecommunication | | |
      2. 9.3.2 BFSI | | |
      3. 9.3.3 Retail | | |
      4. 9.3.4 Healthcare | | |
      5. 9.3.5 Industrial | | |
      6. 9.3.6 Other End-user Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Hewlett Packard Enterprise | | |
      2. 10.3.2 Dell Technologies | | |
      3. 10.3.3 IBM | | |
      4. 10.3.4 Lenovo | | |
      5. 10.3.5 Cisco Systems | | |
      6. 10.3.6 Fujitsu | | |
      7. 10.3.7 NEC Corporation | | |
      8. 10.3.8 Stratus Technologies | | |
      9. 10.3.9 Oracle | | |
      10. 10.3.10 Super Micro Computer | | |
      11. 10.3.11 Inspur | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Triangulation | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global High Availability Server Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global High Availability Server Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Deployment, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Market Size, by Operating System, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  23. TABLE 9 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  26. TABLE 12 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Market Size, by Deployment, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Market Size, by Operating System, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  31. TABLE 17 Europe Market Size, by Deployment, 2021–2035 (USD Billion) | |
  32. TABLE 18 Europe Market Size, by Operating System, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  34. TABLE 20 Asia-Pacific Market Size, by Deployment, 2021–2035 (USD Billion) | |
  35. TABLE 21 Asia-Pacific Market Size, by Operating System, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  37. TABLE 23 South America Market Size, by Deployment, 2021–2035 (USD Billion) | |
  38. TABLE 24 South America Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  39. TABLE 25 Middle East & Africa Market Size, by Deployment, 2021–2035 (USD Billion) | |
  40. TABLE 26 Middle East & Africa Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  41. TABLE 27 Competitive Benchmarking Matrix, 2026 | |
  42. TABLE 28 Company Profiles – Key Players | |
  43. TABLE 29 Recent Developments & Strategic Announcements, 2023–2025 | |
  44. TABLE 30 Report Scope & Methodology Summary | |
  45. TABLE 31 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  46. FIGURE 1 Market Dynamics Snapshot – Drivers, Restraints and Opportunities | |
  47. FIGURE 2 Industry Value Chain Analysis | |
  48. FIGURE 3 Porter's Five Forces Analysis | |
  49. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  50. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 (%) | |
  51. FIGURE 6 Market Share by Deployment, 2025 vs 2035 (%) | |
  52. FIGURE 7 Market Share by Operating System, 2025 vs 2035 (%) | |
  53. FIGURE 8 Market Share by End-user Industry, 2025 (%) | |
  54. FIGURE 9 Regional Market Share Distribution, 2025 (%) | |
  55. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) | |
  56. FIGURE 11 Country-Level Contribution within Asia-Pacific, 2025 (%) | |
  57. FIGURE 12 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  58. FIGURE 13 Competitive Positioning Quadrant – Capability vs Certification Breadth | |
  59. FIGURE 14 Driver Impact Contribution Waterfall, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By DeploymentCloud-based; On-premiseOn-premise (53.6% share, 2025)Cloud-based (17.4% CAGR, 2026–2035)
By Operating SystemWindows; Linux; Other Operating Systems (UNIX, BSD)Linux (52.6% share, 2025)Windows (15.6% CAGR, 2026–2035)
By End-user IndustryIT & Telecommunication; BFSI; Retail; Healthcare; Industrial; Other End-user IndustriesIT & Telecommunication (29.7% share, 2025)Healthcare (18.1% CAGR, 2026–2035)


Market Segmentation Overview

By Deployment

Sub-SegmentKey Trend
Cloud-basedSovereign and in-country regions extend compliant redundant capacity to regulated buyers.
On-premiseLatency-bound and residency-bound workloads retain dedicated clustered hardware.


On-premise remains the larger of the two sub-segments at 53.6% share because auditors accept evidence of physically controlled failover more readily than shared-tenancy attestations, and because industrial control and core banking systems carry recovery-time objectives that public regions cannot always contract to. Cloud-based deployment nonetheless grows fastest at 17.4% annually, driven almost entirely by sovereign region build-outs in the Gulf, France and Southeast Asia that place compliant capacity inside national borders. The two sub-segments are converging in practice: most large buyers now run clustered pairs on both sides of the boundary.

By Operating System

Sub-SegmentKey Trend
WindowsIntegrated failover clustering and hybrid management lower the operational skill threshold.
LinuxPacemaker, Corosync and DRBD stacks anchor large-scale cluster deployment.
Other Operating System (UNIX, BSD)Legacy transaction and switching platforms sustain absolute value while share erodes.


Linux leads at 52.6% share because the open cluster stack is mature, staffable and aligned with the container platforms that new applications target, which matters most to the hyperscale and telecom buyers who account for the largest configuration volumes. Windows grows fastest at 15.6% as mid-market organisations without dedicated Linux operations teams adopt built-in failover clustering paired with hybrid management consoles. Other Operating System (UNIX, BSD) holds roughly USD 2.98 billion of 2025 value in transaction and switching platforms whose rewrite cost still exceeds their maintenance cost.

By End-user Industry

Sub-SegmentKey Trend
IT & Telecommunication5G standalone core functions push redundancy out to aggregation sites
BFSIResilience regulation converts tested failover into a licensing condition.
RetailOmnichannel order management raises uptime expectations beyond store hours.
HealthcareRecords platform replacement and diagnostic imaging workloads drive clustered procurement.
IndustrialProcess control and manufacturing execution systems require continuous availability.
Other End-user IndustriesPublic sector, education and media workflows modernise on longer cycles.


IT & Telecommunications holds the largest position at 29.7% share, reflecting the sheer number of aggregation and edge sites that 5G standalone cores require and the redundancy each one carries. Healthcare expands fastest at 18.1% because hospital systems are replacing decade-old records platforms during the same window that imaging and diagnostic AI workloads enter clinical pathways, and unavailability there carries patient consequences rather than revenue inconvenience. BFSI contributes the second-largest absolute value at USD 5.44 billion, where supervisors now audit failover testing directly.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.