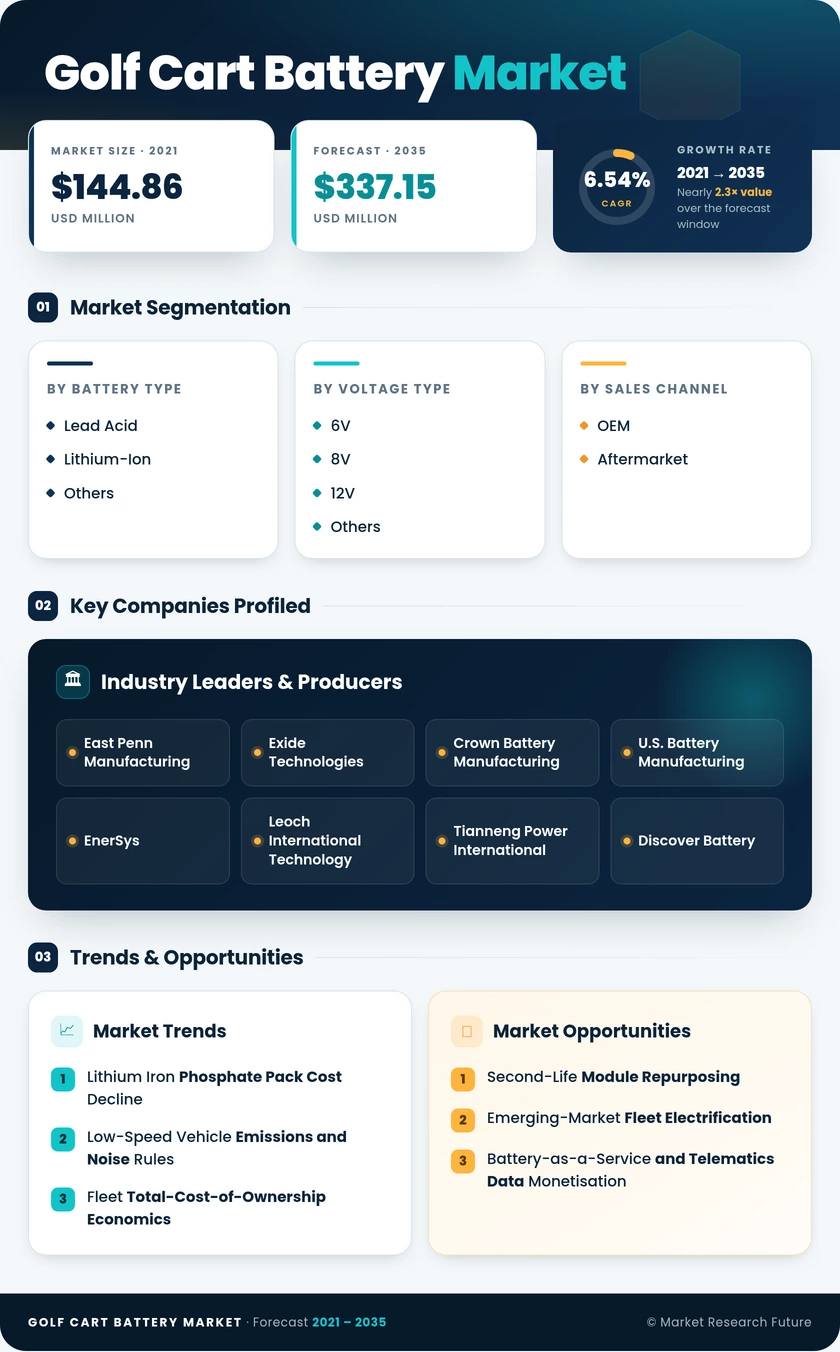
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Battery Type | Lead Acid, Lithium-Ion, Others | Lithium-Ion (50.48% share) | Lithium-Ion (6.57% CAGR) |
| By Voltage Type | 6V, 8V, 12V, Others | 6V (46.49% share) | 12V (6.66% CAGR) |
| By Sales Channel | OEM, Aftermarket | Aftermarket (67.93% share) | Aftermarket (6.61% CAGR) |
| By Application | Golf Course, Commercial | Golf Course (61.75% share) | Commercial (6.58% CAGR) |
Market Segmentation Overview
By Battery Type
| Sub-Segment | Key Trend |
| Lead Acid | Enhanced-flooded and AGM variants defend price-sensitive accounts |
| Lithium-Ion | LiFePO₄ packs with integrated BMS become the new-fleet default. |
| Others | Sodium-ion prototypes and nickel-metal hydride niches |
Lithium-Ion leads this dimension at 50.48% share and simultaneously grows fastest at a 6.57% CAGR, because 6,000-cycle durability and the elimination of watering and equalisation labour outweigh a purchase price roughly 2.4 times that of a comparable Lead Acid bank. Lead Acid holds ground where annual capital budgets govern, and maintenance labour is inexpensive, particularly in South America and parts of Asia-Pacific. Others stay marginal through the decade but are the entry point for sodium-ion chemistries after 2028.
By Voltage Type
| Sub-Segment | Key Trend |
| 6V | Series-string architecture retains installed-base advantage |
| 8V | Balances runtime against tray footprint in mid-range carts |
| 12V | OEM designs converge on fewer, larger units |
| Others | 48V and 72V platforms for utility and people-mover duty |
6V dominates at 46.49% share, an artefact of series-string lead-acid design where replacing a single failed unit is cheaper than replacing a bank. That logic breaks with sealed lithium, so 12V grows fastest at a 6.66% CAGR as manufacturers cut connection points, reduce corrosion failure modes and free auxiliary capacity for GPS displays and cabin climate systems. The 8V sub-segment persists as a compromise fit for existing trays, while Others captures higher-voltage utility platforms.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM | Bundled pack, charger, telematics and unified warranty packages |
| Aftermarket | Multi-brand drop-in kits with local installation and financing |
Aftermarket both leads at 67.93% share and grows fastest at a 6.61% CAGR, sustained by distributors who stock competing brands, standardised tray geometry that permits cross-brand swaps, and fleet managers who prefer negotiating outside OEM service windows. OEM volumes still climb in absolute terms as factory-fit lithium moves from special order to catalogue line, appealing to institutional buyers who value a single warranty counterparty. Channel competition now centres on installation speed and take-back logistics rather than unit price.
By Application
| Sub-Segment | Key Trend |
| Golf Course | Steady replacement cadence across an entrenched fleet base |
| Commercial | Resorts, campuses, gated communities and industrial sites |
Golf Course applications hold 61.75% share on the strength of an installed cart population that turns over predictably every five to seven years regardless of economic conditions. Commercial expands faster at a 6.58% CAGR because its duty cycles are more demanding — longer shifts, heavier payloads, frequent stop-start operation — which shortens replacement intervals and strongly favours high-cycle lithium chemistry. Hospitality and campus operators additionally weight quiet, fume-free operation and reduced turf compaction in their specifications.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA