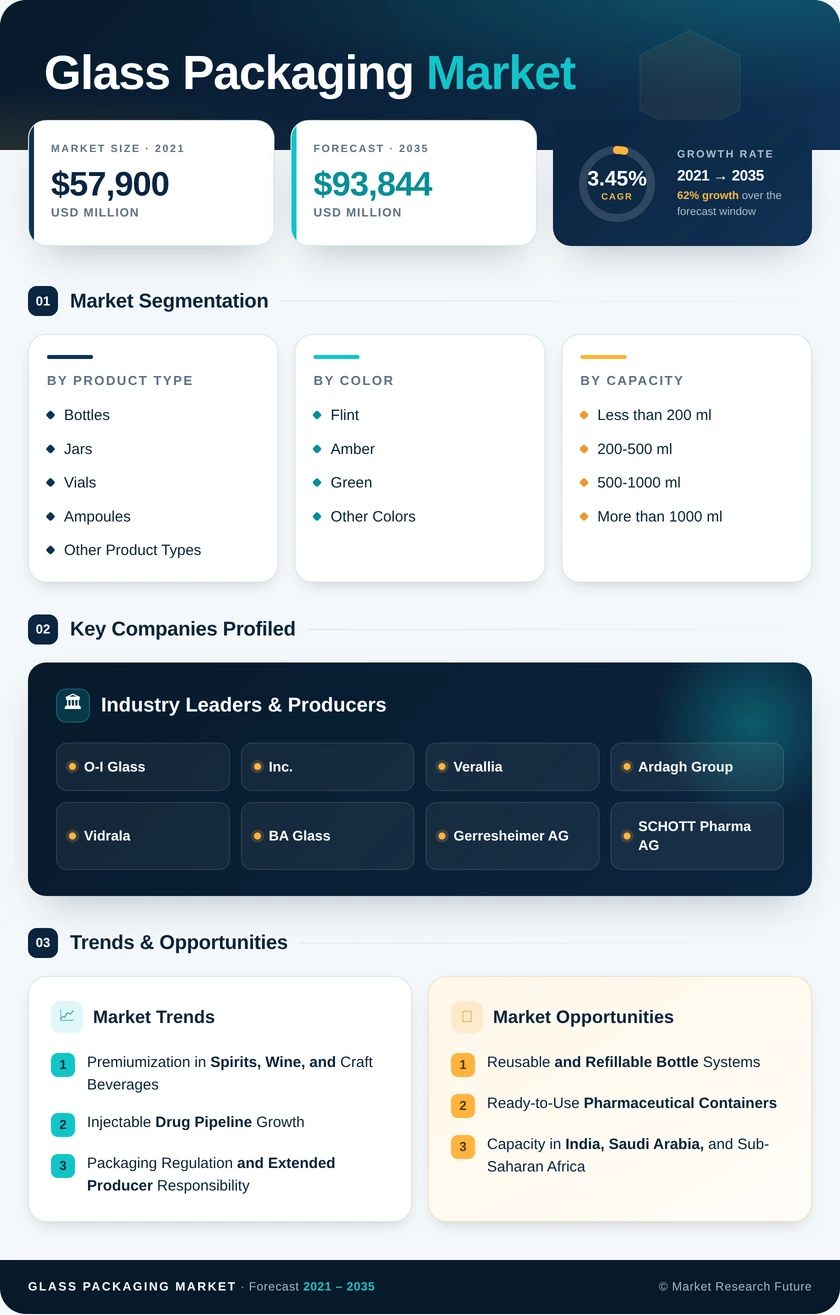
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Type | Bottles and Jars; Vials and Ampoules; Other Product Types | Bottles and Jars (68.7% share) | Vials and Ampoules (6.69% CAGR) |
| By Color | Flint; Amber; Green; Other Colors | Flint (48.0% share) | Green (5.60% CAGR) |
| By Capacity | Less than 200 ml; 200-500 ml; 500-1000 ml; More than 1000 ml | 500-1000 ml (38.4% share) | Less than 200 ml (5.9% CAGR) |
| By End-Use Industry | Food; Beverage; Pharmaceuticals; Cosmetics and Personal Care; Other End-Use Industries | Beverage (57.6% share) | Pharmaceuticals (7.57% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Europe (33.8% share) | Middle East & Africa (5.12% CAGR) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
|---|---|
| Bottles and Jars | Lightweighting and premium decoration across beverages and food |
| Vials and Ampoules | Shift to ready-to-use, delamination-resistant Type I formats |
| Other Product Types | Automated production of laboratory and specialty vessels |
Bottles and Jars lead because a single forming process serves beer, wine, spirits, and food categories at very high volumes. Vials and Ampoules grow fastest as biologics and GLP-1 injectables require inert Type I containers, often supplied pre-sterilized in nested trays. Other Product Types stay a stable niche anchored in laboratory and specialty demand.
By Color
| Sub-Segment | Key Trend |
|---|---|
| Flint | Demand for clarity in spirits, food, and cosmetics |
| Amber | UV protection for beer and light-sensitive drugs |
| Green | High mixed-cullet tolerance and wine heritage |
| Other Colors | Custom tints for gin and luxury fragrance |
Flint leads on shelf visibility, though its need for clean, color-sorted cullet limits recycled content. Green grows fastest because wineries and craft brewers favor it and it absorbs mixed cullet that cuts melting energy. Amber holds a protected position in beer and pharmaceuticals where light sensitivity rules out clear glass.
By Capacity
| Sub-Segment | Key Trend |
|---|---|
| Less than 200 ml | Growth in injectable vials, perfumes, and travel sizes |
| 200-500 ml | Craft beer and portion-controlled functional drinks |
| 500-1000 ml | Standard 750 ml wine and spirits format |
| More than 1000 ml | Food-service and institutional supply |
The 500-1000 ml class leads because the 750 ml wine and spirits bottle anchors global tonnage. Less than 200 ml grows fastest as high-value injectables and fragrances command premium pricing per unit. The 200-500 ml range sustains steady demand from craft beer and functional beverages.
By End-Use Industry
| Sub-Segment | Key Trend |
|---|---|
| Food | Visibility and inertness for sauces, preserves, and baby food |
| Beverage | Premiumization in wine, spirits, and craft beer |
| Pharmaceuticals | Commercial scale-up of biologics, vaccines, and GLP-1 drugs |
| Cosmetics and Personal Care | Luxury positioning and refillable designs |
| Other End-Use Industries | Chemical and laboratory reagent storage |
Beverage leads because glass is integral to brand identity in wine and spirits, where premium mix keeps value growing despite softer mainstream beer. Pharmaceuticals expand fastest as injectable therapies reach commercial scale and require qualified Type I suppliers. Food provides baseline volume, while Cosmetics and Personal Care adds value through heavyweight, decorated, and refillable formats.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA