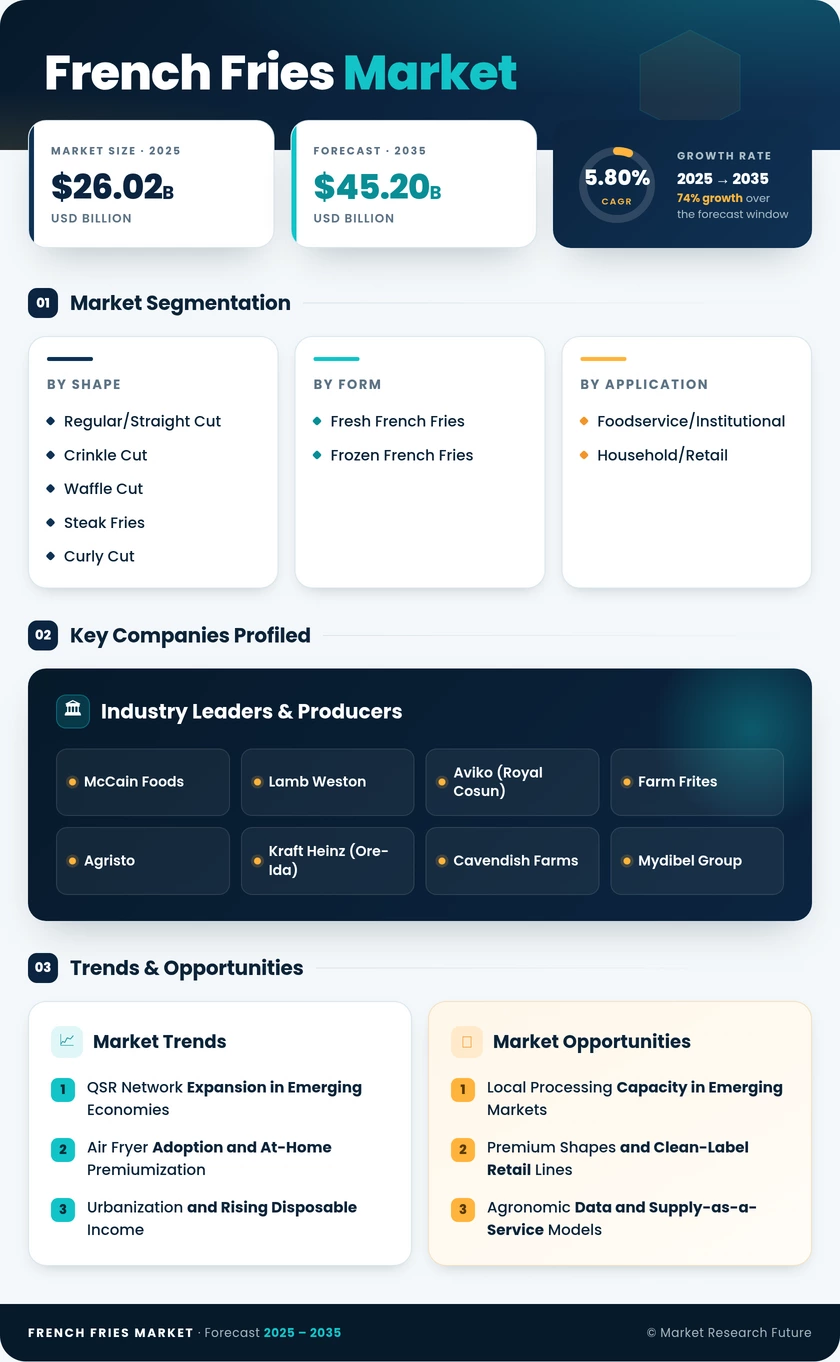
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Shape | Regular/Straight Cut, Crinkle Cut, Waffle Cut, Steak Fries, Curly Cut | Regular/Straight Cut (41.2% share) | Waffle Cut (6.90% CAGR) |
| By Form | Fresh French Fries, Frozen French Fries | Frozen French Fries (82.6% share) | Frozen French Fries (82.6% share) |
| By End User | Foodservice/Institutional, Household/Retail | Household/Retail (70.0% share) | Household/Retail (70.0% share) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East and Africa | Europe (36.6% share) | Asia-Pacific (6.40% CAGR) |
Market Segmentation Overview
By Shape
| Sub-Segment | Key Trend |
|---|---|
| Regular/Straight Cut | Default QSR specification; growth slowing as chains add signature cuts |
| Crinkle Cut | Stable demand in retail multipacks and school foodservice |
| Waffle Cut | Premium retail launches, including organic and seed-oil-free lines |
| Steak Fries | Thick-cut positioning in casual dining and pub menus |
| Curly Cut | Seasoned signature sides for menu differentiation |
Regular/Straight Cut leads with a 41.2% share because QSR fryers, portioning systems and hold times are engineered around it. Waffle Cut grows fastest at a 6.90% CAGR, as retail buyers reward its visual differentiation and sauce-holding surface with premium freezer placement. Curly Cut follows a similar premium logic in chain restaurants, while Crinkle Cut holds steady in value-oriented retail.
By Form
| Sub-Segment | Key Trend |
|---|---|
| Fresh French Fries | Shrinking to premium hand-cut concepts as wages rise |
| Frozen French Fries | Continued conversion of kitchens to par-fried, coated product |
Frozen French Fries lead and grow fastest, holding an 82.6% share because par-frying and freezing remove in-store peeling, cutting and blanching labor. Fresh French Fries grow more slowly at a 3.90% CAGR, sustained mainly by independent and premium restaurants that use hand-cut preparation as a selling point despite higher wage costs.
By End User
| Sub-Segment | Key Trend |
|---|---|
| Foodservice/Institutional | Multi-year QSR contracts and delivery-optimized coated fries |
| Household/Retail | Air-fryer-labelled SKUs, private label and online grocery growth |
Household/Retail leads and grows fastest with a 70.0% share, as air fryer ownership and expanded supermarket and hypermarket freezer ranges move consumption into the home. Foodservice/Institutional, valued at USD 7.81 Billion, depends on specification-driven QSR and caterer contracts, where hold-time performance and supply security outweigh shelf appeal.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA