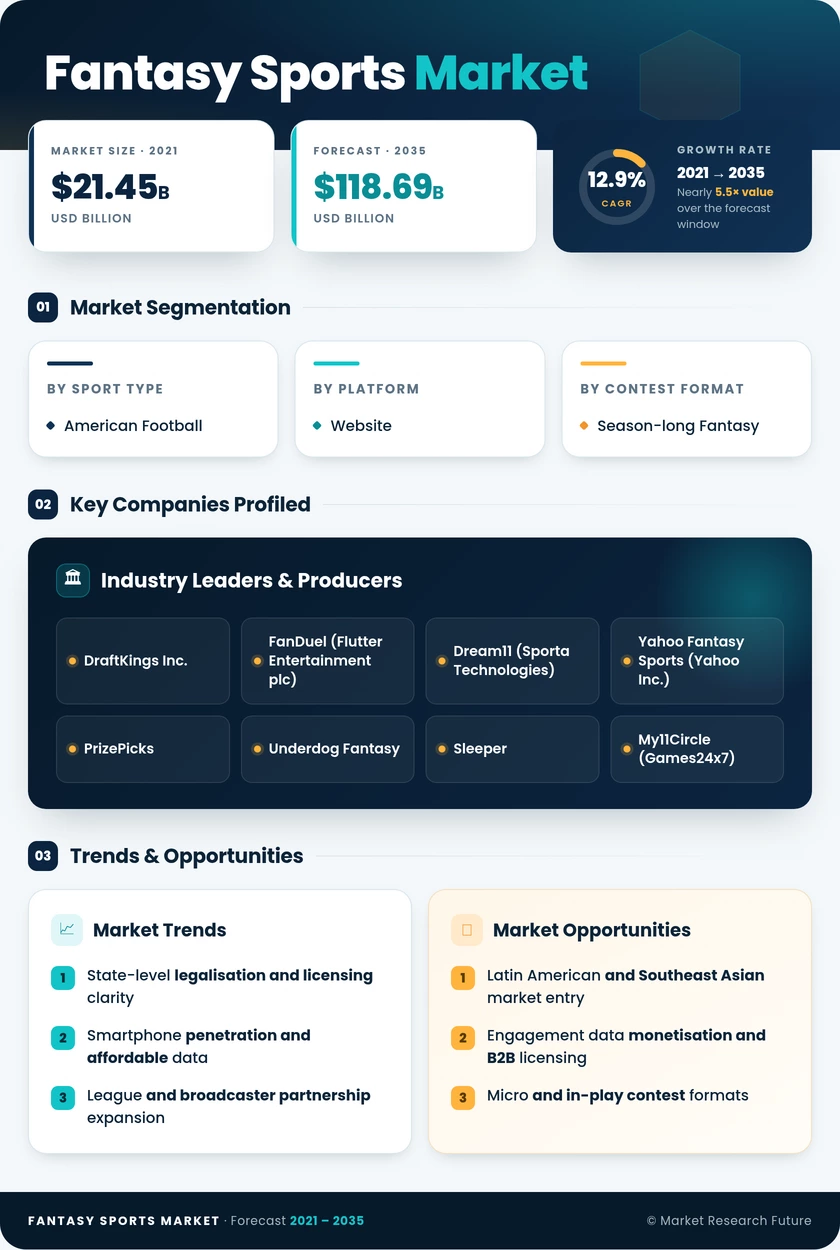
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Sport Type | American Football | American Football (70.42% revenue share, 2025) | American Football (70.42% revenue share, 2025) |
| By Platform | Website | Website (9.6% CAGR, 2026–2035) | Website (9.6% CAGR, 2026–2035) |
| By Contest Format | Season-long Fantasy | Season-long Fantasy (USD 9.81 Billion, 2025) | Season-long Fantasy (USD 9.81 Billion, 2025) |
| By Revenue Model | Entry-fee Based | Entry-fee Based (57.36% revenue share, 2025) | Entry-fee Based (57.36% revenue share, 2025) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America (41.5% revenue share) | Asia-Pacific (15.4% CAGR, 2026–2035) |
Market Segmentation Overview
By Sport Type
| Sub-Segment | Key Trend |
| American Football | Weekly fixture cadence and official league scoring partnerships sustain habitual participation |
American Football leads and grows fastest within this dimension because its scheduling structure — a compressed weekly slate with a fixed lock time — produces the most reliable recurring engagement loop of any code covered in scope. Official league data agreements give operators settlement authority that reduces scoring disputes, a material factor for regulators assessing skill predominance. The sub-segment's revenue concentration in the September-to-January window also explains why operators build cross-sport bundles around it rather than replacing it. Section 9 identifies the same dynamic, with share compressing only as absolute revenue continues to rise.
By Platform
| Sub-Segment | Key Trend |
| Website | Browser access retained for draft boards, trade evaluation, and multi-league portfolio management |
Website is the sole access channel in scope and therefore both the leading and fastest-expanding sub-segment here, advancing at 9.6% annually. Its persistence is driven by buyer behaviour rather than nostalgia: participants managing several leagues need the screen area that draft boards, projection tables, and trade analysers demand, and average entry values on browser sessions exceed those recorded elsewhere. Cloud-synced accounts let research happen on Website and execution happen anywhere, which is why operators continue funding browser feature parity despite handheld session dominance.
By Contest Format
| Sub-Segment | Key Trend |
| Season-long Fantasy | Social league obligation drives renewal rates above 80% year over year |
Season-long Fantasy leads this dimension at USD 9.81 Billion in 2025 and also grows fastest within scope, because the retention mechanism is social rather than promotional. A workplace or friend group league commits a dozen participants to a shared season, and switching operators requires collective agreement — a barrier no competitor discount easily overcomes. Commissioner tooling, trade arbitration, and messaging features are the buyer-relevant differentiators here, and operators treat Season-long Fantasy as the acquisition anchor from which other formats are cross-sold, exactly as Section 9 describes.
By Revenue Model
| Sub-Segment | Key Trend |
| Entry-fee Based | Transparent rake disclosure supports regulatory approval and participant trust |
Entry-fee Based monetisation holds 57.36% of 2025 receipts and remains the fastest-growing model in scope, sustained by regulatory preference as much as participant familiarity. Published rake percentages and segregated player-fund accounting simplify licensing submissions in jurisdictions that require documented skill predominance, so Entry-fee Based products clear compliance review faster than experimental alternatives. Taxation of deposits and rising promotional competition are compressing margin, which is pushing operators to layer additional revenue streams on top of — not in place of — the Entry-fee Based core.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA