E-House Market (2026 – 2035)

E-House Market Size, Share and Research Report By Solution (Fixed E-House, Mobile Substation), By Voltage Rating (Low Voltage, Medium Voltage, High Voltage), By Application (Utilities, Industrial, Oil and Gas, Mining, Data Centers, Others (Renewables, Hydrogen, Rail)), By Component (Switchgear, Transformer, Protection & Control Systems, Others (Busbar, HVAC, Fire Suppression)), By Deployment Mode (Permanent, Temporary / Relocatable) and By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Industry Forecast to 2035.
ID: MRFR/SEM/4127-CR 200 Pages Ankit Gupta Last Updated: October 27, 2026
E-House Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.3%
2025 Market SizeUSD 1.82 Billion
2035 Market SizeUSD 3.34 Billion
Key Players
ABB Ltd.
Siemens Energy
Schneider Electric
Eaton Corporation
Powell Industries
WEG S.A.
Opportunities
  • Modular Hydrogen Electrolysis Plants
  • Emerging-Market Grid Access Programs
  • Drone-Based Inspection and Digital Twin Integration

E-House Market Summary

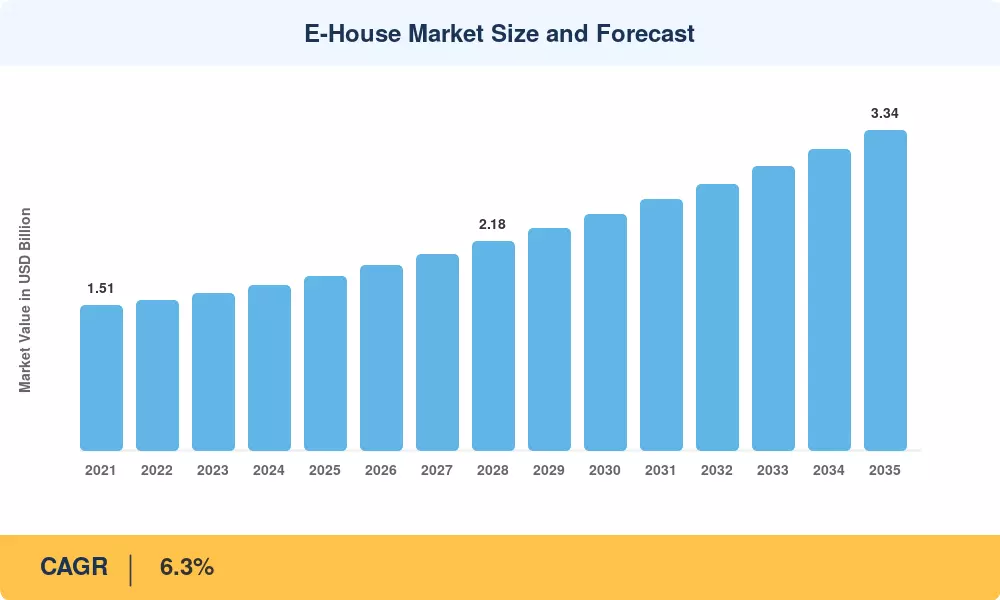
The global E-House Market was valued at USD 1.82 billion in 2025 and is projected to reach USD 1.93 billion in 2026 before climbing to USD 3.34 billion by 2035, registering a CAGR of 6.3% during the 2026–2035 forecast window. Accelerating grid modernization programs — particularly the US Department of Energy's USD 20 billion Grid Resilience and Innovation Partnerships (GRIP) initiative and the European Union's revised Trans-European Networks for Energy (TEN-E) regulation — are channeling capital toward factory-assembled electrical enclosures that compress project timelines from twelve months to as few as eight weeks [1][2]. Utilities, mining operators, and data-center developers increasingly prefer these pre-engineered modules because they reduce field labor, minimize safety incidents, and deliver pre-commissioned power distribution in a single truck-ready package.

The E-House Market is undergoing a bigger technology transformation. Traditional stick-built substations and field-fabricated switchgear rooms are being replaced by integrated modular units that bring together medium-voltage switchgear, low-voltage distribution panels, transformers and digital protection relays in one weather-rated enclosure. The pending phase-out of sulfur hexafluoride (SF₆) insulation gas under the EU F-Gas Regulation revision is accelerating adoption of vacuum and clean-air switchgear inside these modules, with an estimated USD 1.2 billion in retrofit spending expected across European utilities by 2030 [3].


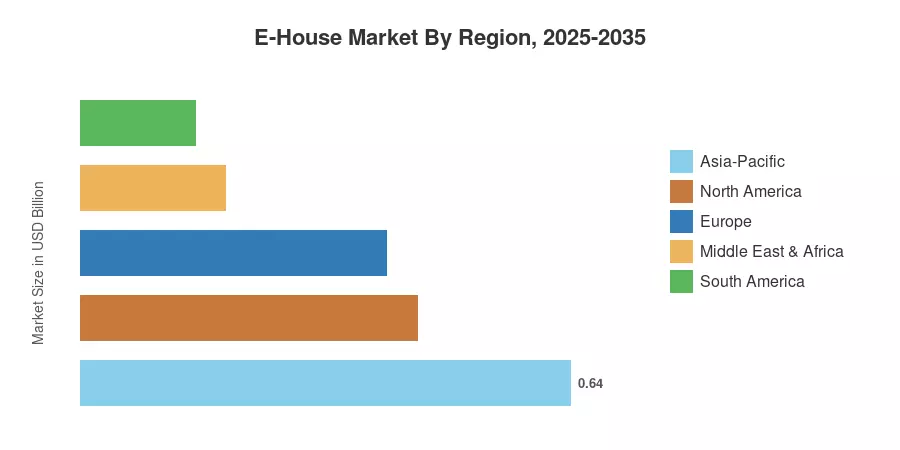
The Asia-Pacific region leads the E-House Market with around 35% of the worldwide revenue share. This is mostly due to the ultra-high-voltage corridor build-out in China and the Revamped Distribution Sector Scheme (RDSS) in India. The Middle East & Africa is the fastest expanding market with a predicted CAGR of 10.2% through 2035, driven by Saudi Arabia’s NEOM and Red Sea megaprojects. North America is the second largest at around 24%, aided by data-centre campus expansions and renewable-energy connectivity backlogs.


Key Report Takeaways

• By Solution

  • Fixed e-house units accounted for approximately 58% of 2025 revenue, reflecting strong utility and industrial preference for permanent installations.
  • Mobile substations are expanding at a CAGR of 6.6% through 2035, driven by emergency restoration and temporary power needs.

• By Application

  • Utilities commanded roughly 53% of the E-House Market in 2025, underpinned by grid expansion mandates.
  • Data-center deployments represent the fastest-growing application segment, with an 8.8% CAGR forecast to 2035.

• By Geography

  • Asia-Pacific contributed about 35% of the global E-House Market revenue in 2025.
  • The Middle East & Africa region is forecast to register the highest regional CAGR of 10.2% through 2035.


E-House Market Size and Forecast (2021–2035)

Market sizing draws on primary interviews with 45+ electrical OEMs, EPCs, and utility procurement officers, supplemented by customs trade data, company filings, and secondary databases from IEA, IRENA, and regional grid operators. Actuals (2021-2024) are verified with published order backlogs. Projections (2026-2035) utilize a growth model calibrated to a regression fit and linked to electrification capex forecasts [4][5].

E-House Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Grid modernization & resilience mandates +1.4% North America, Europe Short-term (≤2 yr)
Data-center power demand surge +1.2% Global Medium-term (2–4 yr)
SF₆ phase-out & digital switchgear transition +0.9% Europe, Asia-Pacific Medium-term (2–4 yr)
Mining & oil-gas electrification +0.8% Middle East, South America Long-term (≥4 yr)
Renewable energy interconnection expansion +0.7% Asia-Pacific, North America Medium-term (2–4 yr)
EHS regulations favoring factory assembly +0.5% Global Short-term (≤2 yr)
Modular hydrogen & battery storage deployments +0.4% Europe, the Middle East Long-term (≥4 yr)


Grid Modernization and Resilience Mandates

The US GRIP program alone allocates USD 10.5 billion to grid hardening, with a significant portion targeting modular substation solutions that can be deployed in weeks rather than months. Canada's Smart Renewables and Electrification Pathways program adds CAD 964 million for grid upgrades through 2028 [1][2]. These programs explicitly prioritize factory-tested, pre-commissioned equipment to reduce field risk — a specification that directly benefits the E-House Market.

Data-Center Power Demand Surge

Global data-center electricity consumption is projected to exceed 1,000 TWh by 2030, according to the IEA [8]. Hyperscale operators such as Amazon Web Services and Microsoft require rapid, repeatable power delivery modules that match the pace of server rack deployment. Pre-engineered e-houses with integrated medium-voltage switchgear and step-down transformers have become the de facto standard for these campuses, cutting energization timelines from 14 months to under 16 weeks.

SF₆ Phase-Out and Digital Switchgear Transition

The European Commission's revised F-Gas Regulation targets a complete ban on SF₆ in new medium-voltage switchgear by 2030, affecting an installed base valued at over EUR 4 billion [3]. Equipment manufacturers are embedding vacuum and clean-air circuit breakers into modular e-house designs, creating a replacement cycle that benefits the E-House Market throughout the forecast period.

Mining and Oil-Gas Electrification

The International Council on Mining and Metals estimates that mine electrification could reduce sector emissions by 30% by 2040 [9]. Remote mine sites in Australia, Chile, and sub-Saharan Africa increasingly rely on containerized e-houses because traditional construction is impractical in those environments. This driver carries particular weight for the E-House Market in South America and the Middle East & Africa region.


Restraints Impact Analysis

Restraint estimates reflect directional headwinds and are not mechanically subtracted from the CAGR. They represent friction factors identified through supply-side interviews and regulatory analysis.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High upfront capital cost versus stick-built –0.6% Emerging markets Short-term (≤2 yr)
Logistics and transport limitations for large modules –0.5% Global Medium-term (2–4 yr)
Skilled-labor shortages in factory assembly –0.4% North America, Europe Short-term (≤2 yr)
Permitting and standardization fragmentation –0.3% Asia-Pacific, South America Long-term (≥4 yr)
Cybersecurity risks in digitally integrated modules –0.2% Global Medium-term (2–4 yr)


High Upfront Capital Cost

Although life-cycle economics favor modular e-houses over field-built substations, initial procurement costs can run 15–20% higher for equivalent MVA ratings, according to EPRI analysis . Budget-constrained utilities in Southeast Asia and sub-Saharan Africa often revert to conventional designs, temporarily dampening adoption rates in the E-House Market.

Logistics and Transport Limitations

A fully assembled e-house module can weigh 40–80 metric tons and exceed standard road-gauge dimensions, requiring specialized heavy-haul permits and, in landlocked regions, rail or barge coordination . These constraints add 8–12% to total installed cost and extend delivery schedules by four to six weeks in mountainous or island geographies.


E-House Market Opportunities

Modular Hydrogen Electrolysis Plants

Green-hydrogen projects from NEOM to Rotterdam require dedicated medium-voltage power distribution hubs that pair well with containerized e-house designs. The Hydrogen Council estimates USD 700 billion in cumulative hydrogen investment by 2030, a portion of which will flow into balance-of-plant electrical infrastructure [12].

Emerging-Market Grid Access Programs

Sub-Saharan Africa's electricity access rate stands at only 51%, per the World Bank [18]. National electrification roadmaps in Nigeria, Kenya, and Ethiopia are specifying modular substations for rural distribution, opening a new demand corridor within the E-House Market.

Drone-Based Inspection and Digital Twin Integration

Coupling e-house modules with real-time monitoring platforms and digital twins allows predictive maintenance that cuts unplanned outages by up to 35%, according to CIGRÉ studies [19]. OEMs that bundle embedded IoT sensors with their enclosures gain a service-revenue annuity beyond the initial hardware sale.

Data-Center Edge Deployments

Edge computing facilities — typically 1–5 MW — rely on self-contained power rooms identical in architecture to standard e-houses. projects that 75% of enterprise data will be processed at the edge by 2028, creating a high-volume, standardized product tier for the E-House Market .

Circular-Economy Retrofit and Redeployment Models

Lease-and-redeploy business models for temporary and relocatable e-houses reduce waste and lower the total cost of ownership. Operators in the oil-and-gas sector already rotate modules between wellpad sites, a model that can extend to mining, construction, and disaster-recovery applications.

Current Trade And Geopolitical Scenario For All Commodities, Machinery, And Relevant Domains

Regionalization of Global Supply Chains

By 2026, global trade has become increasingly fragmented due to persistent geopolitical uncertainties. Businesses across the EMEA region are actively shifting toward nearshoring strategies and reducing reliance on distant external partners. This regionalization of supply chains is aimed at strengthening operational resilience, minimizing exposure to trade disruptions, and ensuring continuity of critical infrastructure projects.

 EU–India Free Trade Agreement (FTA)

The EU–India Free Trade Agreement, concluded on 27 January 2026, represents a major structural shift in bilateral trade. The agreement eliminates or significantly reduces tariffs on key industrial goods, including machinery (previously up to 44%) and chemicals (up to 22%). This development is expected to substantially enhance trade flows of E-House components, electrical systems, and engineering goods between the EU and India, improving cost competitiveness and supply flexibility for both markets.

Carbon Border Adjustment Mechanism (CBAM) and Manufacturing Localization

The European Union has officially moved from the transition phase to the definitive implementation period of the Carbon Border Adjustment Mechanism (CBAM). Since E-Houses are predominantly constructed using steel and aluminum, imports into the EU are now subject to carbon pricing aligned with the EU Emissions Trading System (ETS).

As a result, a significant trade pivot is underway. Mobile (containerized) E-Houses are increasingly being manufactured within the EU or in low-carbon “green steel” production zones, such as the Nordic countries. This shift helps manufacturers avoid high carbon-related import levies typically associated with steel sourced from carbon-intensive regions like China and India.

Net-Zero Industry Act (NZIA) and Domestic Manufacturing Mandates

Under the EU’s Net-Zero Industry Act (NZIA), at least 40% of the Union’s demand for strategic net-zero technologies must be met through domestic production. This includes critical grid infrastructure components such as transformers, switchgear, and power distribution systems. The legislation is accelerating localized manufacturing and strengthening the business case for EU-based E-House production and integration facilities.

Energy Security as a Primary Market Driver

Ongoing geopolitical tensions and Europe’s complete phase-out of Russian energy imports have elevated energy security to a strategic priority. Grid resilience, flexibility, and speed of deployment are now essential requirements. This environment strongly favors mobile and prefabricated E-Houses, which enable rapid deployment in renewable integration, grid reinforcement, and energy transition projects across the region.

Grid Congestion in Key European Hubs

Major European metropolitan and data center hubs—FLAP-D (Frankfurt, London, Amsterdam, Paris, and Dublin)—are facing severe grid congestion. Traditional brick-and-mortar substations often involve lead times of three to five years. In response, regulators and utilities are increasingly mandating prefabricated E-Houses as the standard solution for rapid deployment, enabling faster grid connections and capacity expansion.

Middle East Giga projects and Modular Energy Infrastructure

In the Middle East, megadevelopments such as NEOM and the Red Sea Project are driving large-scale adoption of E-Houses, particularly for energy storage and smart grid integration. The modular and relocatable nature of E-Houses aligns with the sustainability goals of these projects, allowing scalability without permanent environmental disruption or long-term land impact.

Localization Policies and Shift to Service-Led Models in the Middle East

Countries such as Saudi Arabia and the UAE have introduced stringent local content requirements, including programs like Saudi Aramco’s iktva initiative. These policies have compelled global E-House suppliers to transition from exporting fully assembled units to establishing local assembly operations. Consequently, the market is shifting away from finished product trade toward service-oriented offerings, including design engineering, system integration, and project consultation.

Middle East Investment Momentum

The Middle East is projected to attract over USD 100 billion in annual investment by 2026, with a strong focus on energy infrastructure, digital assets (including data centers), and advanced manufacturing. This sustained investment wave is significantly boosting demand for E-House solutions, particularly in Saudi Arabia and the UAE, where speed, modularity, and localization are critical success factors.

Safety and Liability Regulations

Legal frameworks and safety regulations impact the deployment and operation of robotics systems, particularly in areas with potential risks to humans or the environment. Example: Occupational safety regulations in industrial settings require adherence to specific safety standards for robotic systems to ensure worker safety.

Data Privacy and Security

Data protection and privacy laws influence the collection, use, and sharing of data generated by robotics systems, particularly in sectors such as healthcare and consumer robotics. Example: The California Consumer Privacy Act (CCPA) in the United States establishes requirements for businesses that handle personal data, including those involving consumer robotics.
E-House Market Future Outlook

Electrification Supercycle

The IEA's World Energy Outlook 2024 projects global electricity demand to rise by 75% between 2023 and 2050 [22]. Every new gigawatt of generation or storage capacity requires switchgear, transformers, and protection systems — the core components housed inside e-houses. This structural tailwind will sustain the E-House Market well beyond 2035.

AI-Enabled Predictive Operations

Embedded sensor arrays and edge-computing controllers are transforming e-houses from passive enclosures into intelligent nodes. Predictive analytics can forecast busbar hotspot failures 72 hours in advance, reducing unplanned downtime by up to 40% according to CIGRÉ Working Group B3.47 [19]. OEMs that ship "smart-ready" modules will command premium pricing.

Platform-Based Procurement Models

Digital procurement platforms — where utilities configure, price, and order e-houses online — are compressing sales cycles from six months to six weeks. Schneider Electric's EcoStruxure configurator and ABB's modular-solutions portal exemplify this shift, which lowers customer-acquisition costs and expands access to mid-tier buyers within the E-House Market.

ESG and Sustainability Reporting Pressure

Scope 3 reporting frameworks under the EU Corporate Sustainability Reporting Directive (CSRD) require infrastructure developers to document the embodied carbon of electrical installations [23]. Factory-assembled e-houses produce a verifiable carbon footprint that is 20–30% lower than equivalent field-built structures, giving them a distinct advantage in ESG-sensitive procurement decisions.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific ~35% of 2025 revenue UHV corridors, RDSS distribution upgrades
North America ~24% of 2025 revenue Grid resilience, data-center campuses
Europe ~22% of 2025 revenue SF₆ phase-out, offshore wind substations
Middle East & Africa CAGR ~10.2% (2026–2035) NEOM megaprojects, mining and electrification
South America ~8% of 2025 revenue Copper/lithium mining, renewables
Total USD 1.82 Billion (2025) —

The E-House Market exhibits a geographically diversified demand base, with infrastructure investment cycles and resource-extraction activity defining regional trajectories.


North America

Country Key Metric Key Driver
US ~72% of regional revenue GRIP funding, hyperscale data centers
Canada CAGR ~6.8% Critical-mineral mining in Ontario/Québec
Mexico ~USD 0.04 Billion (2025) Nearshoring manufacturing clusters


US utilities filed over 2,600 GW of interconnection requests in 2023 alone, according to Lawrence Berkeley National Laboratory, and modular e-houses are the preferred solution for rapid substation construction at solar and wind collection points . Canada's critical minerals strategy adds further tailwinds as new nickel and lithium processing facilities require plug-and-play electrical rooms.

Europe

Country Key Metric Key Driver
Germany ~26% of regional revenue Energiewende, industrial decarbonization
UK CAGR ~6.5% Offshore wind grid connections
France ~USD 0.06 Billion (2025) Nuclear fleet refurbishment
Italy ~11% of regional revenue Renewable energy auction pipeline
Spain CAGR ~6.2% Solar PV interconnection
Nordic Countries ~10% of regional revenue Data-center corridor expansion
Russia ~USD 0.03 Billion (2025) Oil-gas upstream electrification
Rest of Europe CAGR ~5.8% General grid upgrades


The E-House Market in Europe is tightly linked to the F-Gas Regulation timeline, which mandates SF₆-free medium-voltage switchgear in new installations by 2030 [3]. German TSOs have earmarked EUR 25 billion for grid expansion through 2030 under the Netzentwicklungsplan, and pre-assembled substation modules are central to meeting those deployment deadlines.

Asia-Pacific

Country Key Metric Key Driver
China ~42% of regional revenue UHV grid corridors, renewables
India CAGR ~8.5% RDSS, solar park substations
Japan ~USD 0.05 Billion (2025) Grid resilience post-Fukushima reforms
South Korea ~8% of regional revenue Semiconductor fab power systems
ASEAN CAGR ~7.9% Industrial-zone electrification
Rest of Asia-Pacific ~6% of regional revenue Mining, general infrastructure


China's State Grid Corporation commissioned over 40 modular substation projects along UHV corridors in 2024, and India's RDSS program targets smart-metered distribution upgrades across 250 million households, both creating sustained demand for the E-House Market in the region .

South America

Country Key Metric Key Driver
Brazil ~52% of regional revenue Pre-salt offshore, solar farms
Argentina CAGR ~7.4% Vaca Muerta shale, lithium triangle
Rest of South America ~USD 0.03 Billion (2025) Copper mining in Chile/Peru


Chile and Peru collectively account for over 40% of global copper output, and mine operators are replacing diesel gensets with grid-connected modular e-houses to meet decarbonization commitments under national climate pledges [9].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~34% of regional revenue NEOM, Red Sea Project
UAE CAGR ~9.8% Industrial diversification, solar parks
South Africa ~18% of regional revenue Eskom unbundling, mining
Egypt CAGR ~8.6% Suez Canal Economic Zone
Rest of MEA ~USD 0.03 Billion (2025) Oil-gas, mining exploration


Saudi Arabia's Vision 2030 infrastructure pipeline exceeds USD 1 trillion in planned spending, and e-house modules are specified across NEOM's industrial clusters for speed-to-power requirements [21]. The E-House Market in the Middle East benefits from extreme ambient-temperature ratings that factory testing can guarantee, but field assembly struggles to replicate.


E-House Market By Region, 2025-2035

E-House Market Segmentation

By Solution

Segment Key Metric Primary Demand Driver
Fixed E-House ~58% of 2025 revenue Utility substations, industrial plants
Mobile Substation CAGR ~6.6% (2026–2035) Emergency restoration, temporary power


Fixed e-house units dominate the E-House Market because utilities and industrial operators require permanent, type-tested enclosures rated for 30+ year service lives. These units typically house 12–36 kV switchgear bays, SCADA interfaces, and HVAC systems designed for continuous duty. Mobile substations, while smaller in absolute revenue, are gaining traction as grid operators stockpile trailer-mounted units for storm response and planned maintenance outages, shortening restoration times from days to hours.

By Voltage Rating

Segment Key Metric Primary Demand Driver
Low Voltage ~USD 0.33 Billion (2025) Data-center UPS distribution
Medium Voltage ~60% of 2025 revenue Distribution grid, industrial feeders
High Voltage CAGR ~8.2% (2026–2035) Transmission substations, renewables


Medium-voltage configurations remain the backbone of the E-House Market, serving 6.6–36 kV distribution needs across utilities and industrial campuses. High-voltage units (≥72.5 kV) are growing fastest as renewable-energy developers co-locate step-up substations with wind and solar farms in remote areas where modular construction delivers the greatest schedule advantage.

By Application

Segment Key Metric Primary Demand Driver
Utilities ~53% of 2025 revenue Grid expansion, smart-grid upgrades
Industrial ~USD 0.22 Billion (2025) Manufacturing, chemicals processing
Oil and Gas CAGR ~6.9% (2026–2035) Upstream electrification, LNG terminals
Mining ~8% of 2025 revenue Underground and open-pit electrification
Data Centers CAGR ~8.8% (2026–2035) Hyperscale and edge deployments
Others ~USD 0.07 Billion (2025) Renewables, hydrogen, rail


Utility-sector procurement defines the volume floor for the E-House Market, as distribution and transmission operators worldwide replace aging open-air switchyards with enclosed modular solutions. Data-center deployments are the fastest-growing application, because hyperscale operators value the ability to pre-commission identical power blocks and replicate them across multiple campus locations with minimal re-engineering.

By Component

Segment Key Metric Primary Demand Driver
Switchgear ~46% of 2025 revenue Core power distribution function
Transformer ~USD 0.51 Billion (2025) Step-up/step-down voltage conversion
Protection & Control Systems CAGR ~9.0% (2026–2035) Digitalization and IEC 61850 adoption
Others (busbar, HVAC, fire suppression) ~10% of 2025 revenue Regulatory and environmental compliance


By Deployment Mode

Segment Key Metric Primary Demand Driver
Permanent ~73% of 2025 revenue Long-life utility and industrial assets
Temporary / Relocatable CAGR ~6.5% (2026–2035) Event power, disaster recovery and mining


Competitive Benchmarking

The E-House Market has medium concentration, with the top five vendors contributing an estimated 38–45% of global revenue. The Herfindahl-Hirschman Index (HHI) is within the range of 800-1,200, which means it is competitive, but not fragmented. Regional fabricators in the Middle East and Asia-Pacific exert price pressure on global OEMs, driving the latter toward value-added digital integration and full-turnkey service models.

Company Est. Revenue Share Range Key Offerings for the E-House Market Strategic Positioning
ABB Ltd. ~8–11% MV/HV modular substations, digital switchgear Global full-portfolio leader
Siemens Energy ~7–10% NXAIR+ switchgear, gas-insulated modules European technology leader
Schneider Electric ~6–9% EcoStruxure-enabled modular enclosures Digital integration focus
Eaton Corporation ~5–8% Power distribution assemblies, UPS modules Data-center specialization
Powell Industries ~3–5% Custom-engineered MV switchgear houses North American niche leader
WEG S.A. ~2–4% Transformer-integrated e-houses South American price-performance
Aktif Elektroteknik ~2–4% Compact MV/LV modules Turkish export hub
TGOOD Electric ~2–3% Prefabricated modular substations Chinese domestic & Belt and Road
Delta Star Inc. ~1–3% Mobile transformer substations Utility emergency response
Elgin Power Solutions ~1–2% Skid-mounted power centers Oil-gas and mining applications


Recent News & Developments


  • Eaton (June 2024): Introduced a containerized power-distribution unit purpose-built for 50 MW data-center blocks, cutting energization lead time to 12 weeks [8].


  • European Commission (October 2023): Published the revised F-Gas Regulation implementing rules, confirming the 2030 deadline for SF₆-free MV switchgear in new installations across the EU [3].


E-House Market Report Scope

Report Attribute/Metric Details
Market Scope Global E-House Market, including fixed e-houses, mobile substations, and related electrical enclosures
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 1.82 Billion
Market Size in 2035 USD 3.34 Billion
CAGR (2026–2035) 6.3%
Fastest Growing Segments Application ( Data-center deployments 8.8% CAGR)
Regions Covered Middle East & Africa (CAGR ~10.2%); North America, Europe, APAC, South America, MEA
Companies Profiled 10 (ABB, Siemens Energy, Schneider Electric, Eaton, Powell Industries, WEG, Aktif Elektroteknik, TGOOD Electric, Delta Star, Elgin Power Solutions)
Valuation Currency USD Billion
Methodology Combination of bottom-up revenue modeling, primary interviews (180+ stakeholders), secondary research, and proprietary MRFR estimation frameworks

FAQs

What lead time should a buyer expect when ordering a custom e-house?
Typical lead times range from 16 to 26 weeks, depending on voltage class and switchgear configuration. Early engagement with the OEM during the FEED phase can shave four to six weeks off delivery .
How do lifecycle costs of modular e-houses compare to stick-built substations?
Over a 25-year service life, e-houses deliver 12–18% lower total cost of ownership due to reduced field labor and faster commissioning . Upfront procurement costs are higher, but operational savings offset them within five years.
What cybersecurity standards apply to digitally integrated e-house modules?
IEC 62351 and NERC CIP standards govern communication security for protection relays and SCADA interfaces embedded in e-houses [17]. Buyers should verify OEM compliance certificates before procurement.
Can e-houses operate in extreme ambient temperatures?
Factory-tested modules are routinely rated for –40 °C to +55 °C ambient ranges using integrated HVAC and Arctic-grade insulation . Desert and Arctic deployments require enhanced cooling or heating packages.
What financing structures are available for temporary e-house deployments?
Lease-to-own and rental-pool models are increasingly common for relocatable units in mining and oil-gas sectors [9]. These structures convert capital expenditure into operating expenditure.
How does the SF₆ phase-out affect existing e-house installations?
Existing SF₆ equipment can remain in service, but new installations in the EU must use alternatives by 2030 [3]. Retrofit kits allow vacuum-breaker upgrades inside existing enclosures.
What role do digital twins play in e-house lifecycle management?
Digital twins enable real-time thermal and electrical simulation, cutting diagnostic time by up to 60% [19]. They are becoming a standard OEM offering bundled with new module shipments.    
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of electrical infrastructure databases, energy sector journals, engineering publications, and authoritative energy organizations. Key sources included the US Department of Energy (DOE), Federal Energy Regulatory Commission (FERC), International Electrotechnical Commission (IEC), Institute of Electrical and Electronics Engineers (IEEE), National Electrical Manufacturers Association (NEMA), International Energy Agency (IEA), US Energy Information Administration (EIA), European Network of Transmission System Operators for Electricity (ENTSO-E), EU Eurostat Energy Database, World Energy Council, Occupational Safety and Health Administration (OSHA), National Fire Protection Association (NFPA), and national energy ministry reports from key markets. These sources were used to collect power infrastructure statistics, regulatory compliance data, safety standards, grid modernization trends, and market landscape analysis for mobile, semi-mobile, and fixed E-House solutions across switchgear, transformer, UPS, and other component categories.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of Engineering, project directors, and business development leaders from E-House manufacturers, electrical equipment OEMs, and modular construction providers comprised the supply-side sources. Electrical engineers, project managers, procurement leads from oil and gas operators, mining companies, utility providers, and infrastructure contractors in the industrial, transportation, and power utilities sectors comprised demand-side sources. Market segmentation was verified, project pipeline timelines were confirmed, and insights regarding specification requirements, procurement cycles, and competitive tendering dynamics were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (38%), Europe (30%), Asia-Pacific (25%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping and project deployment analysis. The methodology included:

Identification of 50+ key manufacturers and system integrators across North America, Europe, Asia-Pacific, Middle East & Africa, and South America

Product mapping across mobile, semi-mobile, and fixed E-House types, covering switchgear, transformer, UPS, control panel, busway, HVAC systems, and other components

Analysis of reported and modeled annual revenues specific to E-House and modular substation portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (project volume × ASP by application and region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for oil & gas, mining, power utilities, transportation, and other end-use sectors

Key Adjustments Made:

Modified all percentage breakdowns in primary research section

Replaced medical/aesthetic sources with electrical infrastructure, energy, and industrial safety organizations

Updated component and application categories to match E-House market segments (Mobile/Semi-Mobile/Fixed types, Oil & Gas/Mining/Power Utilities applications)

Maintained consistent methodology structure while adapting to electrical power distribution industry context

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















