Dental Lasers Market (2026 - 2035)

ID: MRFR/HC/5906-HCR 200 Pages Vikita Thakur Last Updated: October 27, 2026
Dental Lasers Market Research Report By Application (Periodontal Treatment, Crown Lengthening, Teeth Whitening, Soft Tissue Surgery, Endodontic Procedures), By Type (Diode Laser, YAG Laser, CO2 Laser, Nd:YAG Laser, Erbium Laser), By End Use (Dental Clinics, Hospitals, Research Laboratories, Academic Institutions), By Configuration (Portable, Standalone, Tabletop, Robotic) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2026 To 2035
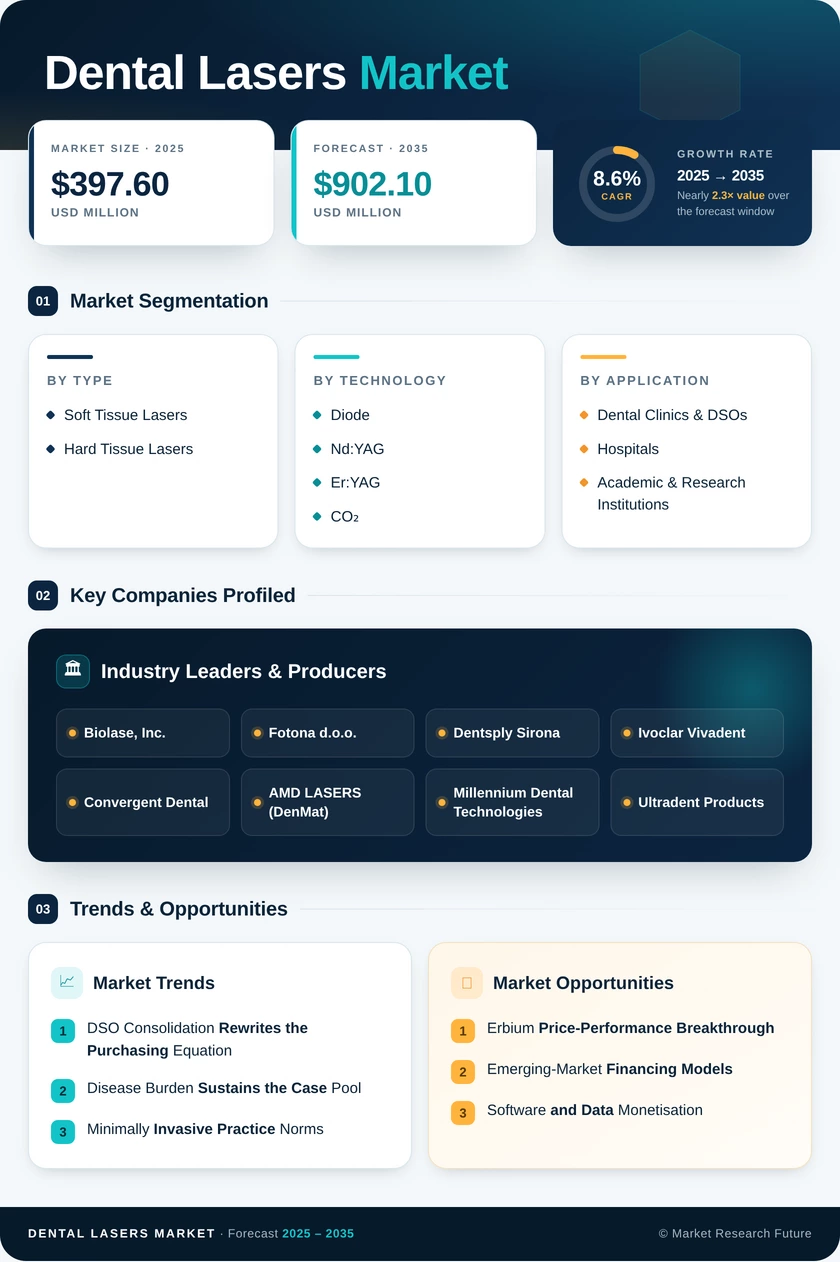
Dental Lasers Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.60%
2025 Market SizeUSD 397.6 Million
2035 Market SizeUSD 902.1 Million
Key Players
Biolase, Inc.
Fotona d.o.o.
Dentsply Sirona
Ivoclar Vivadent
Convergent Dental
AMD LASERS
Opportunities
  • Erbium Price-Performance Breakthrough
  • Emerging-Market Financing Models
  • Software and Data Monetisation
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 DSO Consolidation and Standardised Capital Purchasing |
    2. 4.2 Periodontal and Peri-Implant Disease Prevalence |
    3. 4.3 Minimally Invasive Practice Norms |
    4. 4.4 Product Refinement and Indication Expansion
  5. 5 Restraints Impact Analysis |
    1. 5.1 Capital Cost and Financing Barriers |
    2. 5.2 Reimbursement Ambiguity |
    3. 5.3 Clinician Training Gaps
  6. 6 Opportunities |
    1. 6.1 Erbium Price-Performance Breakthrough |
    2. 6.2 Emerging-Market Financing Models |
    3. 6.3 Software and Data Monetisation |
    4. 6.4 Peri-Implantitis Maintenance Category |
    5. 6.5 Academic Channel Development
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Software-Defined Consoles |
    2. 8.2 Consumables and Service Economics |
    3. 8.3 Evidence Consolidation and Reimbursement |
    4. 8.4 Manufacturing Shift and Price Compression
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Product Type | |
      1. 9.1.1 Soft Tissue Lasers | |
      2. 9.1.2 Hard Tissue Lasers |
    2. 9.2 By Technology | |
      1. 9.2.1 Diode | |
      2. 9.2.2 Nd:YAG | |
      3. 9.2.3 Er:YAG | |
      4. 9.2.4 CO₂ |
    3. 9.3 By Application | |
      1. 9.3.1 Conservative Dentistry | |
      2. 9.3.2 Endodontic Treatment | |
      3. 9.3.3 Oral Surgery | |
      4. 9.3.4 Periodontics | |
      5. 9.3.5 Implantology |
    4. 9.4 By End User | |
      1. 9.4.1 Dental Clinics & DSOs | |
      2. 9.4.2 Hospitals | |
      3. 9.4.3 Academic & Research Institutions
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Biolase, Inc. | |
      2. 10.3.2 Fotona d.o.o. | |
      3. 10.3.3 Dentsply Sirona | |
      4. 10.3.4 Ivoclar Vivadent | |
      5. 10.3.5 Convergent Dental | |
      6. 10.3.6 AMD LASERS (DenMat) | |
      7. 10.3.7 Millennium Dental Technologies | |
      8. 10.3.8 Ultradent Products | |
      9. 10.3.9 A.R.C. Laser GmbH | |
      10. 10.3.10 Gigaa Laser | |
      11. 10.3.11 Zolar Technology | |
      12. 10.3.12 Mectron S.p.A.
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Valuation Currency & Unit |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Dental Lasers Market Size & Forecast, by Revenue (USD Million), 2021–2035 |
  17. TABLE 2 Global Dental Lasers Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Dental Lasers Market Size, by Region, 2021–2035 (USD Million) |
  21. TABLE 6 North America Dental Lasers Market Size, by Country, 2021–2035 (USD Million) |
  22. TABLE 7 Europe Dental Lasers Market Size, by Country, 2021–2035 (USD Million) |
  23. TABLE 8 Asia-Pacific Dental Lasers Market Size, by Country, 2021–2035 (USD Million) |
  24. TABLE 9 South America Dental Lasers Market Size, by Country, 2021–2035 (USD Million) |
  25. TABLE 10 Middle East & Africa Dental Lasers Market Size, by Country, 2021–2035 (USD Million) |
  26. TABLE 11 Global Dental Lasers Market Size, by Product Type, 2021–2035 (USD Million) |
  27. TABLE 12 Global Dental Lasers Market Size, by Technology, 2021–2035 (USD Million) |
  28. TABLE 13 Global Dental Lasers Market Size, by Application, 2021–2035 (USD Million) |
  29. TABLE 14 Global Dental Lasers Market Size, by End User, 2021–2035 (USD Million) |
  30. TABLE 15 Competitive Benchmarking Matrix – Global Dental Lasers Market, 2026 |
  31. TABLE 16 Company Profiles – Key Players, Global Dental Lasers Market |
  32. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 |
  33. TABLE 18 Report Scope & Methodology Summary |
  34. TABLE 19 Detailed Sources & Citations Index |
  35. TABLE 20 North America Dental Lasers Market Size, by Technology, 2021–2035 (USD Million) |
  36. TABLE 21 Europe Dental Lasers Market Size, by Application, 2021–2035 (USD Million) |
  37. TABLE 22 Asia-Pacific Dental Lasers Market Size, by End User, 2021–2035 (USD Million)
  38. 16 LIST OF FIGURES |
  39. FIGURE 1 Global Dental Lasers Market – Market Dynamics Overview (Drivers, Restraints, Opportunities) |
  40. FIGURE 2 Industry Value Chain Analysis – Dental Lasers |
  41. FIGURE 3 Porter's Five Forces Analysis – Dental Lasers |
  42. FIGURE 4 Global Dental Lasers Market Size Trend, 2021–2035 (USD Million) |
  43. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 |
  44. FIGURE 6 Market Share by Product Type, 2025 vs 2035 |
  45. FIGURE 7 Market Share by Technology, 2025 vs 2035 |
  46. FIGURE 8 Market Share by Application, 2025 vs 2035 |
  47. FIGURE 9 Market Share by End User, 2025 vs 2035 |
  48. FIGURE 10 Regional Share Distribution, 2025 |
  49. FIGURE 11 Regional CAGR Comparison, 2026–2035 |
  50. FIGURE 12 North America Country-Level Share Breakdown, 2025 |
  51. FIGURE 13 Asia-Pacific Country-Level Growth Comparison, 2026–2035 |
  52. FIGURE 14 Competitive Landscape – Estimated Revenue Share Bands, 2026 |
  53. FIGURE 15 Competitive Positioning Matrix – Capability vs Price Tier |
  54. FIGURE 16 Installed Base Replacement Cycle Model, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeSoft Tissue Lasers; Hard Tissue LasersSoft Tissue LasersHard Tissue Lasers
By TechnologyDiode; Nd:YAG; Er:YAG; CO₂DiodeEr:YAG
By ApplicationConservative Dentistry; Endodontic Treatment; Oral Surgery; Periodontics; ImplantologyOral SurgeryImplantology
By End UserDental Clinics & DSOs; Hospitals; Academic & Research InstitutionsDental Clinics & DSOsHospitals
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
Soft Tissue LasersEntry-tier pricing keeps this the default first purchase for general practice
Hard Tissue LasersFalling erbium component costs are opening the drill-substitution use case


Product-type dynamics hinge on price accessibility. Soft tissue systems will keep the volume lead through 2035, but the revenue gap narrows steadily as hard-tissue-capable consoles reach mid-market price points and clinicians grow comfortable performing cavity preparation without rotary backup.

By Technology

Sub-SegmentKey Trend
DiodeCommoditising rapidly under pressure from Asian manufacturers
Nd:YAGProtocol-locked periodontal applications sustain a defensible niche
Er:YAGFastest-growing wavelength on hard tissue capability and thermal safety
CO₂Precision surgical positioning with strong haemostatic performance


Wavelength competition increasingly favours dual-wavelength chassis that let one purchase cover both soft and hard tissue indications. Utilisation economics reward breadth, and vendors that cannot offer multi-wavelength configurations risk losing the practice-level standardisation decision entirely.

By Application

Sub-SegmentKey Trend
Conservative DentistrySelective caries removal protocols gaining curriculum support
Endodontic TreatmentDisinfection efficacy evidence strengthening adoption
Oral SurgeryLargest application on clear haemostatic and healing advantages
PeriodonticsPocket decontamination driving steady procedure-volume growth
ImplantologyPeri-implantitis maintenance emerging as a distinct category


Application breadth determines console utilisation, which determines repeat purchase. Implantology's rise is structural rather than cyclical — every implant placed today becomes a maintenance obligation for the next two decades, creating compounding downstream procedure demand.

By End User

Sub-SegmentKey Trend
Dental Clinics & DSOsFleet standardisation converts individual sales into multi-unit contracts
HospitalsMaxillofacial and inpatient dentistry units adding photonic capability
Academic & Research InstitutionsCurriculum expansion shaping next-generation prescribing behaviour


End-user structure explains regional divergence more reliably than population or income data. Regions where group practice models dominate scale installed bases quickly; where solo ownership persists, adoption depends on individual clinician conviction and remains correspondingly slower.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.