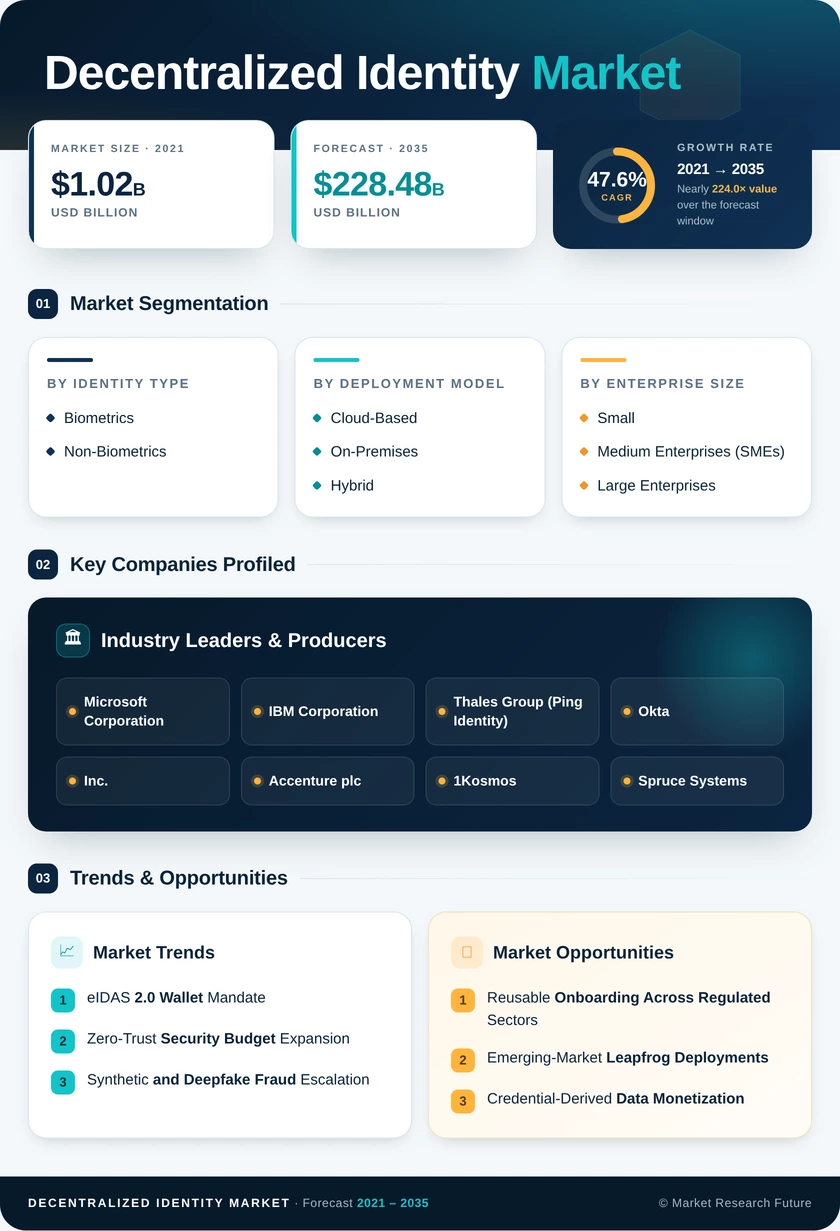
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Identity Type | Biometrics; Non-Biometrics | Biometrics (58.7% share, 2025) | Non-Biometrics (19.4% CAGR, 2026–2035) |
| By Deployment Model | Cloud-Based; On-Premises; Hybrid | Cloud-Based (54.9% share, 2025) | Hybrid (16.5% CAGR, 2026–2035) |
| By Enterprise Size | Small and Medium Enterprises (SMEs); Large Enterprises | Large Enterprises (62.4% share, 2025) | Small and Medium Enterprises (SMEs) (16.6% CAGR, 2026–2035) |
| By End-user Industry | Banking, Financial Services and Insurance (BFSI); IT and Telecommunications; Retail and E-Commerce; Healthcare; Media and Entertainment; More | Banking, Financial Services and Insurance (BFSI) (29.9% share, 2025) | Healthcare (21.8% CAGR, 2026–2035) |
Market Segmentation Overview
By Identity Type
| Sub-Segment | Key Trend |
| Biometrics | Liveness detection and anti-spoofing bound to on-device matching |
| Non-Biometrics | Cryptographic attestation and device signals for privacy-restricted jurisdictions |
Biometrics holds the largest position because binding a credential to a living person, rather than a device, is what high-value financial and border workflows actually require. Non-Biometrics grows fastest from a narrower base, serving deployers in Illinois, Texas, and comparable statutory environments where physical-trait capture carries litigation exposure. Buyers increasingly procure both and let the presentation flow branch by jurisdiction, which is why neither sub-segment displaces the other over the forecast.
By Deployment Model
| Sub-Segment | Key Trend |
| Cloud-Based | Elastic compute absorbing bursty zero-knowledge proof generation |
| On-Premises | Sovereign registry residency for defence and central banking |
| Hybrid | Firewalled registries paired with public key resolution |
Cloud-Based leads on economics: proof workloads spike during batch issuance and idle between, and managed services also carry patching and audit obligations in-house teams would otherwise staff. Hybrid grows fastest because sovereign-data buyers want the reach of public key resolution without moving sensitive registries outside their boundary — the pattern most central bank digital currency pilots have settled on. On-Premises holds a stable but shrinking share, concentrated in defence credentialing where no external dependency is permitted.
By Enterprise Size
| Sub-Segment | Key Trend |
| Small and Medium Enterprises (SMEs) | Embedded SDKs adding credential flows without dedicated security teams |
| Large Enterprises | Decentralized identifiers layered alongside existing OAuth and SAML rails |
Large Enterprises supply the majority of revenue because their employee, contractor, and supplier populations demand unified credential governance, and they can absorb the six-to-nine-month schema reconciliation that precedes production issuance. Small and Medium Enterprises (SMEs) grow faster since low-code APIs remove that barrier entirely, letting a retailer or staffing firm add credential presentation to an existing portal in weeks. Each cohort helps the other — SMEs widen relying-party coverage, large enterprises fund the issuer infrastructure.
By End-user Industry
| Sub-Segment | Key Trend |
| Banking, Financial Services and Insurance (BFSI) | Reusable customer due diligence across institutions |
| IT and Telecommunications | SIM-swap prevention and subscriber onboarding |
| Retail and E-Commerce | Age assurance under new statutory thresholds |
| Healthcare | Patient-held records and clinician credential portability |
| Media and Entertainment | Content provenance and subscription entitlement control |
| More | Education credentialing, travel, and public sector services |
Banking, Financial Services and Insurance (BFSI) leads because due diligence is duplicated at every institution a customer touches, and reusable attestation removes that cost directly at roughly USD 42 per avoided check. Healthcare grows fastest, propelled by TEFCA and the European Health Data Space moving patient-directed record access from voluntary pilot to regulatory obligation, with locum clinician credentialing delivering the earliest measurable savings. Retail and E-Commerce adoption tracks age-assurance statutes rather than fraud economics, giving it a slower but more predictable curve.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA